Border Checks at the Checkout: Why Europe’s National Marketplaces Are Holding the Line
From Warsaw's parcel lockers to Dutch payment rails, domestic habits and resale platforms are proving far more resilient than Silicon Valley’s vision of a frictionless, pan-European bazaar.

At a distribution centre outside Erfurt in eastern Germany, pallets bound for domestic wardrobes stand opposite consignments destined for regional hubs across Poland and the Czech Republic. For more than a decade, the architectural presumption behind platforms like Berlin-based Zalando was that digital commerce would eventually dissolve Europe’s historical commercial borders. The reality confronting boardrooms from Paris to Warsaw, however, is that continental consumption habits are becoming more distinctly parochial, shaped by deeply entrenched payment customs, national logistics networks, and an increasingly frugal domestic shopper.
Despite three decades of the single market, European retail behaviour remains obstinately localised. In Poland, Allegro continues to command the national e-commerce landscape, insulated by the ubiquitous grey-and-yellow automated lockers of InPost and the ubiquity of Blik, the Polish mobile banking protocol. In the Netherlands and Flanders, Bol preserves its market leadership over global rivals by offering local merchant curation and immediate settlement through iDEAL. These platforms did not triumph simply through brand sentiment; they built defensive moats out of national infrastructure that foreign conglomerates consistently underestimated.
The fortress of domestic rails
These technical distinctions carry profound commercial consequences. German shoppers, notoriously protective of financial privacy and return rights, maintain a durable preference for invoice-based purchasing—settling bills only after goods have been physically inspected and tried on in their living rooms. For apparel platforms, accommodating this practice requires substantial working-capital reserves to absorb return rates that frequently exceed fifty per cent. In France, where retail giant Carrefour and marketplace veteran Cdiscount maintain extensive footprints, consumer preference has steered sharply toward suburban drive-through collection bays rather than paid doorstep courier runs.
The continental shopper is not waiting for a single digital shopping street; convenience in Europe is measured by proximity to an errand run, not an outsourced courier at the gate.
This stubborn reliance on established routines dealt a terminal blow to the first generation of venture-backed rapid grocery couriers. While operations such as Gorillas collapsed or consolidated under sustained cash burns, and Flink drastically narrowed its geographic ambitions to densely populated urban cores, traditional supermarket chains simply digitised their existing physical estate. In Germany, REWE expanded click-and-collect counters; in Spain and Italy, hypermarkets converted back-of-store acreage into regional fulfilment hubs, entirely bypassing the need for dedicated dark stores.
Thrift, resale, and the discounter counter-offensive
Where cross-border shopping has genuinely flourished on the continent, it has done so through an unexpected channel: the formalisation of the peer-to-peer wardrobe. Lithuania-founded Vinted has emerged as an indispensable shopping reflex across France, Spain, and Italy. By standardising shipping rates between national postal operators and stripping away the friction of peer-to-peer dispute resolution, Vinted turned economic anxiety and sustainability rhetoric into a transactional habit. For millions of households navigating sustained food and energy inflation, selling children's outgrown outerwear has become the prerequisite funding mechanism for buying the next season's wardrobe.
At the grocery checkout, that same consumer pragmatism has fortified the traditional hard discounters. Neither rapid-delivery apps nor online supermarket portals have managed to divert the core European weekly shop away from Lidl and Aldi. Instead, the discounters digitised on their own terms. Proprietary smartphone programmes, such as Lidl Plus, avoid the crippling overheads of refrigerated transport fleets entirely; they trade app-exclusive weekly discounts for granular consumer basket data, coaxing price-sensitive shoppers back onto physical linoleum floors.
Ultra-low-cost imports from cross-border Chinese platforms are testing the margins of every mid-tier apparel merchant from Madrid to Stockholm. Yet Europe's regional retail leaders retain an enduring advantage. Between stringent European Union packaging directives, pending carbon tariffs on low-value air freight, and consumers who prize familiar return desks and domestic consumer protection rules, Europe’s shopping culture remains distinctly federal. Continental e-commerce is not coalescing into a single American-style monopoly; it is settling into an interlocking archipelago of national champions, guarded by parcel lockers and protected by local payment rails.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
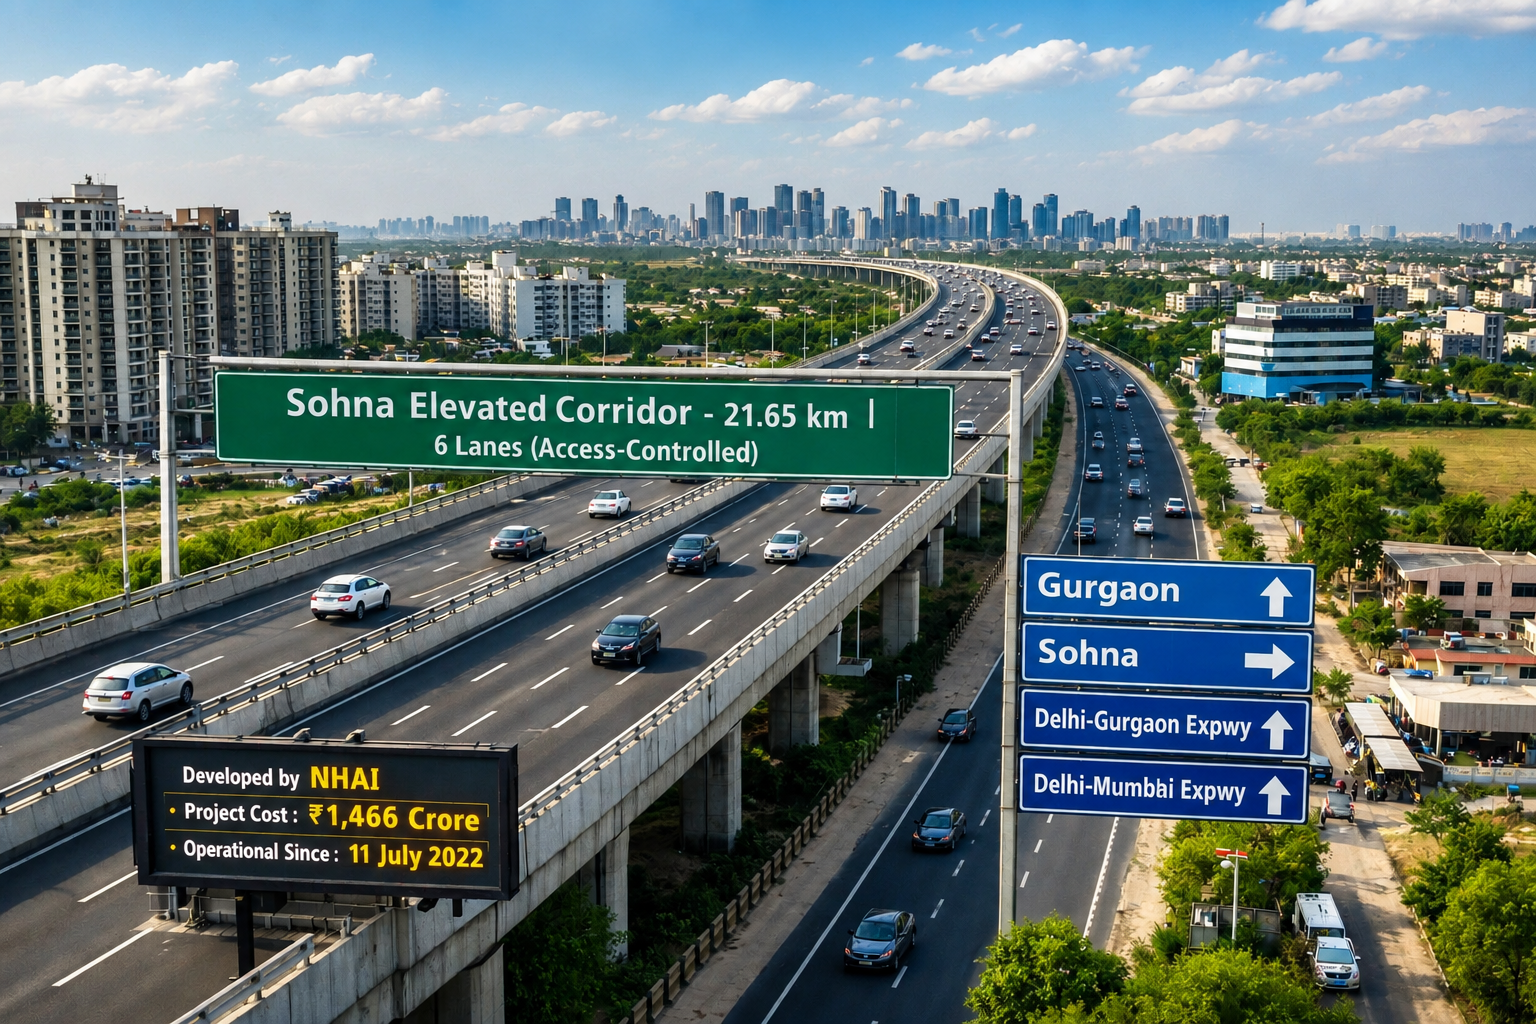
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
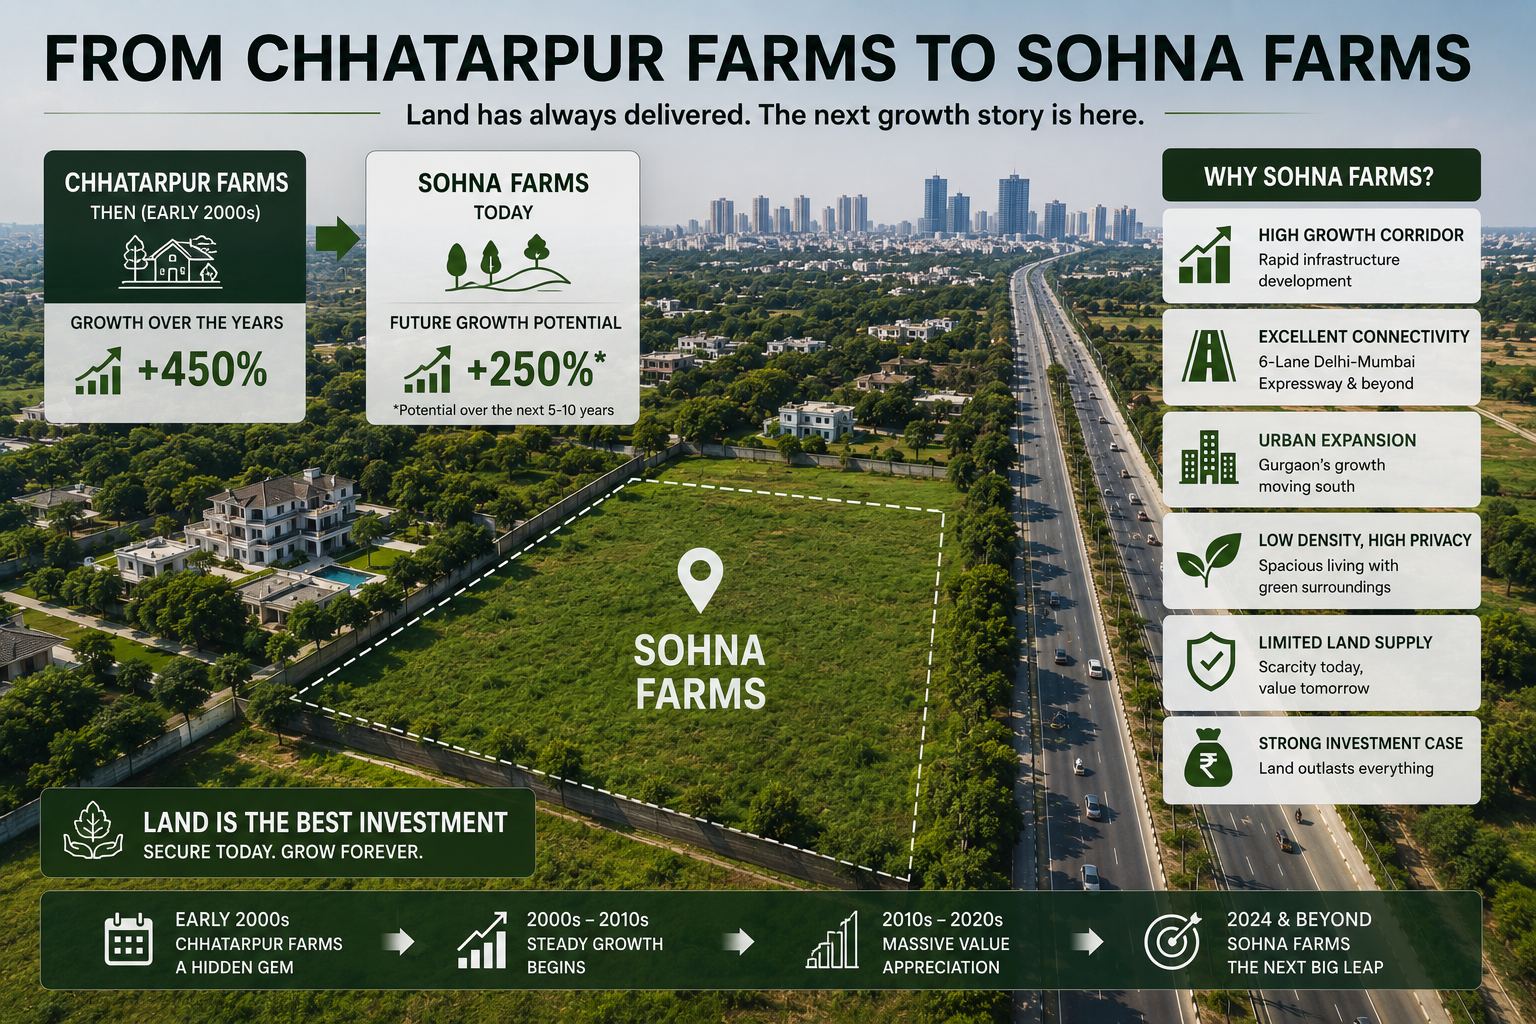
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
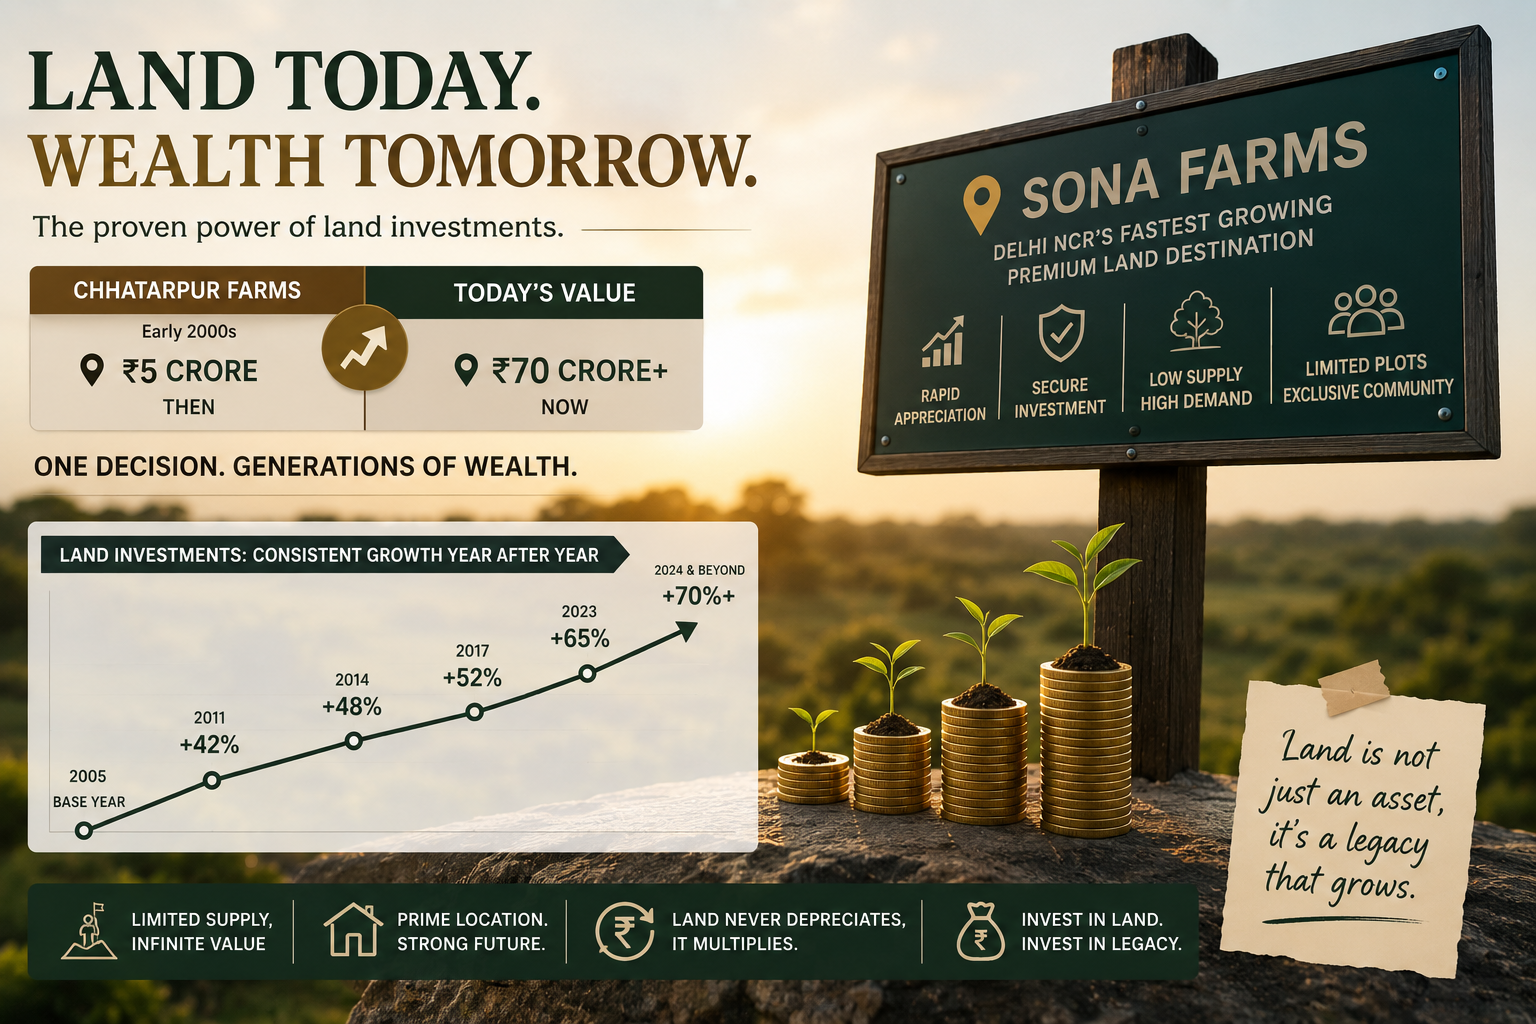
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.