Border Friction and Local Moats: The Enduring Partition of Continental E-Commerce
Rather than collapsing into a monolithic pan-European trading zone, continental retail has settled into fortified regional fiefdoms where domestic logistics networks and entrenched payment habits dictate operating margins.

At Zalando’s vast fulfilment centre in Lahr, near the Upper Rhine, automated shuttle systems sort apparel destined for wardrobes across Germany, France, and Switzerland. Yet the operational seamlessness inside the four walls of the facility conceals an enduring commercial truth: three decades after the creation of the European single market, continental digital trade remains stubbornly fragmented along national lines. For institutional investors who once wagered on a swift, frictionless aggregation of European consumers under a single platform umbrella, the continent’s retail geography has proven far more resistant to centralisation than anticipated.
In Poland, Allegro continues to command more than half of the domestic marketplace sector, holding off well-capitalised incursions from global incumbents by leveraging deeply embedded locker networks and localised consumer loyalty. Across the Low Countries, Bol occupies an equally entrenched position, maintaining dominant market share in Flanders and the Netherlands by tailoring merchant support and vernacular cataloguing to domestic sensibilities. Even in France, where Casino-backed Cdiscount has had to navigate structural reorganisations, local consumer affinity for domestic merchant ecosystems continues to place a ceiling on purely pan-European platforms.
National Bastions and the Marketplace Moat
The economic resilience of these regional platforms stems from capital efficiency rather than brute scale. Building out cross-border inventory buffers across the European Union requires navigating distinct VAT reporting standards, fragmented recycling levies, and wildly disparate last-mile delivery landscapes. While an order travelling from Frankfurt to Milan should theoretically move without impediment, parcel carriers face stark differences in delivery density and transit tolls, making domestic order dispatch structurally cheaper and more dependable.
Food retail has followed an even more conservative trajectory. Following the deflation of the quick-commerce bubble—which saw Berlin-based Gorillas absorbed and survivors like Flink forced to pivot towards disciplined balance sheets—continental grocery giants have reasserted control over digital baskets. Germany’s REWE and the Schwarz Group, parent of Lidl, have largely bypassed speculative delivery infrastructure in favour of highly automated micro-fulfilment hubs and expanded click-and-collect services integrated directly into their existing store footprints. Across France and Spain, Carrefour has similarly reallocated capital expenditure away from rapid-delivery ventures and towards omnichannel store-picking networks that capitalise on existing urban real estate.
The Second-Hand Counterweight and Logistics Realignment
Yet cross-border flows are not entirely stagnant; they are merely flowing through unconventional corridors. Vilnius-headquartered Vinted has emerged as one of the most consequential disrupters of cross-border transport economics between France, Italy, and the Iberian Peninsula. By shifting consumer expectations from expedited home delivery to slower, lower-cost parcel locker networks, the circular fashion platform has demonstrated that European shoppers will willingly cross borders if the economic discount outweighs the convenience premium.
The emergence of this secondary parcel grid, anchored by automated collection lockers across secondary and tertiary towns, suggests that European digital commerce is entering a phase of operational sobriety. The historical ambition of creating a unified, Amazonian digital superhighway from Lisbon to Warsaw has given way to a more pragmatic federation of national and regional leaders, each protected by local logistical moats and consumer habits that no foreign balance sheet has yet managed to dismantle.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
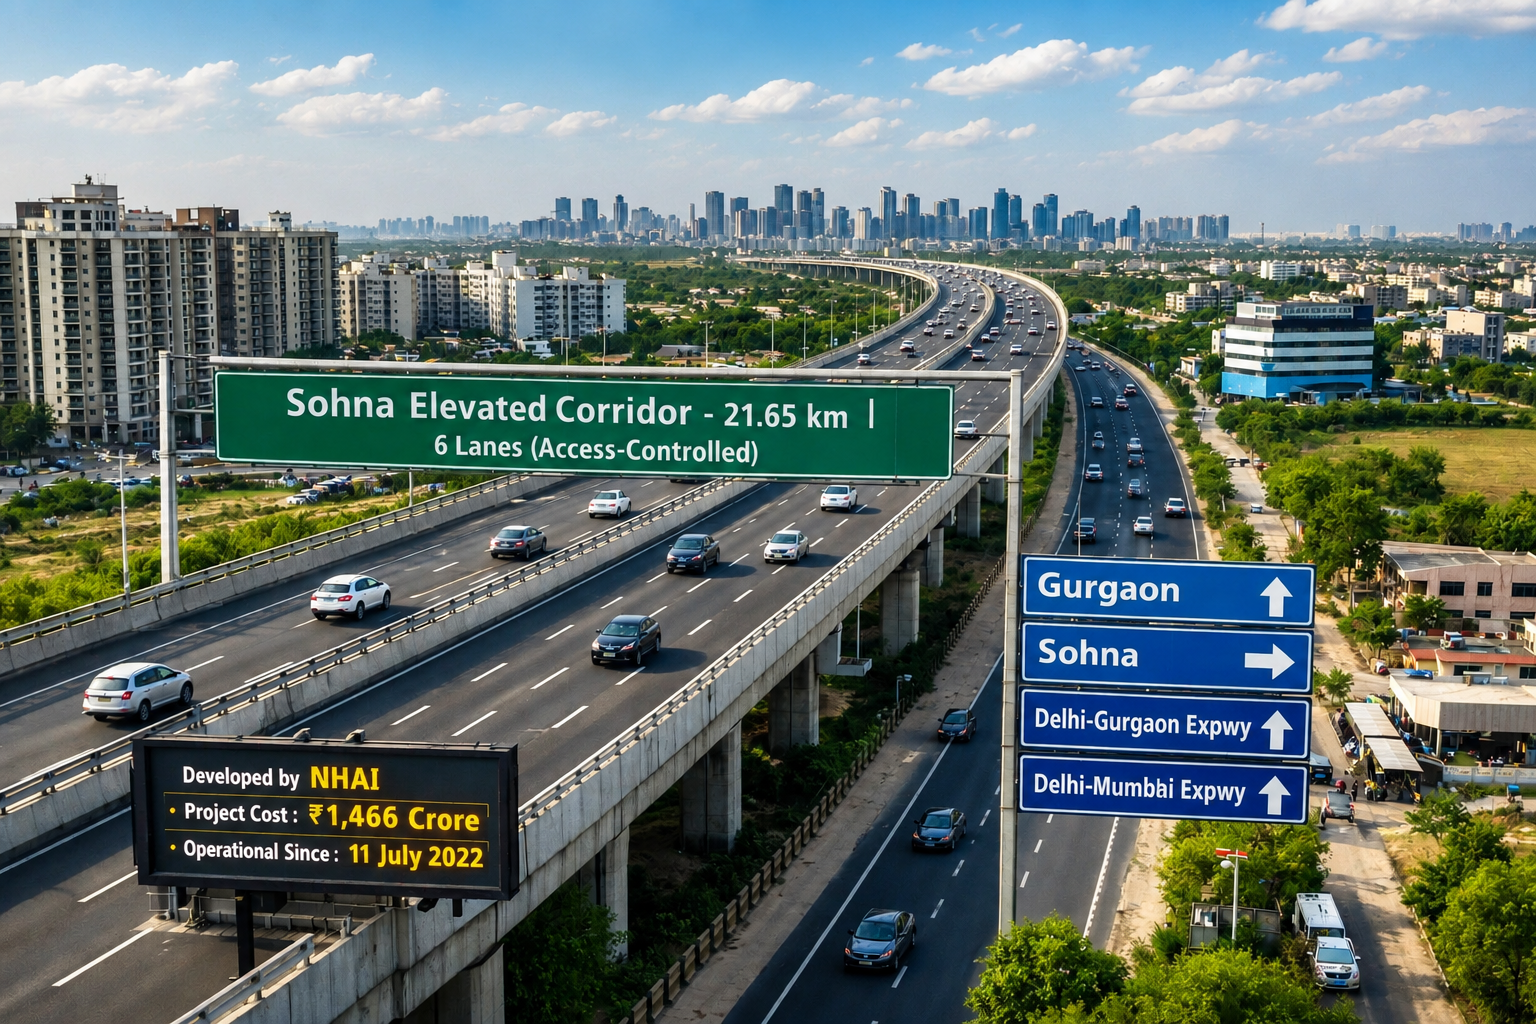
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
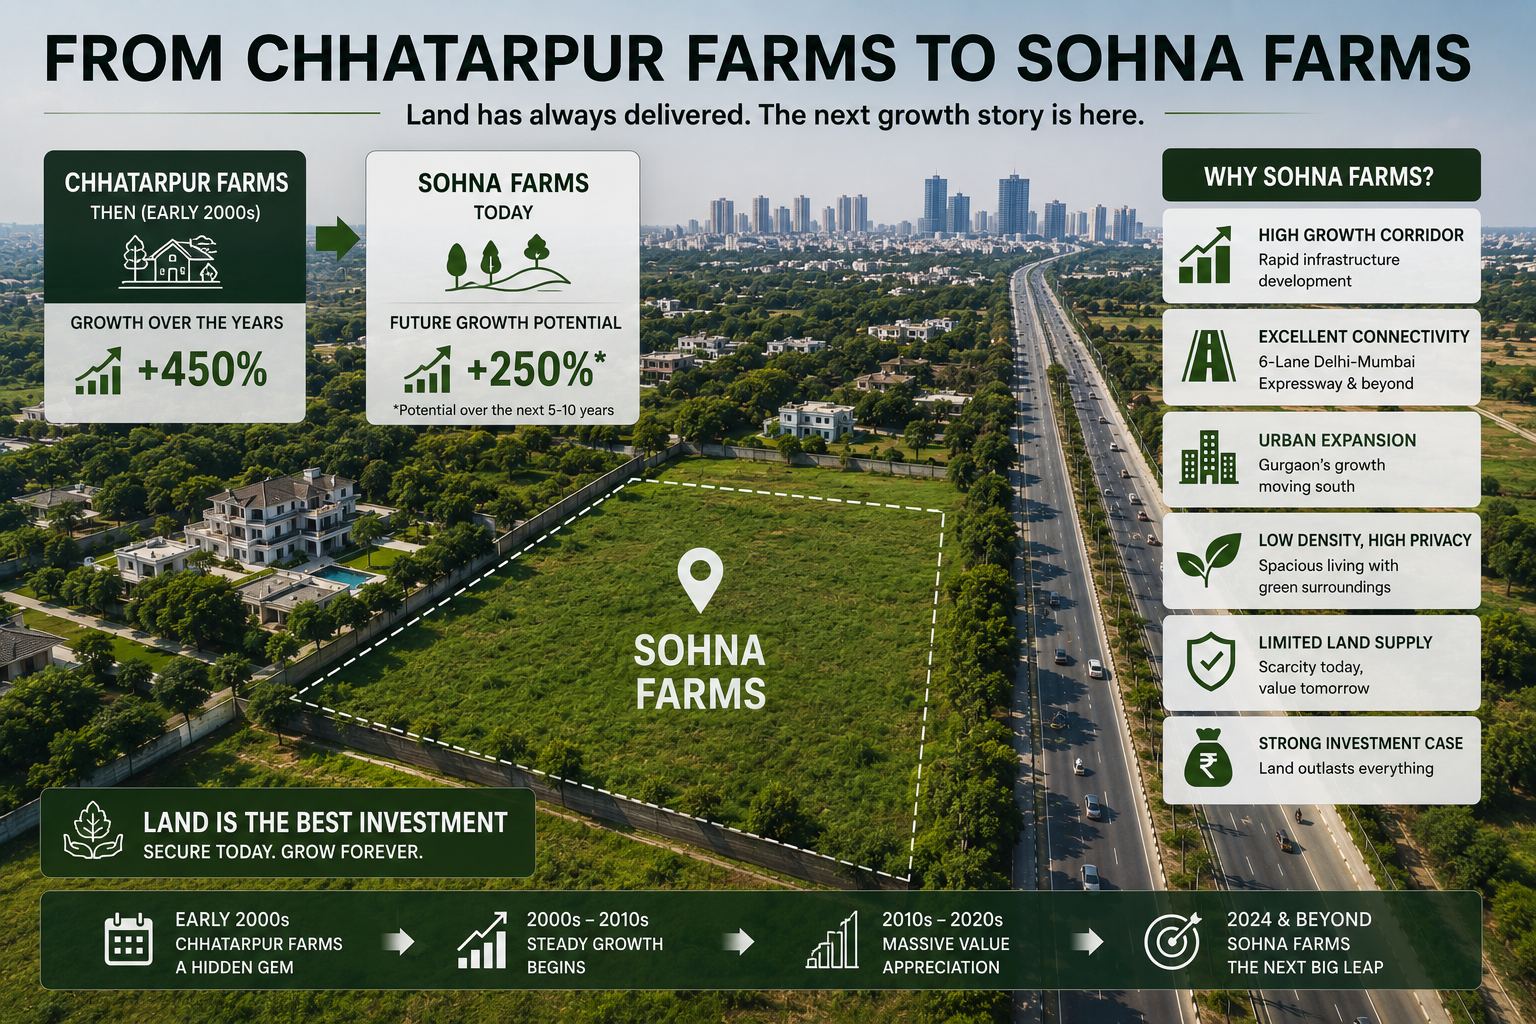
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
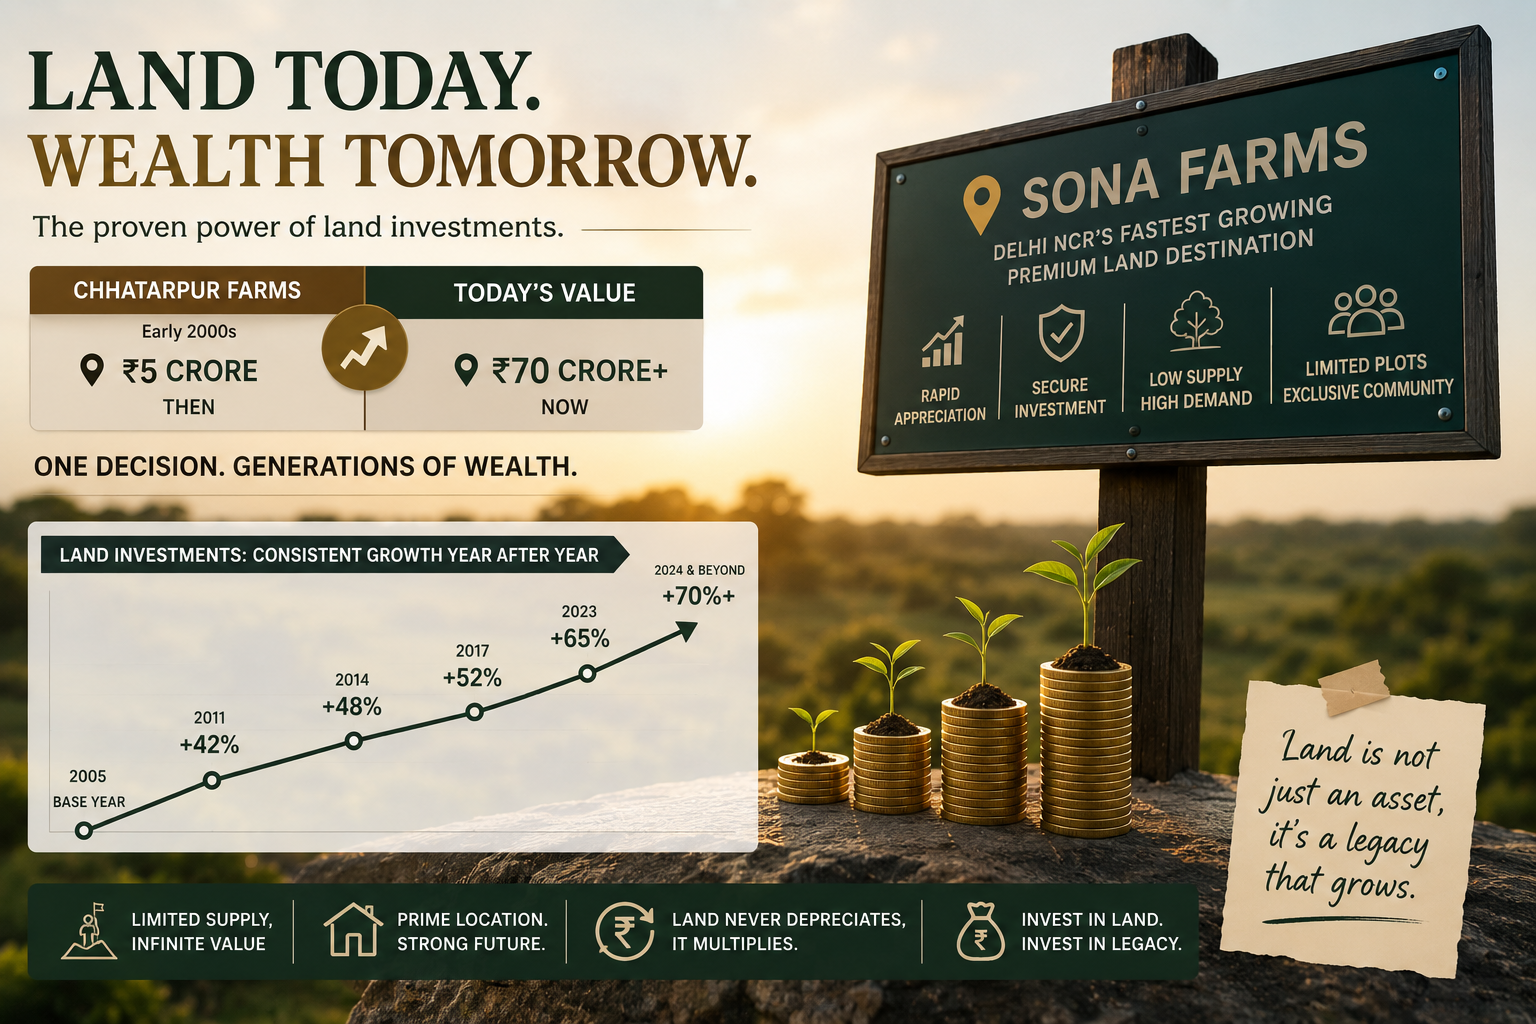
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.