British Retail's Venture Conundrum: Funding Dries as Fundamentals Shift
Despite a vibrant startup ecosystem, UK retail tech ventures face a tightening investment landscape, forcing a re-evaluation of growth strategies and an increased emphasis on profitability amid economic headwinds.

The brightly lit aisles of a Tesco Extra, once the undisputed battleground for retail innovation in the UK, now represent a different challenge for emerging technology firms. While established players like Sainsbury's and Marks & Spencer continue to refine their digital strategies, the pipeline of venture capital funding that once fuelled a multitude of retail-focused startups has notably constricted. This shift portends a more demanding environment for businesses seeking to disrupt or enhance the consumer experience, moving beyond initial promise to tangible, scalable returns.
For several years, British retail technology benefited from a relatively accessible pool of capital, often driven by the success stories of firms like Ocado, which demonstrated the potential for automated logistics, or the rapid rise of delivery platforms such as Deliveroo and Just Eat. Investors were keen to back solutions addressing everything from inventory management to personalised customer engagement, viewing retail's digital transformation as an almost limitless opportunity. This period fostered a perception that rapid expansion, even without immediate profit, was a viable pathway.
Investment Winter Nips at Innovation
Recent data indicates a marked deceleration in venture funding for UK retail tech. While specific figures fluctuate, the overall trend points to a reduction in both the volume and average size of seed and Series A rounds compared to the peak years of 2020 and 2021. This reflects a broader global investor sentiment, where rising interest rates and macroeconomic uncertainty have shifted focus from aggressive growth metrics to sustainable business models and clear paths to profitability. Startups are now encountering more stringent due diligence and a longer fundraising cycle.
The implications extend beyond just access to cash. Many smaller retail tech firms, particularly those developing niche solutions for specific aspects of the supply chain or customer journey, are finding it harder to secure follow-on funding. This necessitates a more conservative approach to headcount expansion and product development, contrasting sharply with the 'growth at all costs' mentality that previously dominated.
The current funding climate demands a return to fundamental business principles: clear unit economics, robust revenue generation, and a demonstrable path to self-sufficiency. Venture capital is not patient capital for its own sake.
Established UK retailers, while still innovating, are also re-calibrating their approach to external partnerships. Companies like Next, known for its strong online infrastructure, or ASOS, which operates purely digitally, might previously have acquired promising startups. Now, they are more likely to seek partnerships that offer immediate, proven operational efficiencies or a direct impact on the bottom line, rather than speculative future growth.
Consumer behaviour in the UK provides a complex backdrop. While online shopping penetration remains high, the cost of living crisis has made value and convenience paramount. Shoppers are discerning, and loyalty is often dictated by price and a seamless experience. This pressure forces retail tech startups to not just offer innovation, but to demonstrate how that innovation translates directly into savings or enhanced value for the end consumer or the retailer.
The current environment therefore necessitates a strategic pivot for many British retail tech ventures. Survival and growth will increasingly depend on lean operations, a meticulous focus on achieving positive cash flow, and a compelling value proposition that resonates with cautious investors and pragmatic retailers alike. The era of abundant, speculative capital appears to have concluded, ushering in a period where only the most resilient and financially astute startups are likely to thrive.
This shift marks a maturation of the UK retail technology sector. While the pace of investment may have slowed, the demand for genuine innovation that addresses persistent challenges in areas such as sustainability, logistics optimisation, and personalised customer experience remains strong. The future of British retail tech may involve fewer, but more robust, ventures capable of delivering tangible commercial impact.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
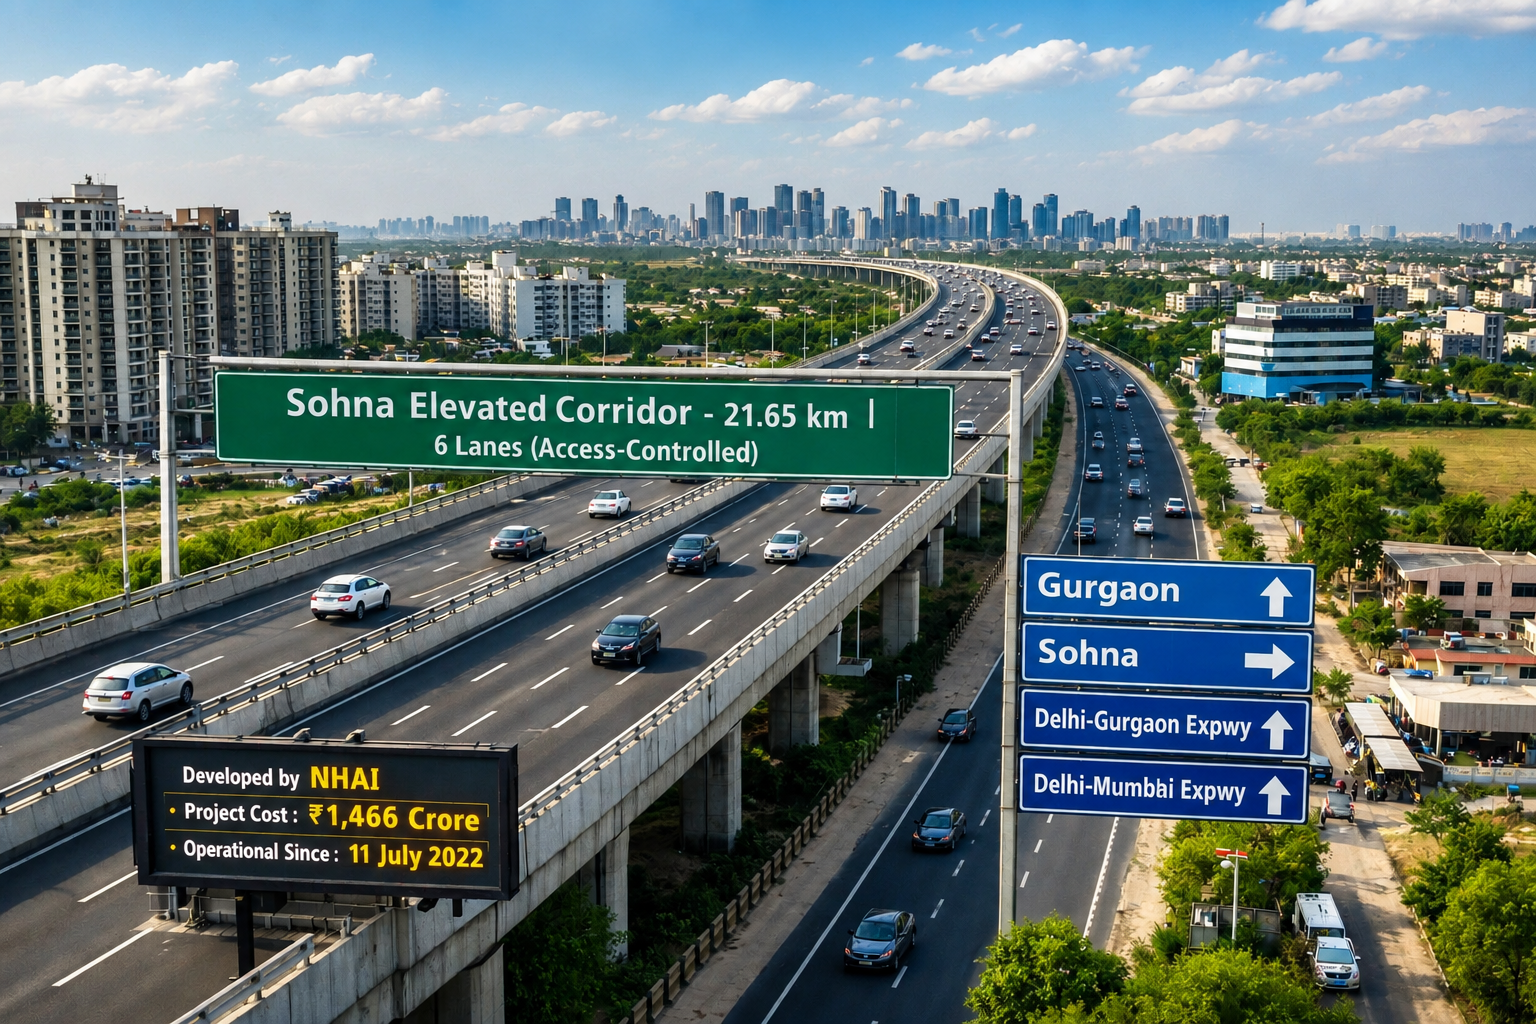
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
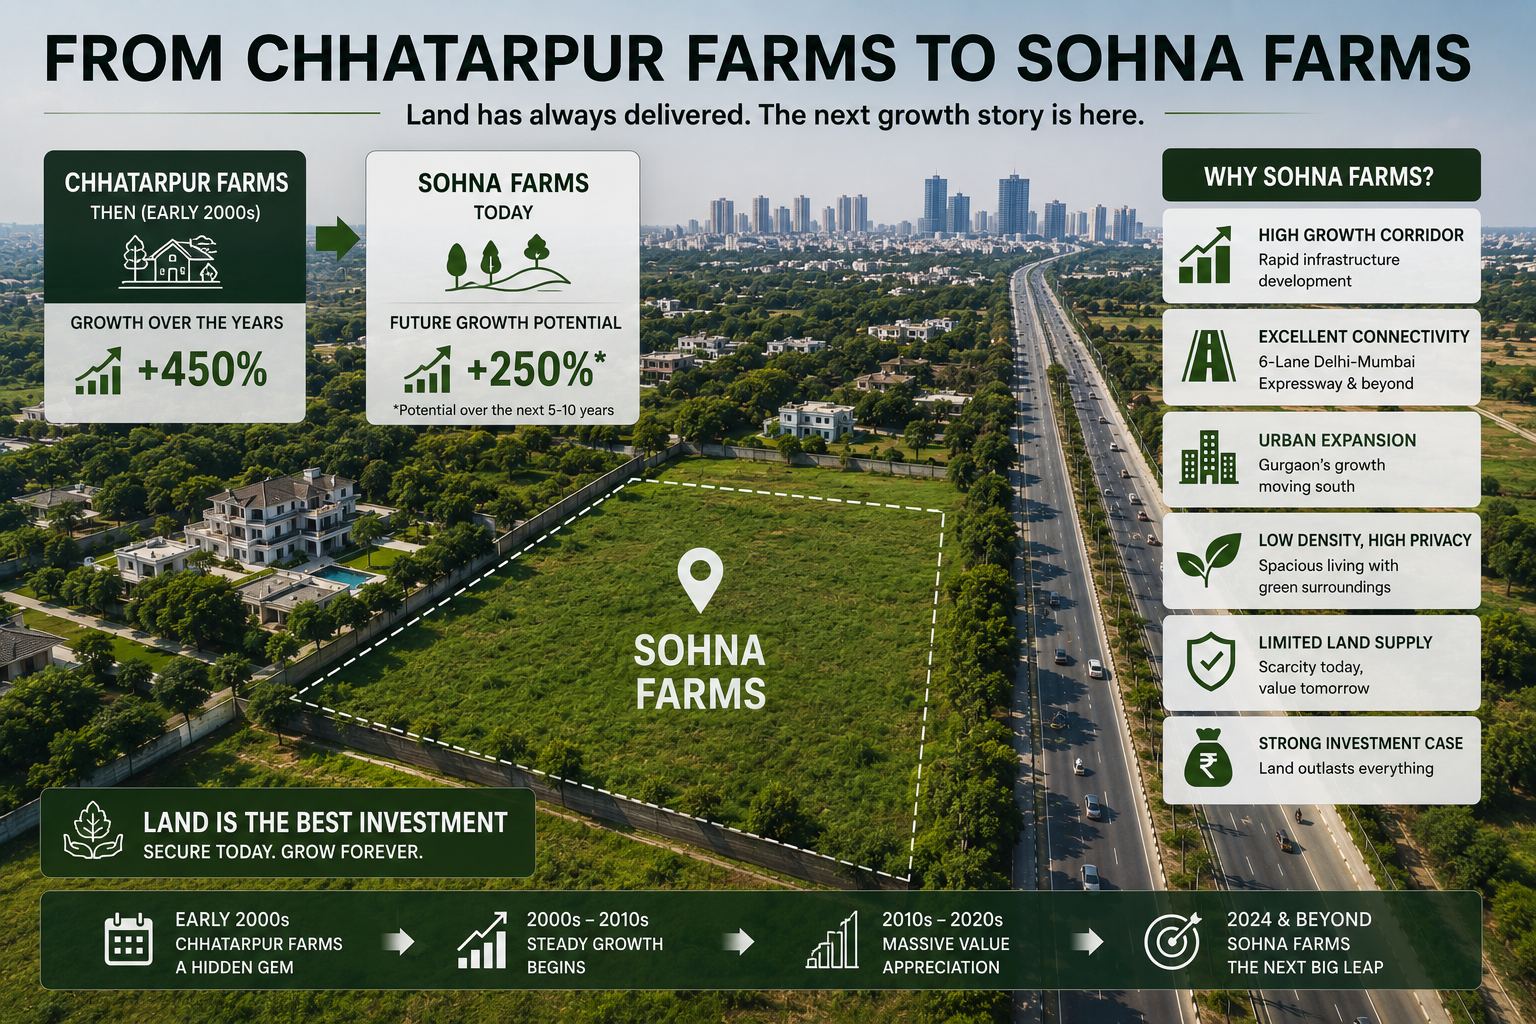
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
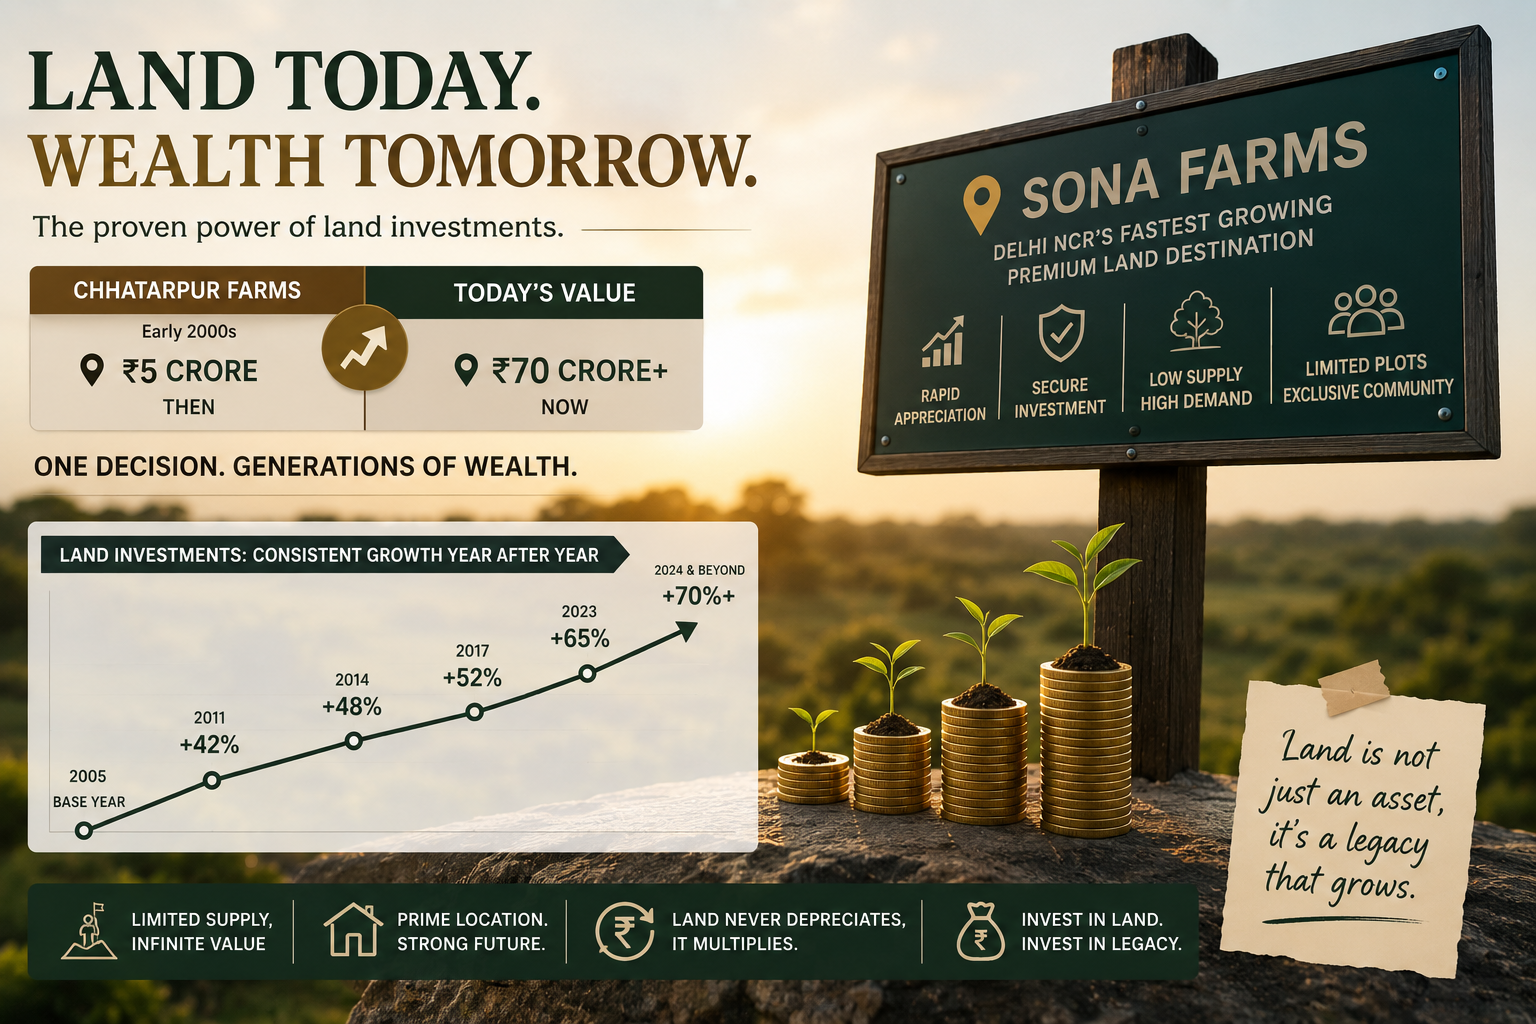
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.