Europe's Digital Market Fragmentation: The Long Tail of Localism
Despite a unified economic bloc, Europe's e-commerce landscape remains stubbornly fractured, presenting unique challenges and opportunities for retailers navigating diverse consumer behaviours and logistical complexities.

While Amazon continues its broad expansion, a closer examination of Europe's digital commerce reveals a persistent patchwork of national champions and regional preferences. Consider the divergent paths of online fashion. Zalando dominates in Germany and parts of the Nordics, processing billions in gross merchandise value annually. Yet, in France, Vinted, initially focused on second-hand fashion, commands significant mindshare and transaction volume, reflecting a distinct consumer inclination towards circularity and value. This geographic segmentation, far from being an anomaly, defines much of the continent's digital retail reality.
This enduring fragmentation matters because it fundamentally alters how businesses scale across the European Union. Unlike the relatively homogenous consumer markets of the United States or China, Europe presents a mosaic of languages, payment preferences, logistics networks, and regulatory nuances. A strategy that achieves success in Warsaw with Allegro's robust marketplace presence might find limited traction in Rome, where ePrice (before its struggles) or specific brand-direct channels held sway. This necessitates highly localised approaches, often sacrificing pan-European efficiency for national resonance.
The Endurance of National Champions
The survival and indeed prosperity of national digital behemoths illustrate this point with clarity. In Poland, Allegro, founded in 1999, remains the undisputed e-commerce leader, handling well over half of all online retail transactions within the country. Across the border in the Netherlands and Belgium, Bol.com, originally a Dutch enterprise, maintains a powerful market position against global competitors. France sees Cdiscount, part of the Casino Group, holding its own against international players, particularly in electronics and home goods. These entrenched positions are often bolstered by decades of brand trust, tailored delivery options, and deep understanding of local consumer psychology, making market entry challenging for outsiders.
Logistics further complicates cross-border aspirations. While the European single market theoretically permits free movement of goods, the practicalities of last-mile delivery vary significantly. A German consumer expects highly efficient parcel delivery services often leveraging dense networks from players like DHL or Hermes. An Italian counterpart might value a different array of collection points or specific delivery windows. Companies like the now-defunct Gorillas or Flink, while aiming for hyper-local rapid delivery, still had to adapt their operational models distinctly for Berlin versus Paris, highlighting the granular differences even within urban logistics.
Shifting Consumer Appetites and Cross-Border Flows
However, this localism is not static. Consumer behaviours, while rooted in national culture, are slowly converging on certain fronts. The pandemic accelerated digital adoption across all age groups and income brackets, pushing traditional retailers like Carrefour and REWE to significantly enhance their online grocery offerings. This move has created new competitive fronts, not just against pure-play e-grocers, but also against discounters like Lidl, which has selectively entered online delivery in various markets, leveraging its vast store network.
"The notion of a single 'European consumer' remains a theoretical construct. Real success hinges on understanding the nuances of 27 distinct market psychologies, even as digital habits grow more uniform."
Moreover, certain product categories inherently lend themselves to more fluid cross-border trade. Premium fashion, luxury goods, and niche electronics often see consumers willing to purchase directly from websites in other EU countries, driven by selection or price. This creates opportunities for retailers to target specific demographics across borders without needing a full-scale physical presence in every market. Yet, for fast-moving consumer goods or everyday essentials, the cost and logistical complexity often favour hyper-local sourcing and fulfilment.
The strategic imperative for any retailer or brand aspiring to significant European presence, therefore, is not to force uniformity, but to master adaptive localism. This involves robust data analytics to discern national consumer preferences, flexible logistics partnerships, and a keen awareness of regulatory differences from data privacy to consumer protection. Those who successfully navigate this complex terrain stand to capture substantial portions of Europe's multi-trillion-euro retail market, even if it never coalesces into a single, seamless digital landscape.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
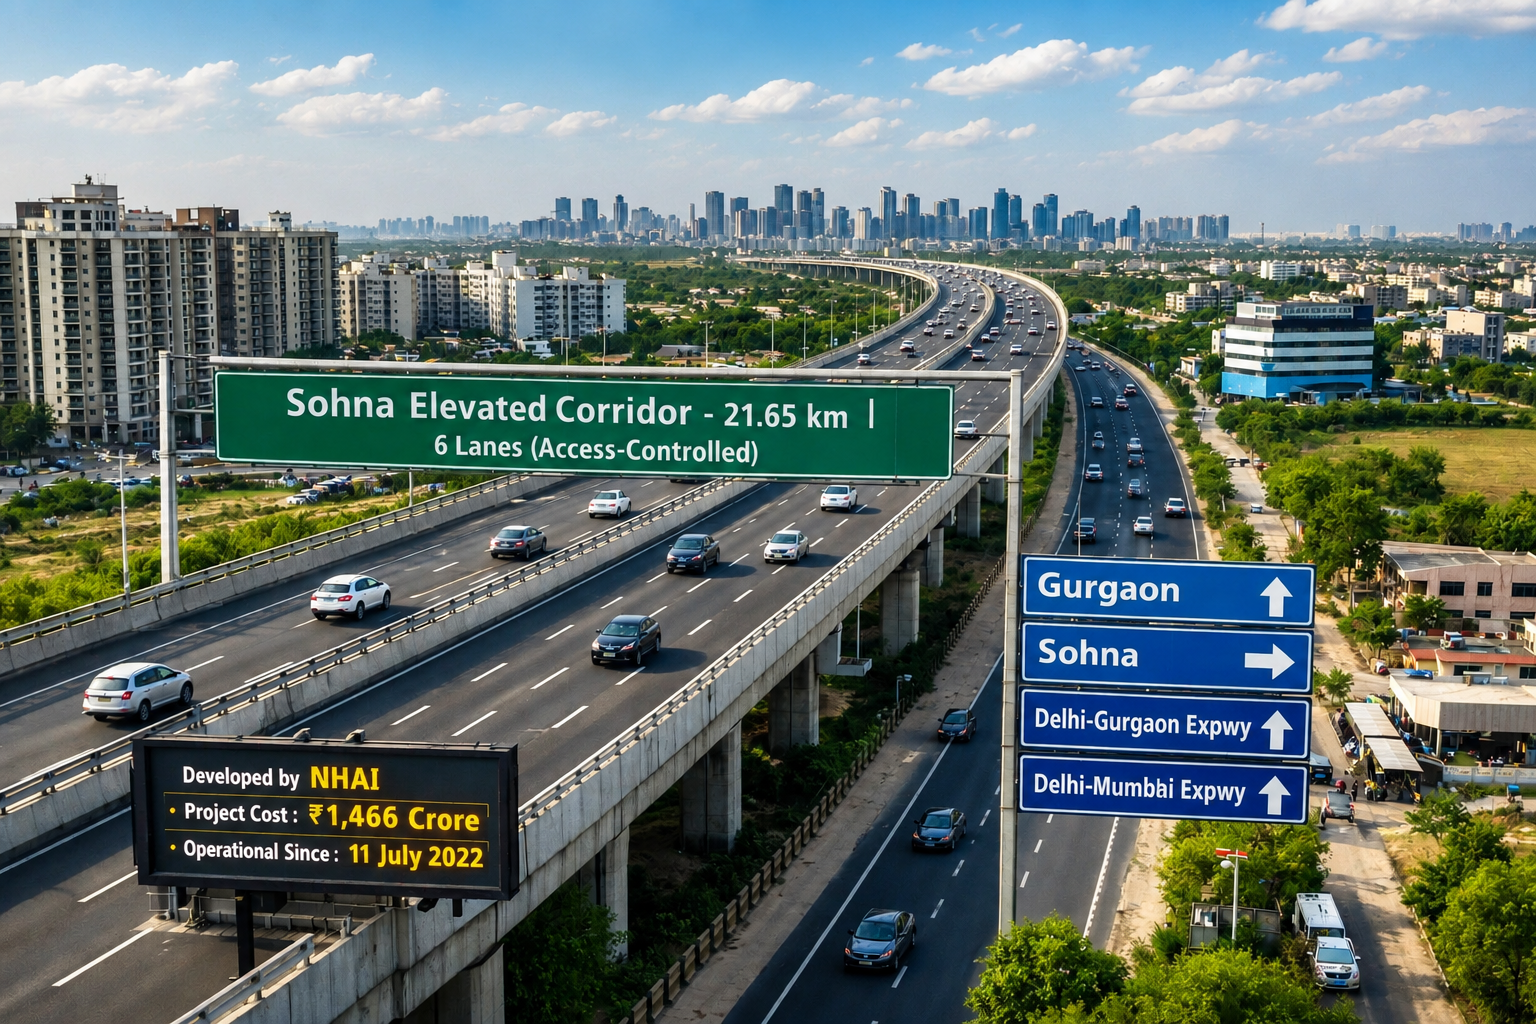
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
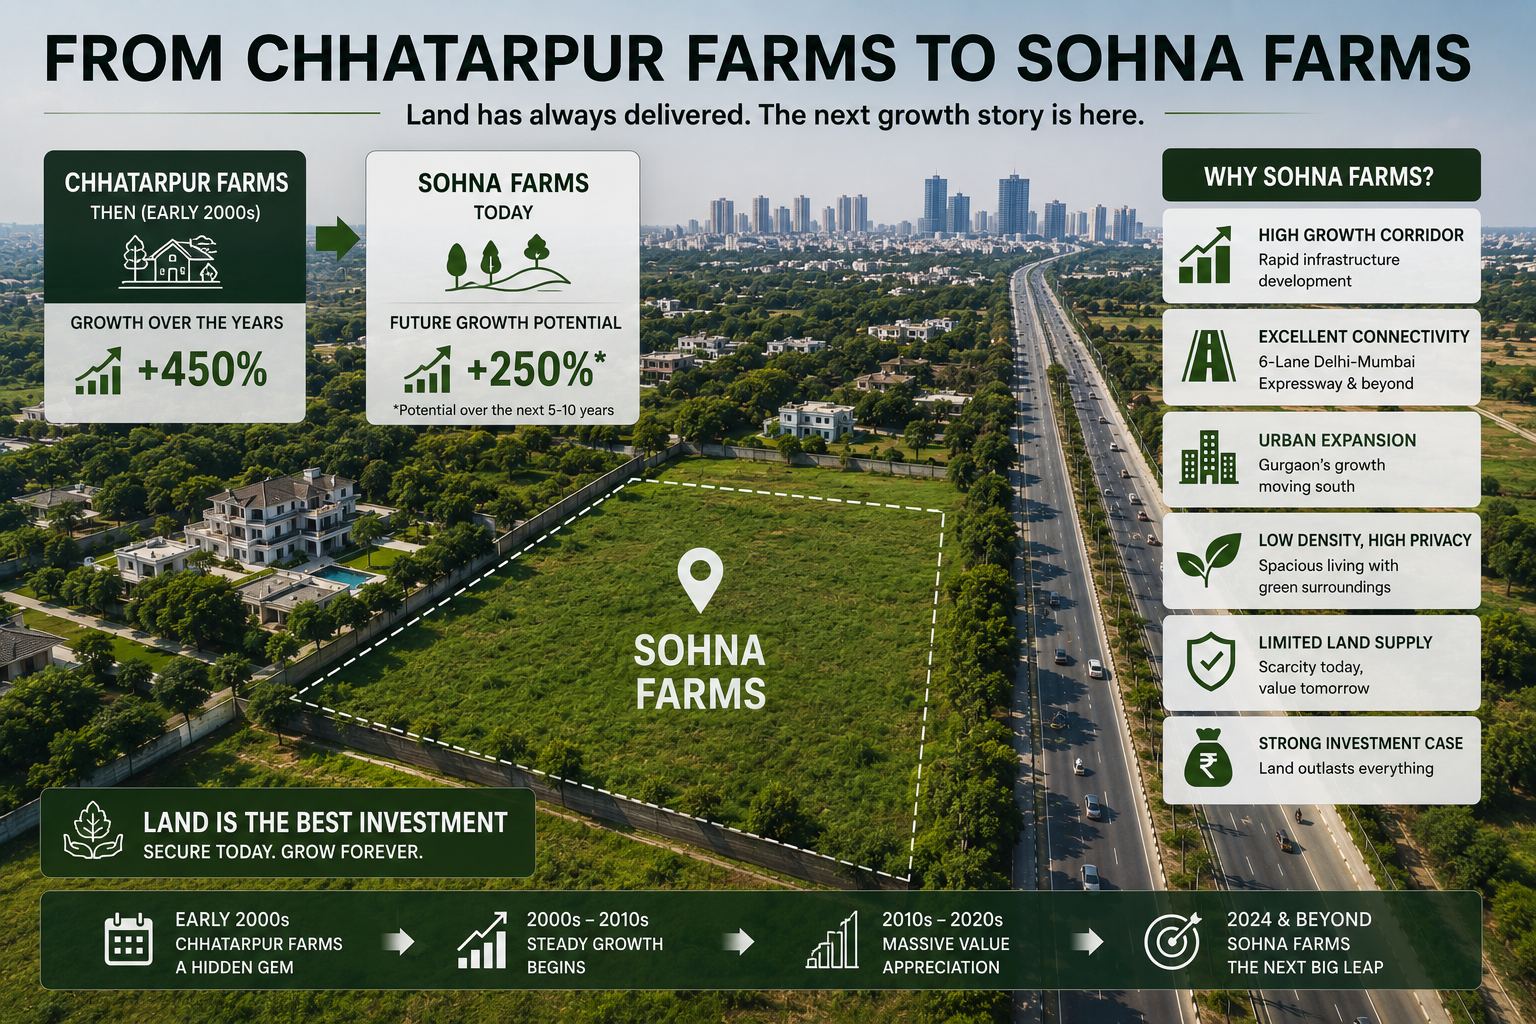
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
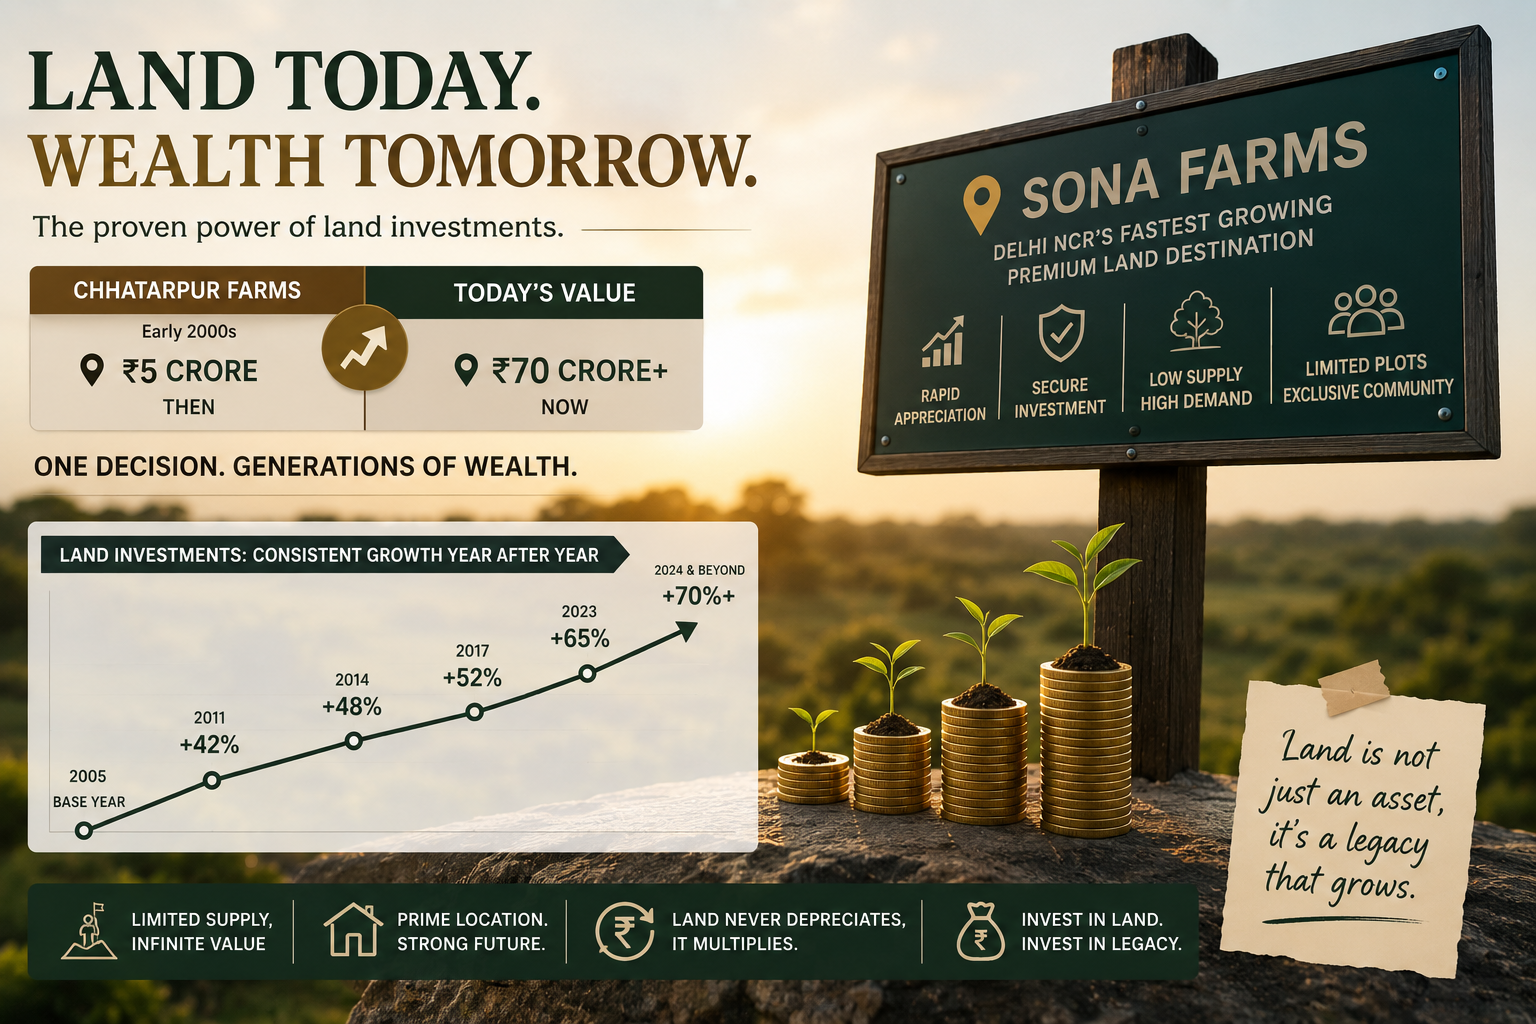
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.