Europe's Digital Marketplace: Fragmented Futures and Consolidation Pressures
The quest for scale and seamless cross-border operations defines the current era for European retail technology, where local champions battle global platforms amidst diverse national consumer habits and regulatory landscapes.

From its Berlin headquarters, Zalando, once a disruptor in fashion e-commerce, now navigates a continental market increasingly defined by fierce competition and the need for operational dexterity. The company's recent strategic shifts, focusing on partner programmes and logistics optimisation, underscore a broader trend across Europe: retailers and tech providers are confronting the unique complexities of a multi-national, multi-lingual digital economy, often without the single-market advantages enjoyed by their US or Chinese counterparts.
The European retail tech landscape is not a monolith. While platforms like Amazon exert considerable influence, a vibrant ecosystem of regional players persists, reflecting deeply ingrained national preferences and regulatory divergences. Consider the grocery sector, where Germany's REWE and Lidl maintain formidable brick-and-mortar and burgeoning online presences, contrasting with the more aggressive e-commerce push seen from Carrefour in France or Spain, and distinct models emerging in the Nordics. These variations inhibit the kind of rapid, uniform scalability observed in other large economic blocs.
Cross-Border Commerce: A Persistent Hurdle
Despite the ambition of a unified digital market, actual cross-border e-commerce within the EU remains more challenging than often depicted. Language barriers are a primary factor, but so too are differing consumer protection laws, payment preferences, and logistics infrastructure. A consumer in Poland engaging with Allegro, for instance, experiences a different interface and service standard than one in France using Cdiscount, or a Dutch shopper on Bol.com. These national champions, deeply entrenched in local psyches, often understand and cater to domestic nuances better than any pan-European entrant.
Venture capital, once flowing freely into rapid delivery experiments like Gorillas and Flink, has become more discerning. The consolidation seen in this sector, exemplified by strategic acquisitions and retrenchments, highlights the unsustainability of growth-at-all-costs models when profitability remains elusive across fragmented urban markets. Investors now prioritise unit economics and a clear path to profitability, rather than merely market share expansion.
Beyond direct-to-consumer platforms, the underlying technology infrastructure also grapples with this fragmentation. Solutions providers, from warehouse automation specialists to payment processors, must often adapt their offerings significantly for each major market. This bespoke approach drives up costs and slows the pace of innovation deployment, particularly for smaller retailers attempting digital transformations. Standardisation, while desired, is often impractical given local customs and legacy systems.
The Pressure to Consolidate and Specialise
The sustained pressure to achieve economies of scale is undeniable. This environment will likely foster further consolidation, as smaller or less differentiated players struggle to compete against the operational efficiencies of larger entities or the deep specialisation of niche providers. Acquisitions, strategic partnerships, and even cross-border mergers are anticipated to become more frequent as companies seek to expand their geographic reach or technological capabilities without reinventing the wheel in every new territory.
The enduring strength of local retail identities, coupled with the regulatory patchwork, means that true pan-European retail dominance is an aspiration, not an inevitability, for any single entity.
The resale market, exemplified by Vinted, demonstrates a successful model for navigating these complexities. By focusing on a specific consumer behaviour – second-hand fashion – and building a robust community across multiple European nations, Vinted has managed to create significant scale despite the underlying market fragmentation. Their success hinges on understanding the common threads of consumer desire across borders, rather than attempting to homogenise disparate national retail experiences. The path forward for many European retail tech entities will likely involve either significant scale through consolidation, or highly effective specialisation within profitable niches.
As the digital maturity of European consumers continues to advance, the distinction between 'online' and 'offline' retail blurs. The companies that will thrive are those capable of seamlessly integrating digital convenience with localised service, while adeptly managing the intricate logistical and regulatory tapestry that defines the European economic area. This necessitates not just technological prowess, but also a profound understanding of diverse cultural contexts.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
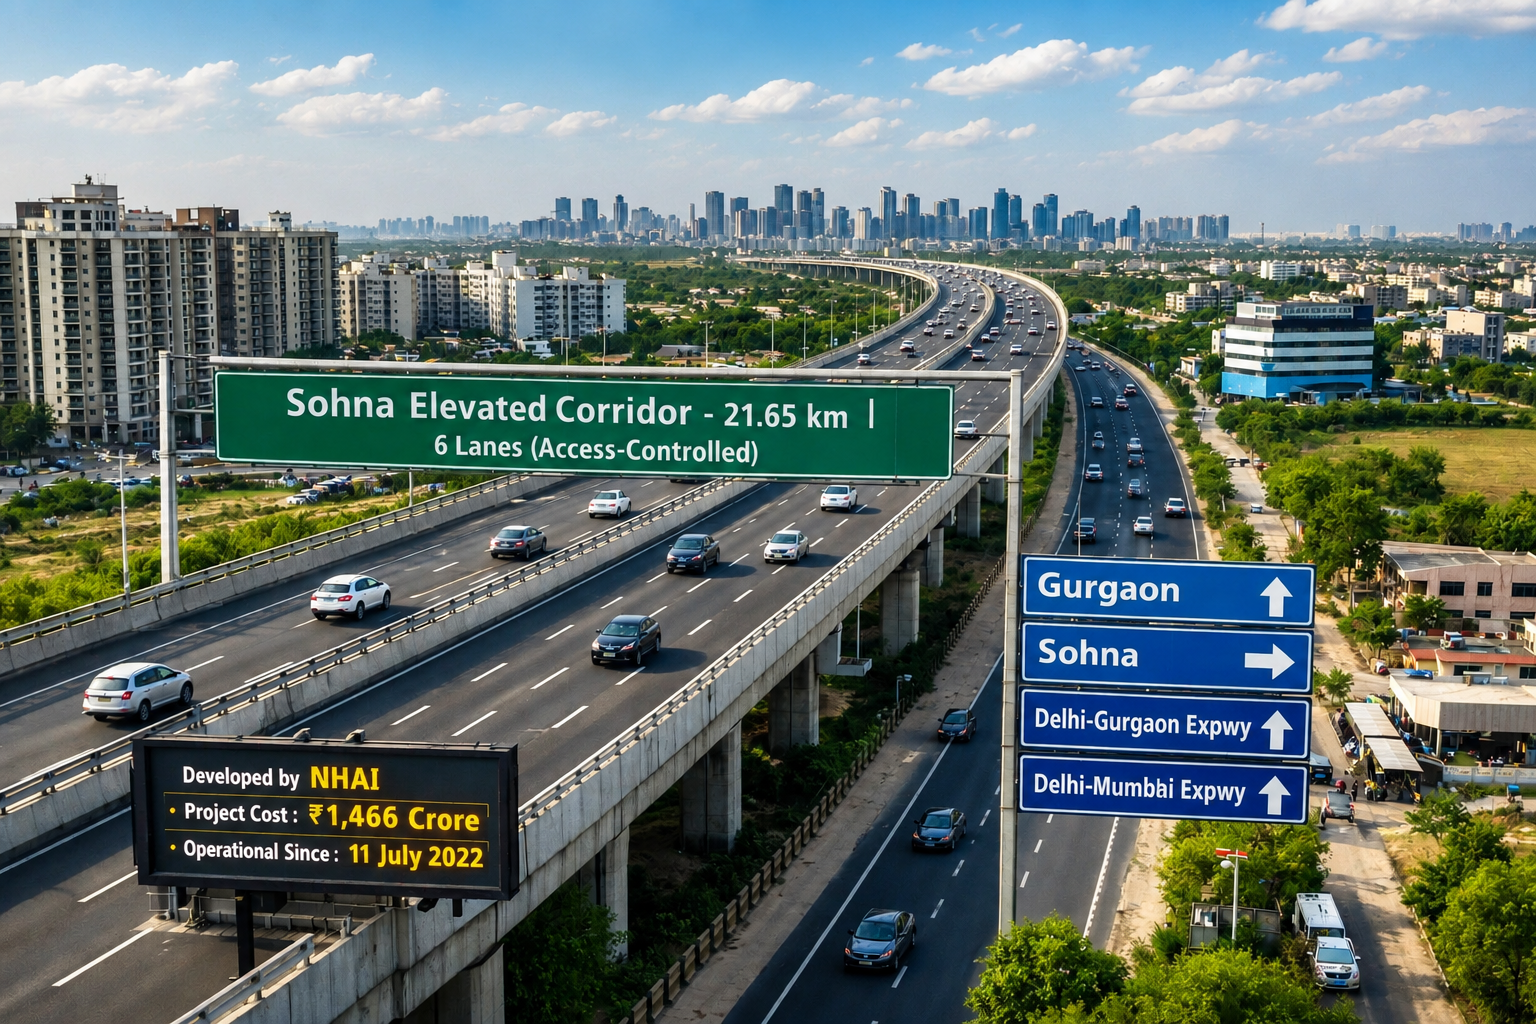
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
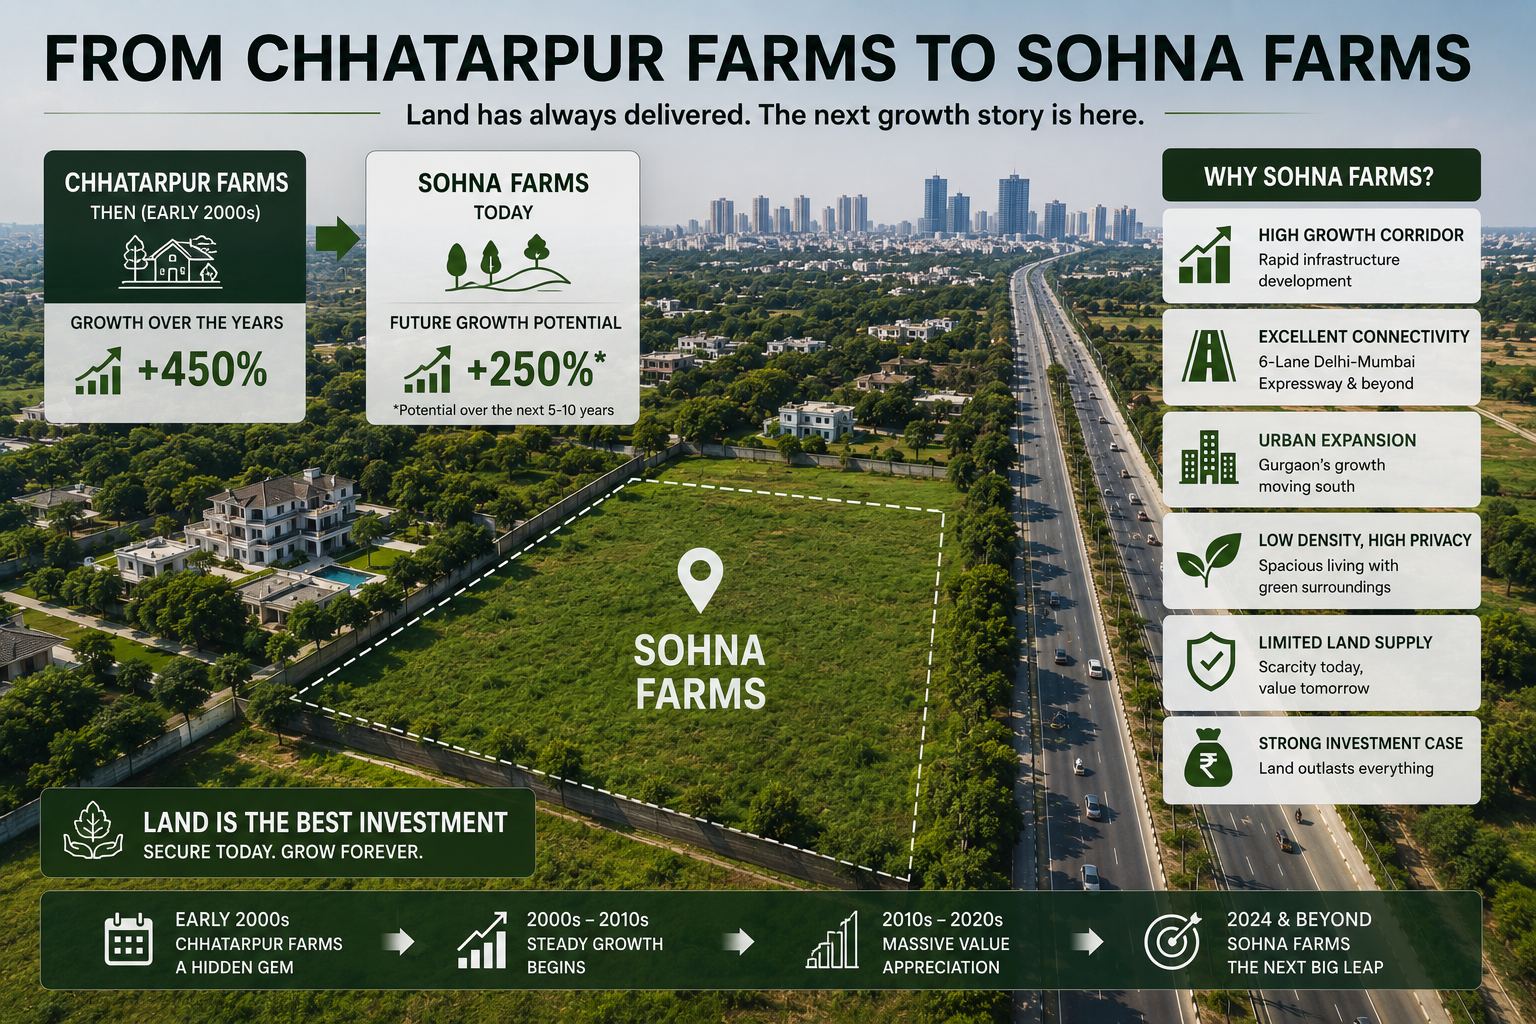
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
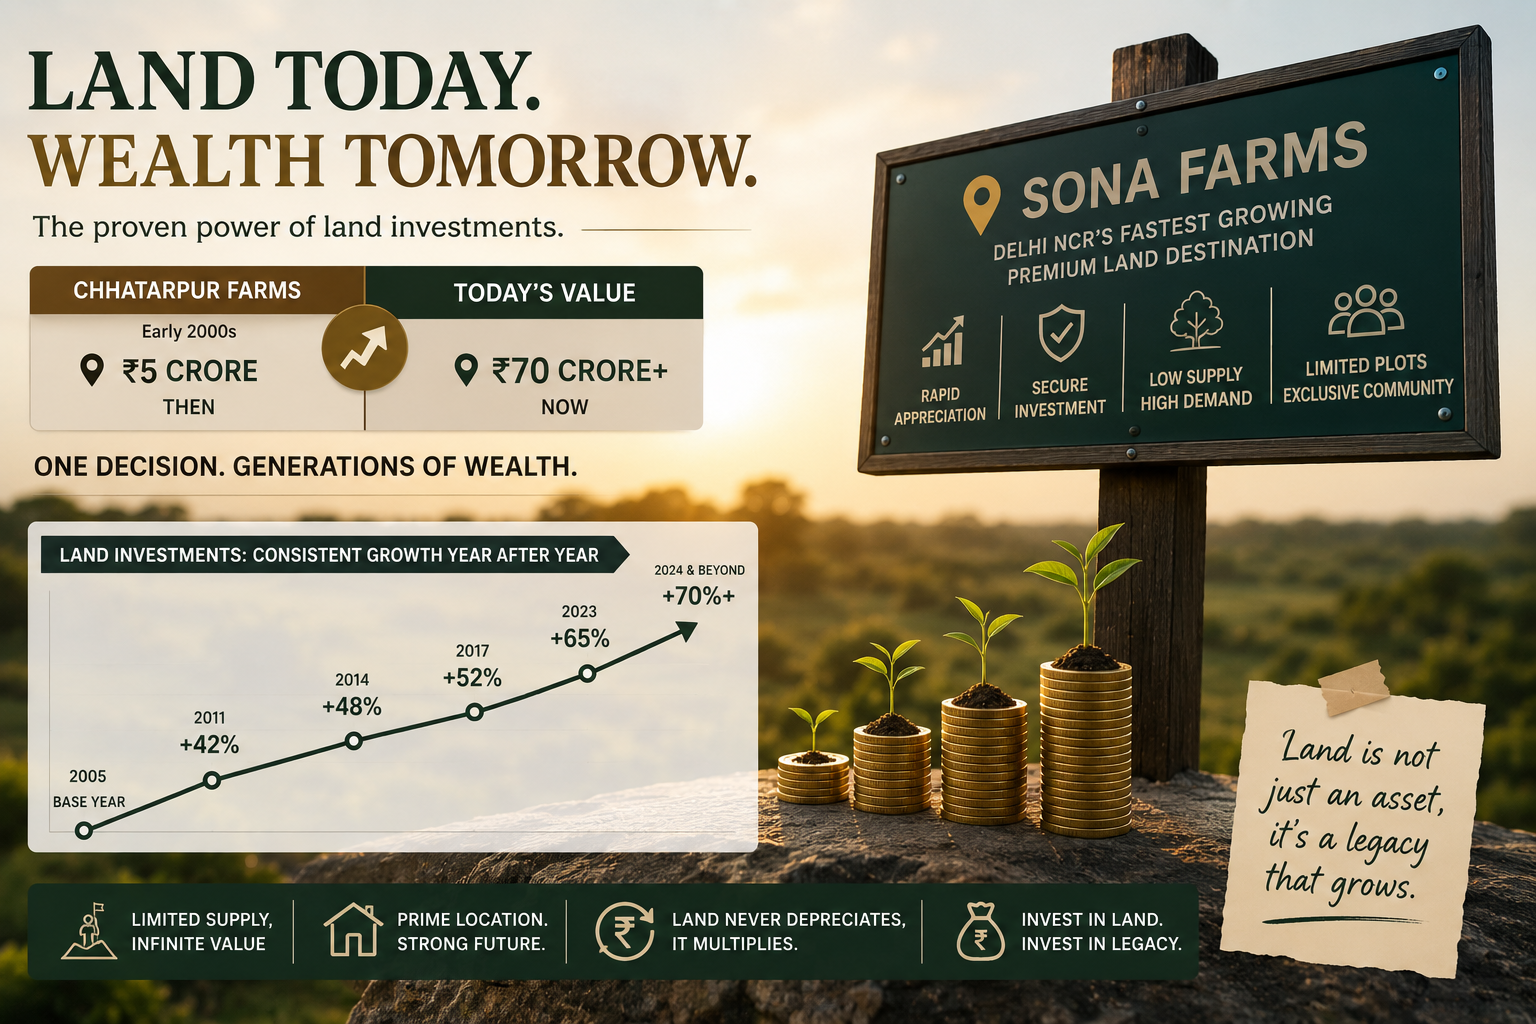
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.