Europe's E-Commerce Fragmentation Persists Amidst Scale-Up Ambitions
Despite efforts towards continental integration, Europe's digital retail landscape remains a patchwork of national champions and distinct consumer preferences, challenging unified expansion strategies.

A recent glance at Bol.com, the dominant online retailer in the Netherlands and Belgium, reveals an inventory tailored specifically for those markets, distinct from the offerings found on Cdiscount in France or Allegro in Poland. This segmentation underscores a fundamental reality of European e-commerce: while the concept of a single market prevails in policy, the retail execution across borders continues to contend with deeply entrenched national identities, diverse logistics networks, and varying regulatory frameworks.
The continent's digital retail sector, valued at approximately €850 billion in 2023, represents a significant economic force. However, unlike the more consolidated e-commerce markets seen in North America or parts of Asia, Europe's market share is distributed among a multitude of players, from pan-European giants like Zalando to domestic powerhouses and a growing cohort of specialised platforms.
Cross-Border Complexities
Expanding across European borders is often more akin to entering a new country than merely extending a digital footprint. Language barriers are merely the most obvious hurdle; payment preferences vary widely, with credit cards dominating in some regions while local debit schemes or alternative methods like Klarna hold sway elsewhere. Fulfilment and last-mile delivery also present a mosaic of challenges, from dense urban centres to more sparsely populated rural areas, each with its own logistical intricacies.
Consider the grocery sector, where the rapid delivery model, once hailed as a revolutionary force, has seen significant rationalisation. While companies like Gorillas and Flink initially scaled aggressively, their paths have diverged, highlighting the difficulty of achieving profitability across heterogeneous markets. Traditional grocers such as Carrefour, REWE, and Lidl are making their own digital inroads, leveraging established physical networks to fulfil online orders, often with a more sustainable cost structure.
The allure of a unified European digital market often masks the granular reality of consumer expectations and operational demands that differ substantially from Lisbon to Helsinki, or from Warsaw to Rome.
The strategic choices made by companies like Vinted, the Lithuanian-founded marketplace for second-hand fashion, demonstrate a more nuanced approach. Instead of attempting a 'big bang' launch across all EU-27 nations simultaneously, Vinted has expanded selectively, building localised communities and logistics capabilities market by market, illustrating the incremental gains possible through tailored execution.
The Pursuit of Scale
Even as these domestic and regional differences persist, the drive for scale remains a powerful imperative. European players recognise the necessity of growing beyond their home turf to compete effectively against global entities. This ambition often manifests through mergers, acquisitions, or strategic partnerships designed to pool resources and expertise, rather than solely organic expansion. The competition is not just for market share, but also for logistical efficiency and technological advancement.
For instance, while Zalando holds a strong position in fashion e-commerce across many European countries, its growth trajectory increasingly involves refining its platform services for partners and investing in its logistics backbone to ensure rapid, reliable delivery across diverse geographies. This investment in infrastructure and ecosystem development aims to mitigate some of the inherent fragmentation.
The long-term trajectory for European e-commerce is likely to involve a continued tension between consolidation and customisation. While certain platforms may achieve greater continental reach, the underlying demand for localised product assortments, specific payment options, and culturally resonant marketing will ensure that the market retains its distinct, multi-faceted character for the foreseeable future. The harmonisation sought by policymakers continues to meet the resistance of deeply embedded commercial realities.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
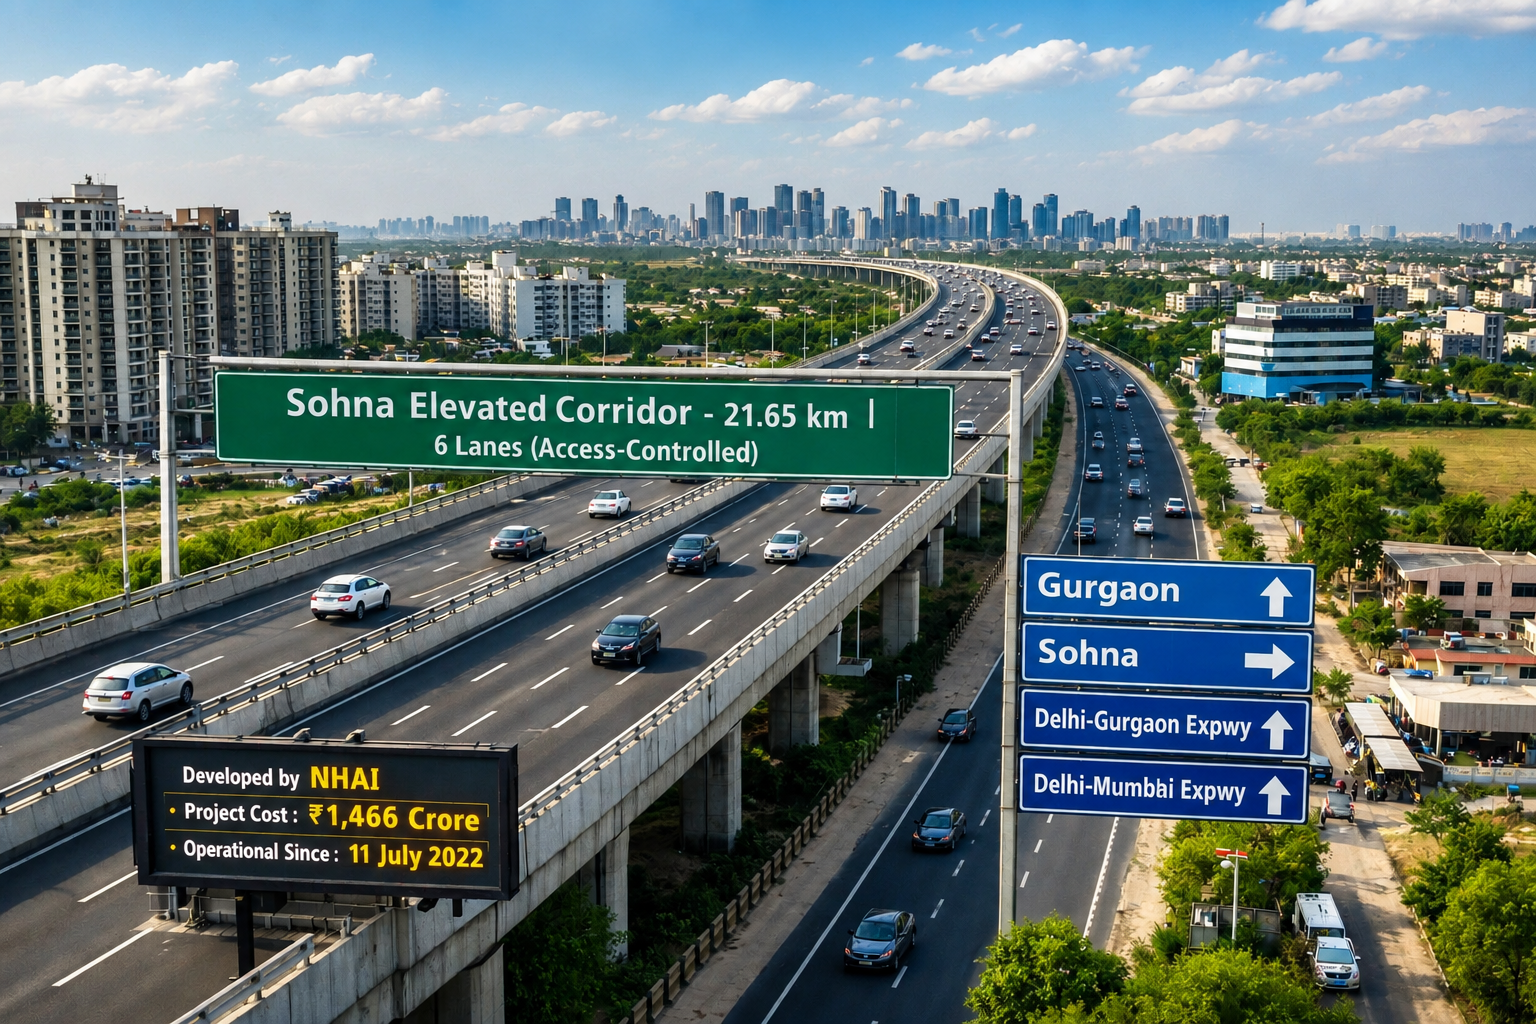
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
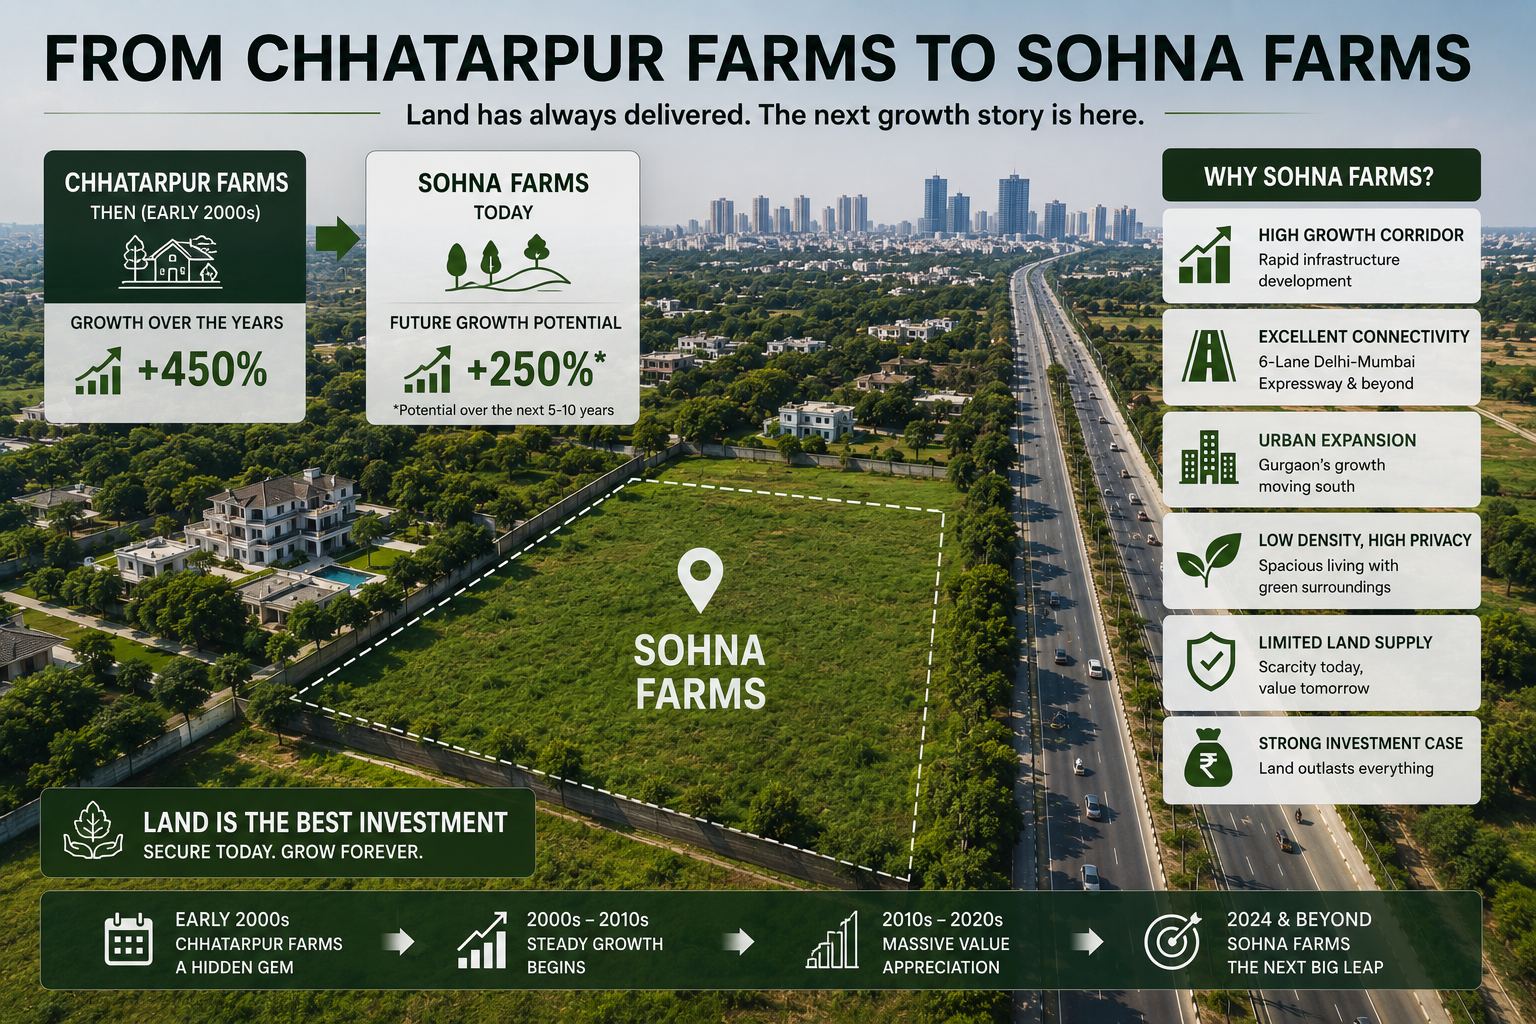
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
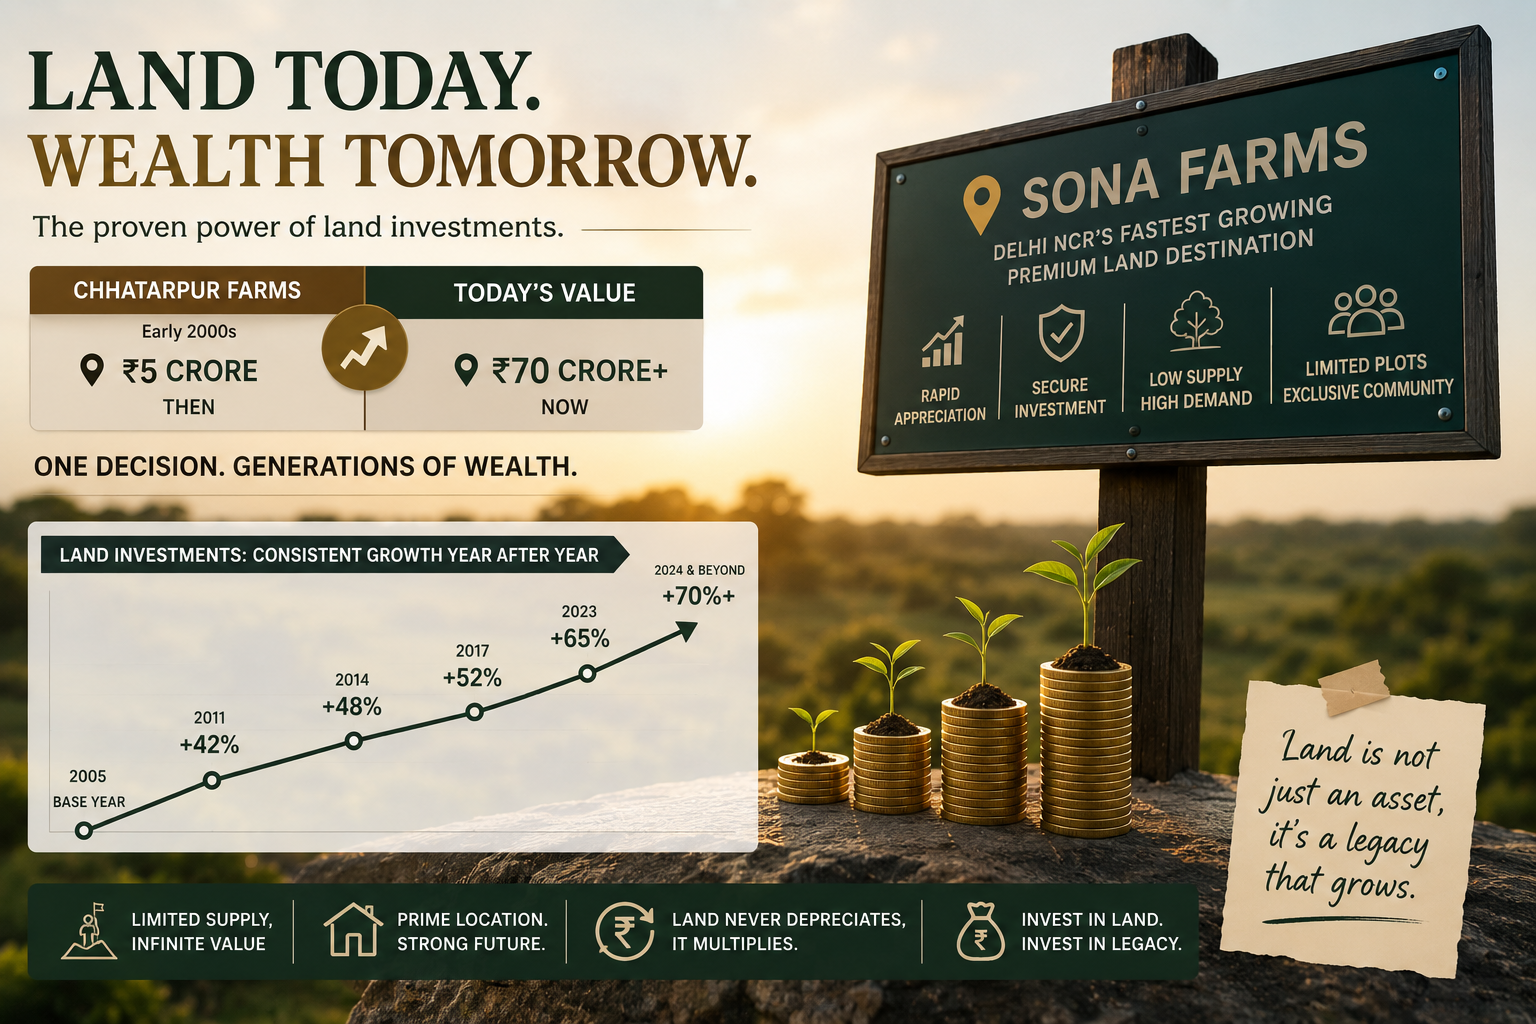
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.