Europe's Retail Consolidation: The Last Mile and the Long Play
European e-commerce, once a fragmented landscape for venture-backed disruptors, now confronts a stark reality of capital scarcity and market maturity, forcing a strategic reckoning among even well-funded players.

The distinctive green and purple branding of Flink, once ubiquitous across central Berlin, has become less prominent, mirroring a broader retrenchment within the rapid grocery delivery sector. This shift exemplifies the current state of European retail innovation, where the early exuberance for digital-first models is giving way to a more disciplined, capital-efficient phase, fundamentally reshaping competition for established incumbents and nimble startups alike.
For several years, venture capital flowed freely into European consumer technology, particularly in fragmented markets like online fashion and grocery. Companies like Gorillas and Flink, promising delivery in minutes, attracted billions, establishing a new consumer expectation while operating on thin, often negative, margins. Similarly, Cdiscount in France and Bol.com in the Netherlands expanded their general merchandise offerings, vying for market share against Amazon and local specialists.
The E-Commerce Capital Crunch
The tide began to turn with rising interest rates and a re-evaluation of growth-at-any-cost strategies. Funding rounds became smaller, valuations compressed, and the path to profitability gained paramount importance. This environment has disproportionately affected companies reliant on continuous external investment, especially those in highly competitive, low-margin sectors. Vinted, the Lithuanian-based second-hand fashion platform, represents a notable exception, demonstrating resilient growth and a clearer path to financial sustainability, having recently expanded its presence across Spain and Italy.
Consolidation is now an inevitability, rather than a mere possibility. Larger, established players like Zalando, while experiencing a slowdown in growth from pandemic-era highs, possess the infrastructure and existing customer bases to weather economic headwinds. Their strategic focus has shifted from aggressive acquisition of new users to enhancing profitability per customer and optimising logistics across their extensive European network, which spans from the Nordics to Poland.
The era of subsidised convenience is drawing to a close, compelling startups to prove the inherent value and operational efficiency of their models without relying on perpetual external subsidy.
Incumbents Adapt and Acquire
Traditional retail giants, including Carrefour in France and REWE and Lidl in Germany, have not been idle observers. Faced with the rise of online challengers, they have significantly invested in their own digital capabilities, often through partnerships or targeted acquisitions. Carrefour's recent investment in its e-commerce infrastructure, alongside its network of thousands of physical stores, creates a hybrid model that online-only players struggle to replicate. These legacy operators leverage their vast buying power and established supply chains, integrating online fulfilment with their existing physical footprint.
The Polish e-commerce leader, Allegro, exemplifies a different facet of this evolution. Operating as a dominant marketplace in Central Europe, it has successfully fended off international competition by deeply understanding local consumer preferences and logistics. Its cross-border strategy, particularly into neighbouring markets, is predicated on scale and a well-developed vendor ecosystem, offering a template for sustained regional leadership.
The immediate future for European retail startups appears challenging. While innovation persists, the focus has shifted towards defensible business models, operational efficiency, and a clear trajectory toward profitability. The landscape will likely feature fewer, but stronger, independent digital players, alongside a continued digital transformation among traditional brick-and-mortar entities, all vying for share of wallet across diverse continental European markets.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
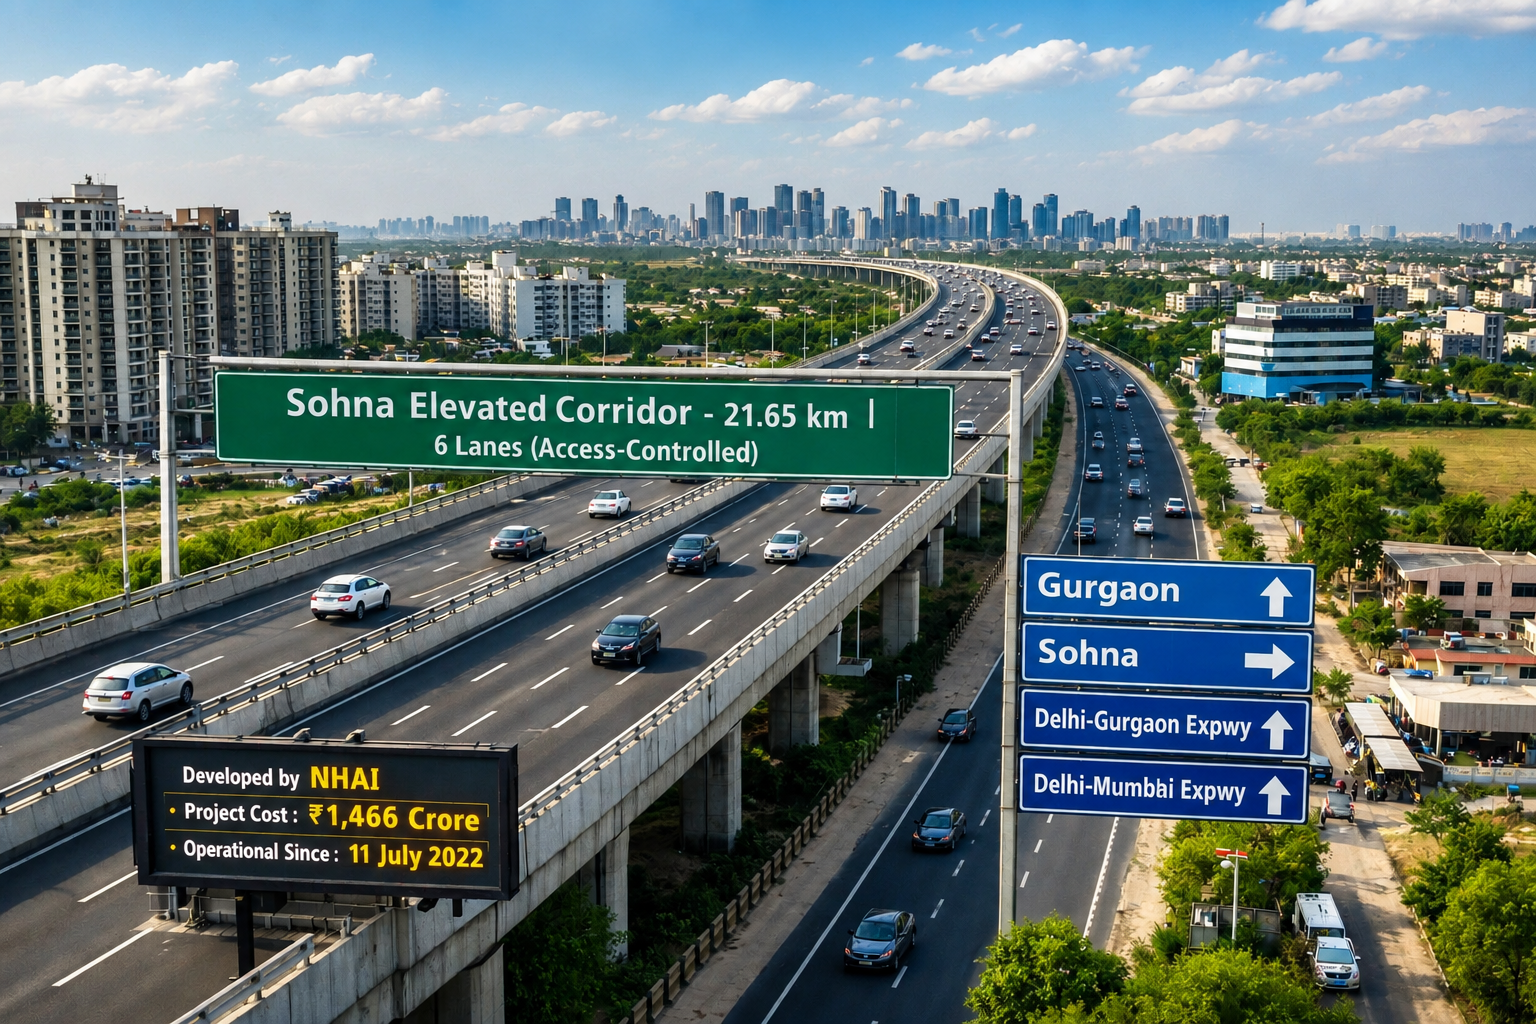
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
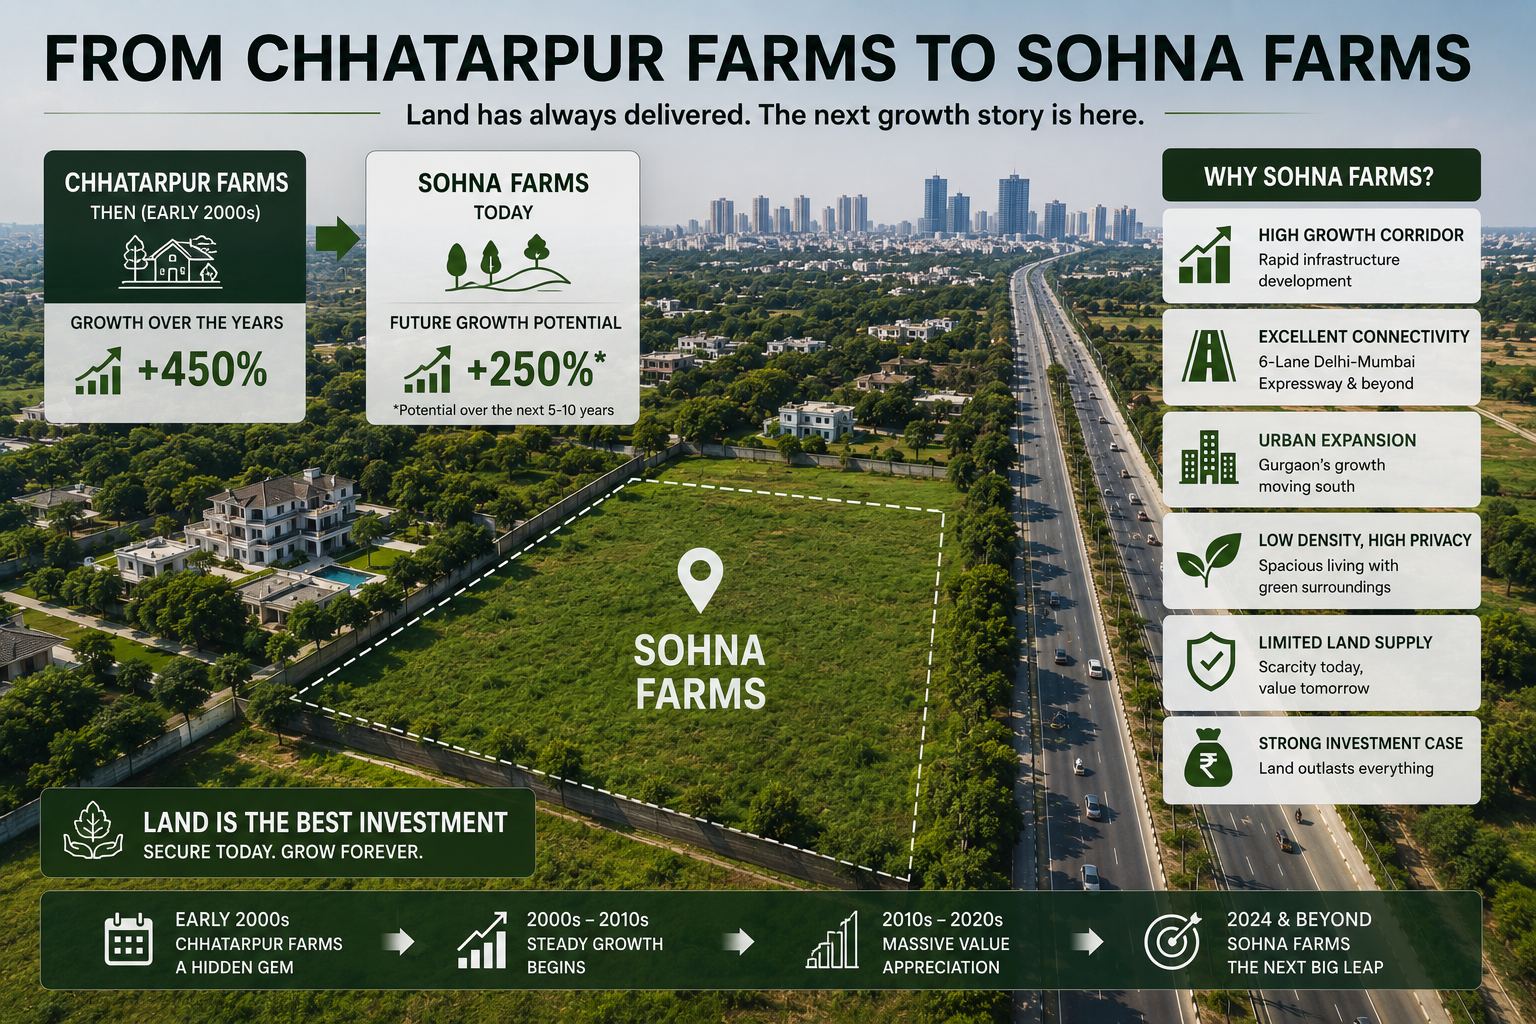
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
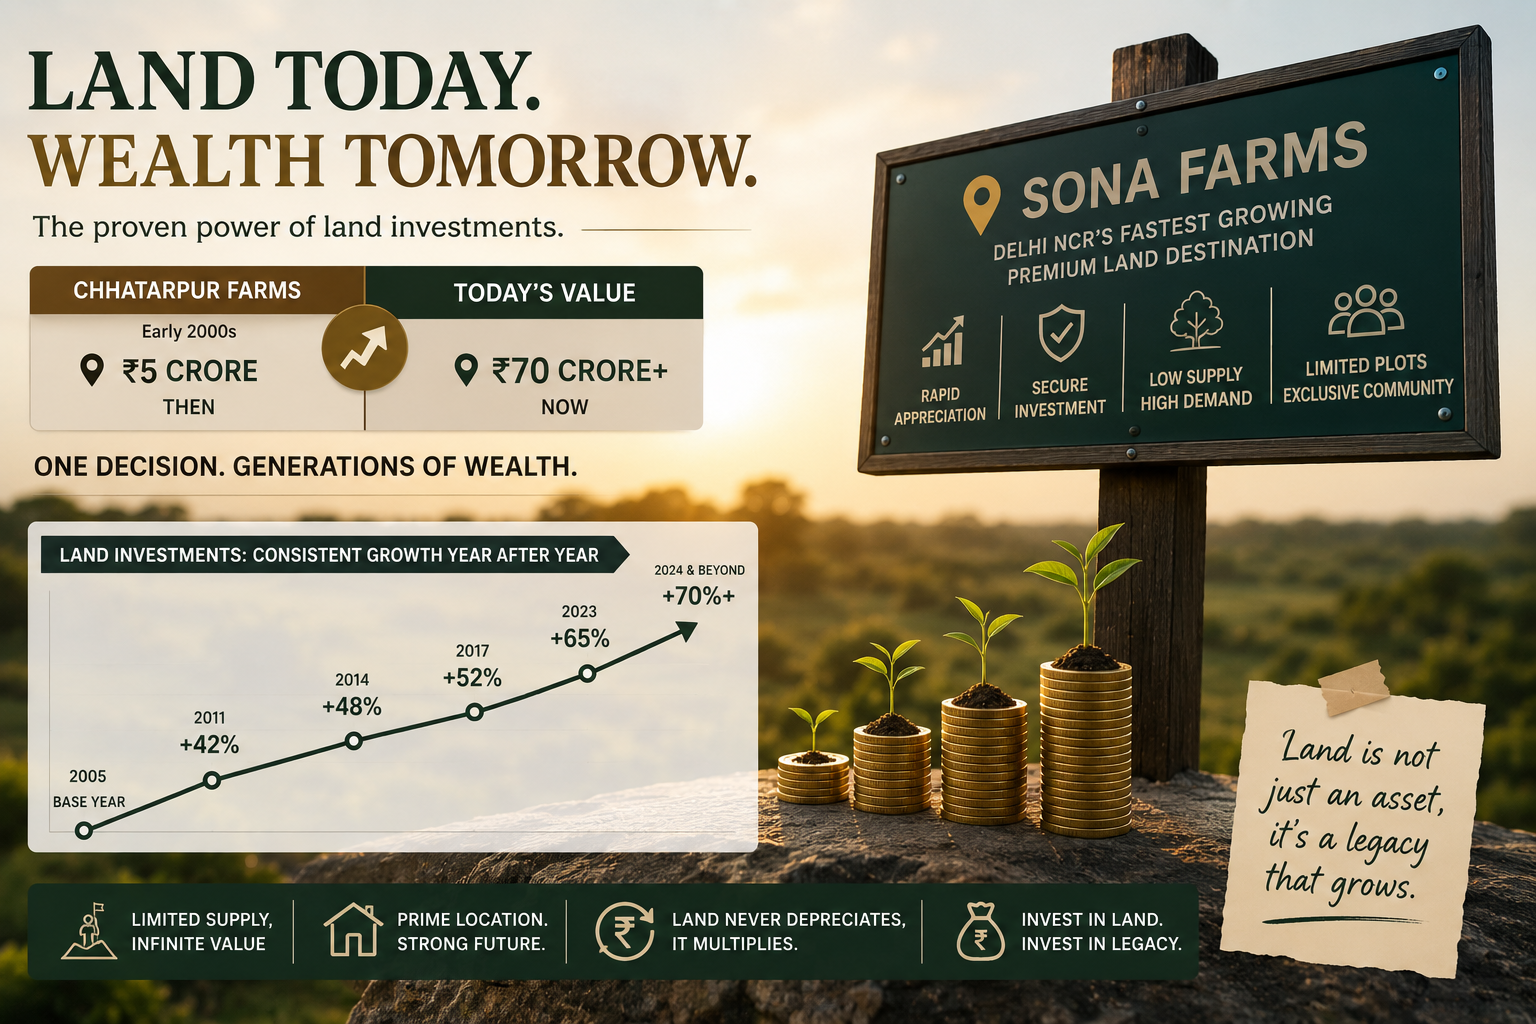
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.