Europe's Retail Fragmentation Persists Amid Digital Aggregation Efforts
Despite a decade of e-commerce expansion, continental Europe's retail landscape remains a patchwork, challenging even the most ambitious cross-border growth strategies for both established giants and nimble digital entrants.

From the bustling aisles of a Carrefour hypermarket in Lyon to the automated distribution centres supplying Bol.com customers in the Netherlands, European retail presents a study in contrasts. While digital platforms have streamlined access to goods across borders, the underlying commercial ecosystem continues to exhibit profound national distinctions. This fragmentation, shaped by regulatory divergence, linguistic barriers, and entrenched consumer habits, often impedes the creation of a truly unified continental market, affecting profitability and scale for many operators.
Zalando's formidable presence in fashion e-commerce or Allegro's dominance in Poland might suggest otherwise, yet their success often stems from bespoke market approaches rather than a blanket strategy. The aspiration for a seamless European shopping experience frequently confronts the reality of differing payment preferences, varied return policies, and the complex logistics of last-mile delivery across diverse urban and rural topographies.
The Lingering Legacy of National Champions
Traditional retail behemoths, such as Germany's REWE or Lidl, have successfully expanded internationally within Europe, but primarily through physical store networks and a decentralised, often country-specific, management model. Their digital strategies, while evolving, frequently reflect these national distinctions, making cross-platform integration across multiple EU states a considerable undertaking. The operational complexities involved in standardising pricing, promotions, and product assortments across countries with distinct supply chains and competitive environments are immense.
For newer digital players, the path to pan-European scale is similarly arduous. Vinted, the Lithuanian-born second-hand fashion marketplace, has achieved significant penetration, yet its growth has involved careful localisation, from user interfaces to marketing campaigns. The failure of many rapid grocery delivery services, such as Gorillas and the challenges faced by Flink, underscores the capital-intensive nature and fine-grained local requirements of scaling even seemingly simple digital models across multiple European cities.
Logistical and regulatory hurdles compound these challenges. Shipping goods from Spain to Sweden or navigating disparate VAT regimes across the bloc adds layers of cost and complexity that do not exist within the United States or China's single market. Fulfilment networks, while increasingly sophisticated, still encounter bottlenecks at national borders, especially for high-value or regulated goods. This necessitates significant investment in local warehousing and delivery infrastructure.
The allure of a 450-million-consumer market is undeniable, but it is not a monolithic entity. Retailers must acknowledge and adapt to the persistent idiosyncrasies that define each national commercial environment.
While some European tech firms have expanded successfully, the path is often circuitous. Cdiscount, a prominent French e-commerce player, has focused its cross-border ambitions more on adjacent Francophone markets or specific product categories rather than an attempt to blanket the continent. This pragmatic approach acknowledges the high cost of acquiring and retaining customers in highly competitive and culturally distinct markets like Germany or Italy.
The sustained growth of marketplaces, both generalist and specialist, indicates a continued aggregation of consumer demand, yet this aggregation frequently occurs at a platform level rather than a seamless cross-border retail brand. These platforms act as conduits, connecting fragmented supply with fragmented demand, often absorbing the complexity rather than eliminating it. Even within the Eurozone, the promise of a truly harmonised digital single market in retail remains an aspiration, not a complete reality.
Ultimately, the European retail story is one of enduring national character intersecting with digital ambition. Success often lies not in bulldozing these distinctions, but in a nuanced appreciation of local consumer preferences, regulatory frameworks, and competitive dynamics. The drive for greater efficiency and scale will persist, yet the path to genuine pan-European retail integration continues to be paved with careful market-by-market navigation.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
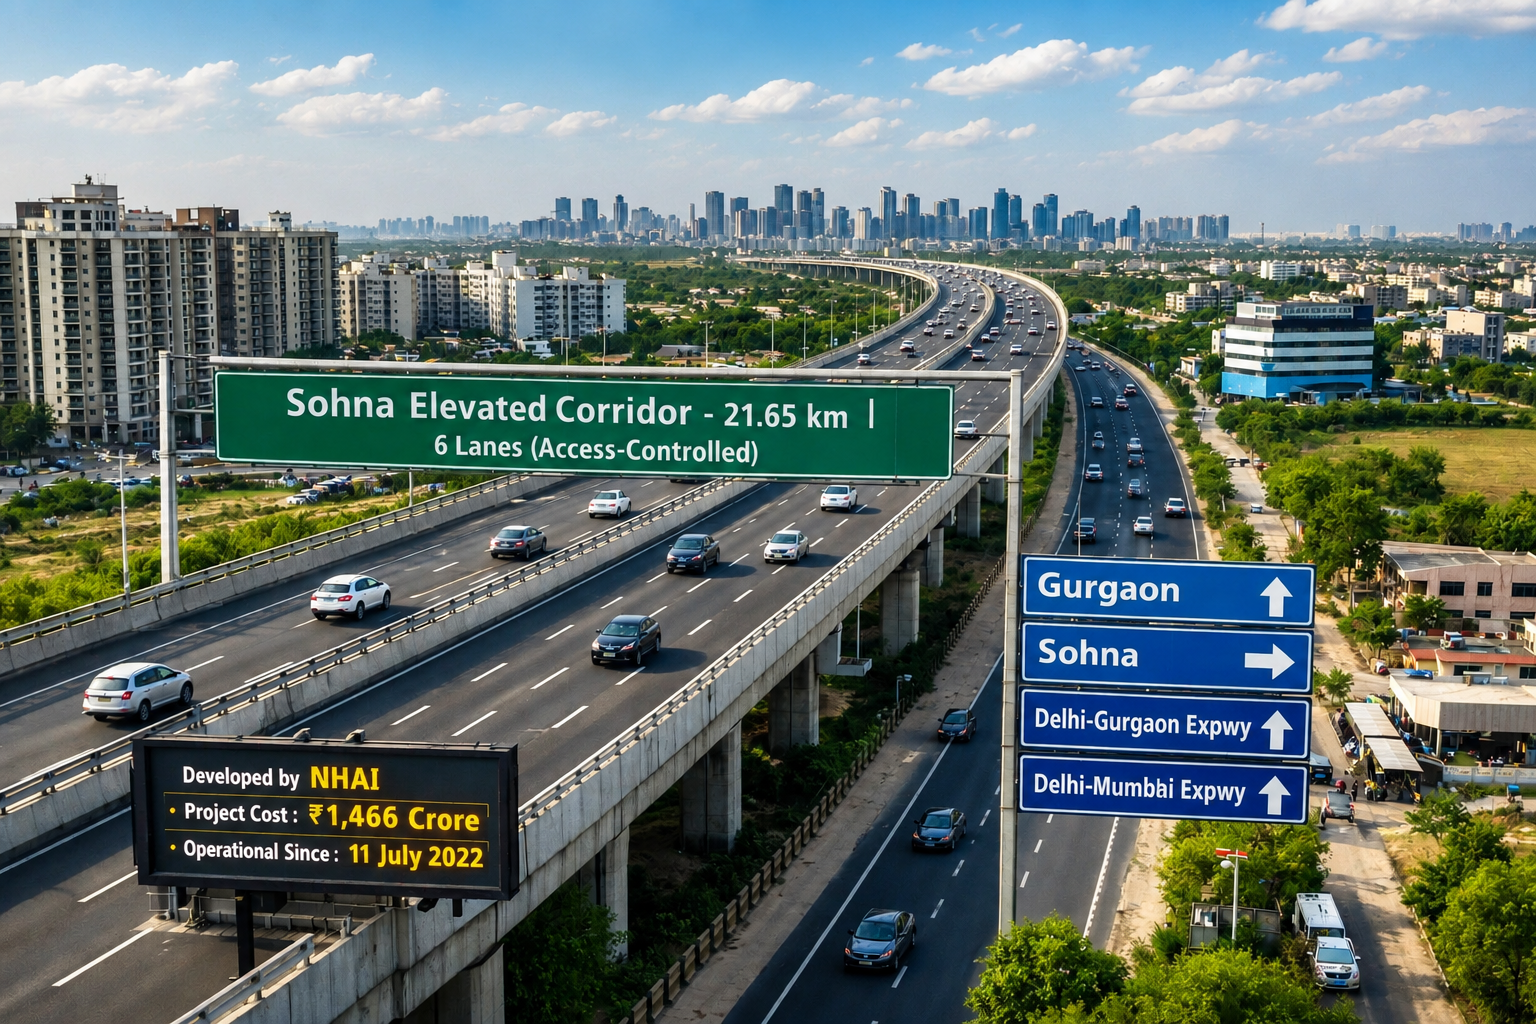
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
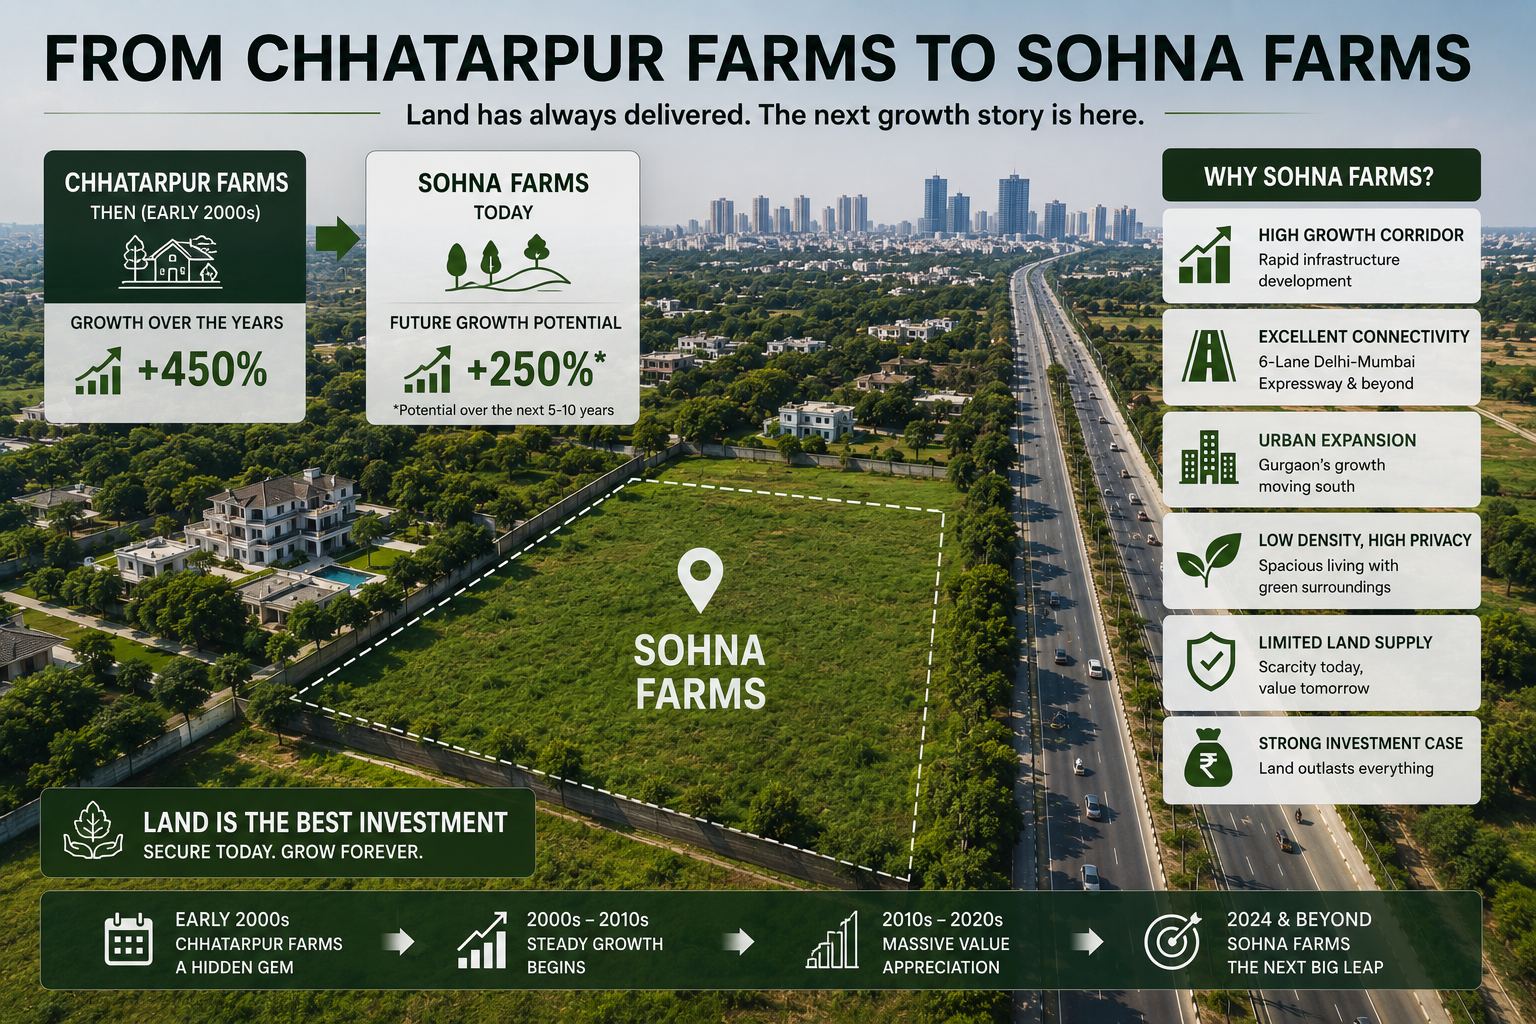
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
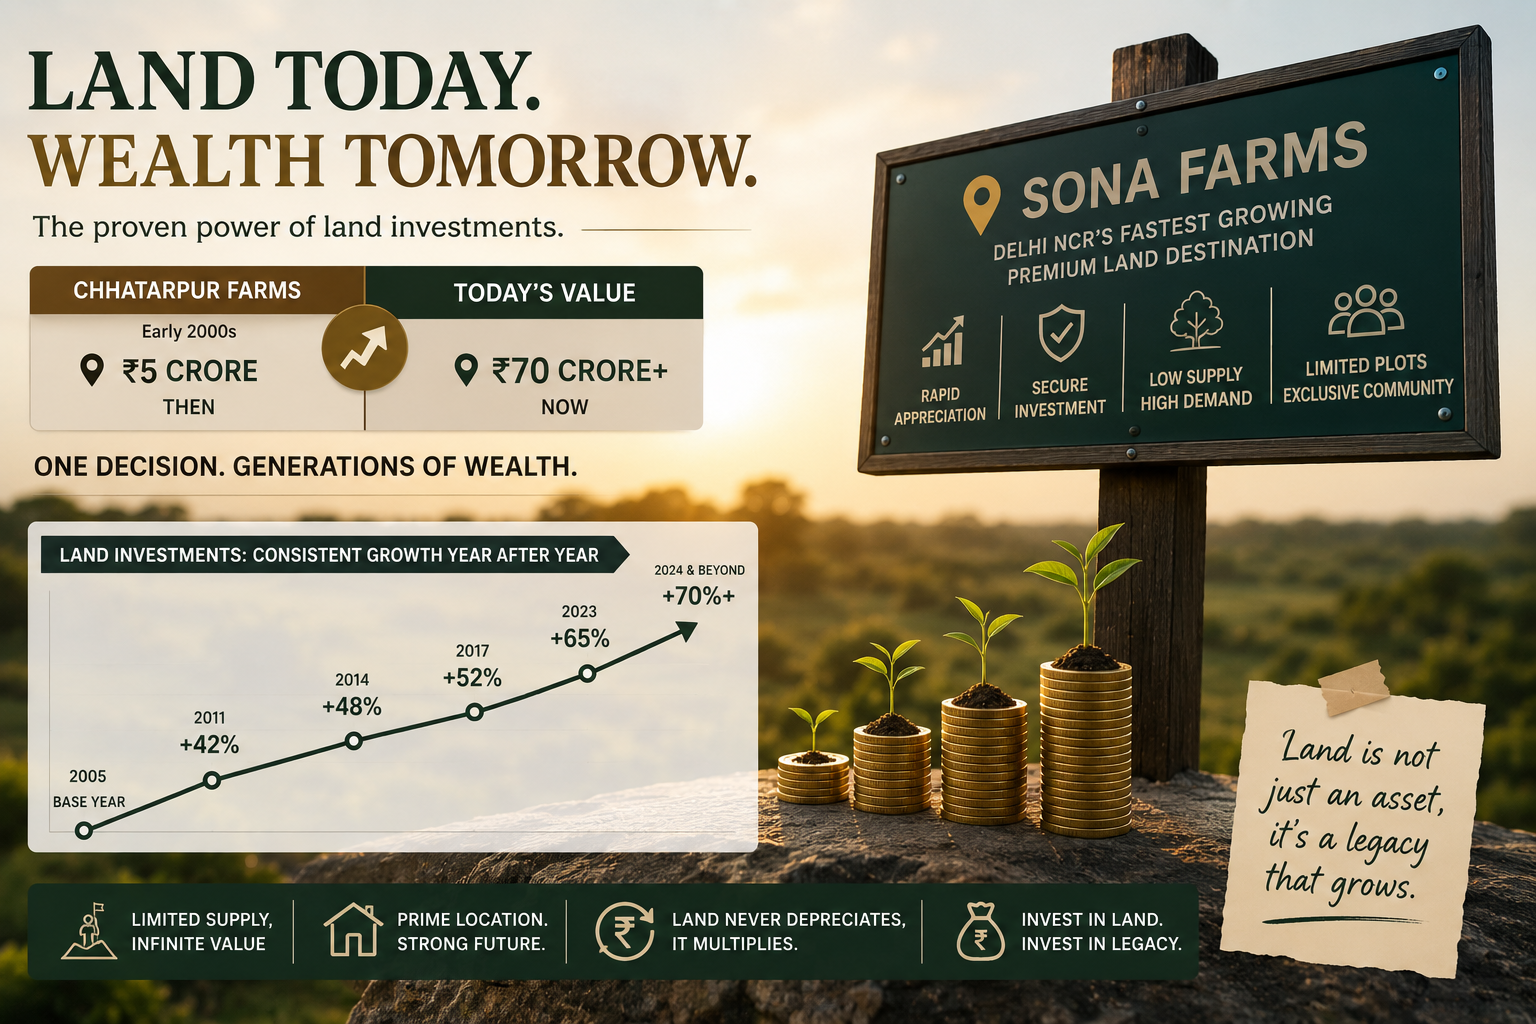
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.