The Composable Hangover: British Merchants Tally the Hidden Costs of Modular Software
After spending heavily to assemble bespoke digital storefronts from dozens of specialised vendors, UK retailers are paring back software sprawl in pursuit of operating cash.

Inside the technology estates of Britain's listed retailers, procurement desks are scrutinising enterprise software contracts with unprecedented severity. Following half a decade of unbundling core commerce engines into best-of-breed microservices, the bill for maintaining dozens of overlapping cloud subscriptions has arrived at an inopportune moment. With household budgets constrained, shop-floor wage bills climbing, and online customer acquisition costs unyielding, high-street stalwarts from Marks & Spencer to ASOS are discovering that the architectural purity of 'headless commerce' carries a punitive operational tax.
The prevailing doctrine between 2019 and 2022 urged digital directors to abandon monolithic enterprise systems from legacy suppliers. In their place, technology consultancies prescribed composable architectures: independent microservices covering checkout, dynamic search, catalogue indexing, and inventory orchestration, stitched together via application programming interfaces (APIs). For nimble digital pureplays chasing rapid deployment, the approach offered genuine agility. Yet for established British operators wrestling with sprawling physical estates, fragmented legacy databases, and complex store-replenishment cycles, the model introduced compounding integration fragility.
The Integration Surcharge
The financial drag of this software fragmentation has become acute. A mid-tier fashion merchant turning over £250 million can easily find itself managing twenty distinct software vendors across its commerce estate, each billing on variable consumption metrics such as API calls, monthly active accounts, or gross merchandise volume. When digital traffic spikes during clearance events such as Black Friday, usage-based cloud licensing multiplies precisely as promotional discounting erodes gross margins. One enterprise systems adviser observes that engineering teams at several British clothing labels now spend more than a third of their working hours maintaining point-to-point connections between disparate software products, rather than deploying commercial improvements to the customer experience.
The promise of seamless modularity collided with the reality of maintaining dozens of disparate cloud contracts during a consumer downturn.
Next plc has demonstrated the viability of the polar opposite strategy. Through its Total Platform division, the Leicestershire-based giant has commercialised its deeply unified internal infrastructure, absorbing client brands such as Reiss, FatFace, and Joules into an end-to-end stack that handles website hosting, payment routing, and warehouse dispatch simultaneously. Rather than paying external SaaS vendors for piecemeal software licences, participating retailers surrender a single percentage of turnover. For Next, the division yields high-margin recurring income; for client brands, it replaces volatile enterprise software overheads with predictable variable expenditure.
Re-bundling and Balance-Sheet Realism
Even grocery leaders, which operate at razor-thin operating margins between two and three per cent, are drawing firmer boundaries around third-party digital tools. While Ocado Group continues to market its proprietary Smart Platform to overseas partners with mixed commercial uptake, domestic chains like Sainsbury’s and Tesco have concentrated their technology capital on proprietary loyalty tooling—namely Nectar Prices and Clubcard analytics—while pruning external customer-experience software. Delivery intermediaries such as Deliveroo and Just Eat have similarly internalised dispatch routing and merchant-facing software rather than licensing off-the-shelf dispatch products.
Enterprise commerce vendors have recognised the shifting mood. Software houses that previously championed radical unbundling are quietly packaging their point solutions back together, offering pre-integrated suites with guaranteed interoperability and volume discounts to stem client attrition. For British retailers navigating persistent domestic cost pressures, the romanticism of architectural perfection has surrendered to balance-sheet pragmatism. The prevailing mandate is no longer to construct the most modular commerce stack in London, but the most defensible one.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
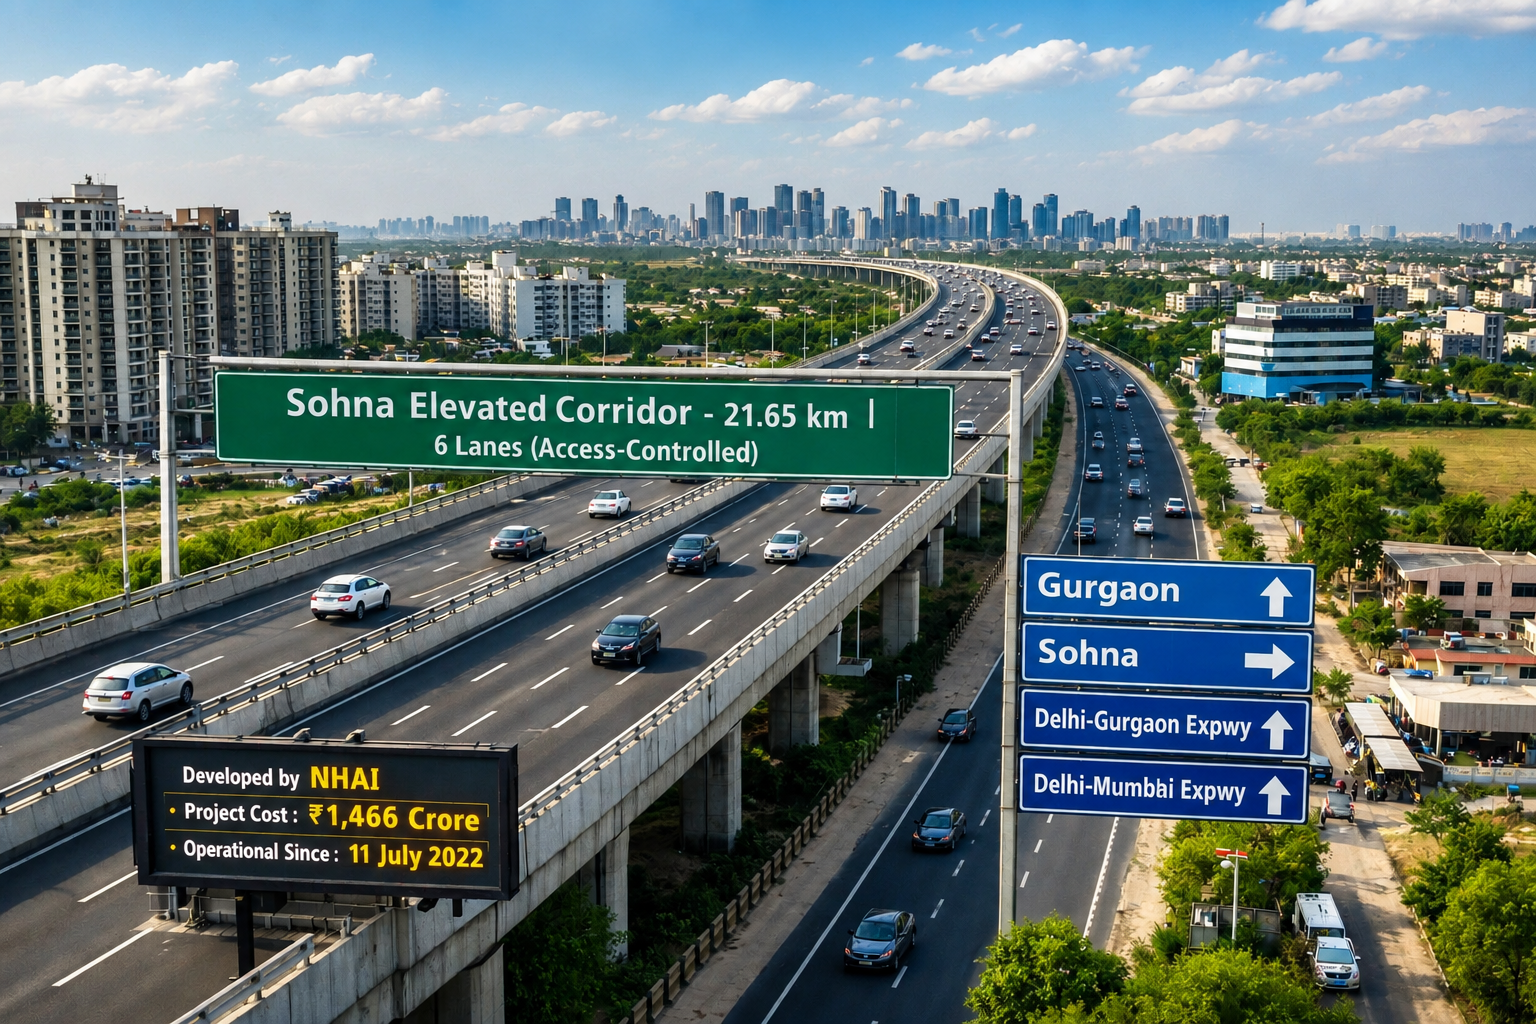
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
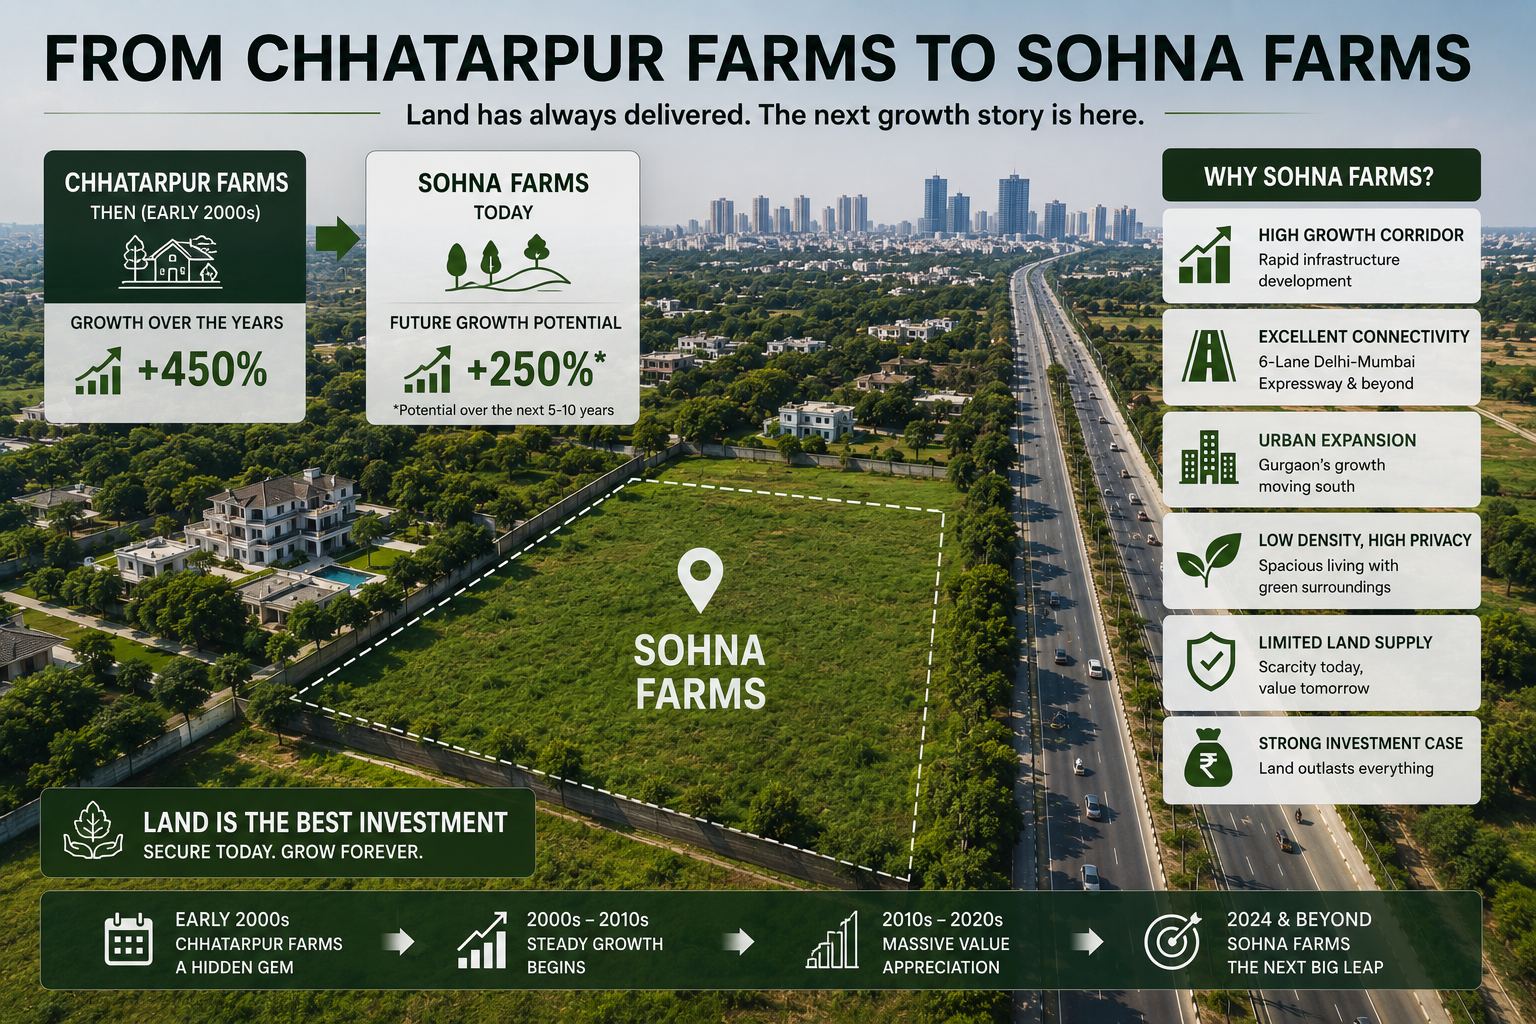
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
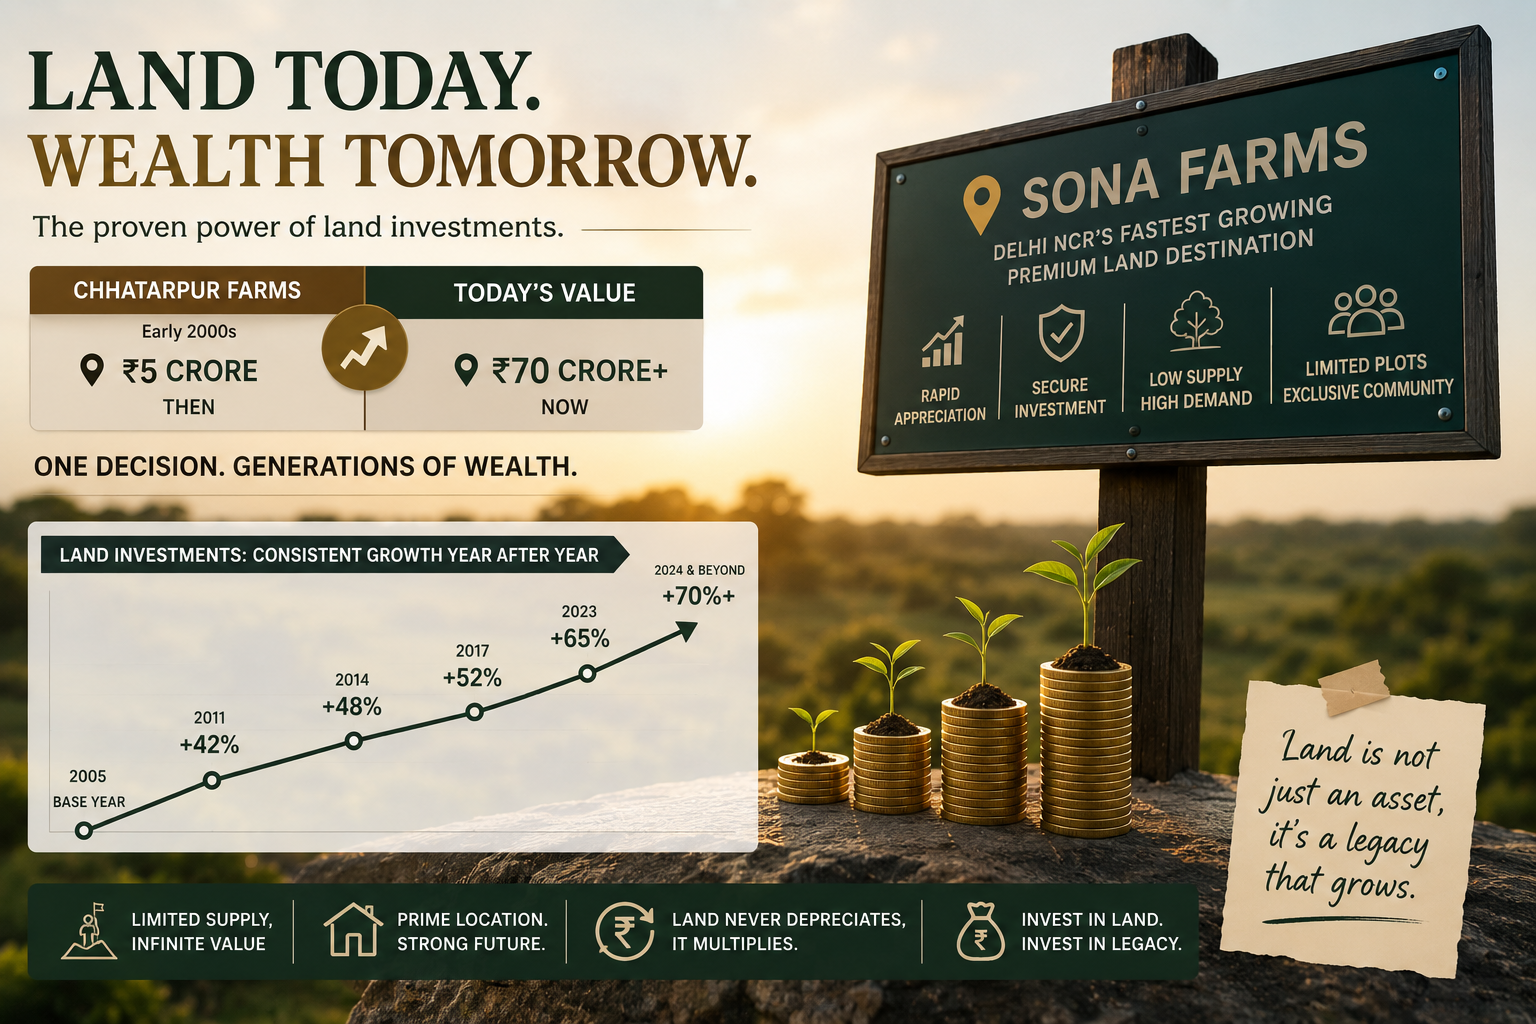
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.