The Continental Consolidation: How Europe’s Retail Giants Are Stitching Together a Fragmented Freight Grid
Faced with stubborn border frictions and sovereign carrier monopolies, the continent's largest digital merchants are abandoning standalone fulfillment in favour of shared logistics infrastructure.

At a distribution terminal outside Poznań, articulated lorries bearing Polish, German and Lithuanian plates idle in uniform queues, their trailers loaded with mixed pallets destined for households from Dresden to dynamic urban corridors in northern Italy. The scene bears little resemblance to the feverish, hyper-local hubris of three years ago, when venture capital poured billions into dark-store operators such as Gorillas and Flink in a bid to conquer individual city quarters. Instead, the real battleground for European e-commerce profitability has migrated to regional transit arteries, where cross-border freight integration is quietly displacing the promise of ten-minute urban couriers.
The shift is born of necessity. While the European Union prides itself on a single market for goods, parcel transit across internal borders remains stubbornly inefficient. Moving a five-kilogram package from North Rhine-Westphalia to a collection point in Lyon or Valencia routinely costs twice as much as a domestic shipment of comparable distance, caught in a tangle of legacy postal handoffs, disparate labour regulations and fragmented regional sortation systems. For pure-play operators whose operating margins hover in the low single digits, these cross-border frictions have become untenable.
The Retreat from Ultra-Fast Illusions
The reckoning in quick commerce served as an expensive lesson in unit economics. The retrenchment of rapid-delivery startups across Paris, Berlin and Madrid forced supermarket incumbents such as Carrefour, REWE and Lidl to reassert control over food retail logistics. Rather than attempting to maintain dozens of sub-scale urban micro-fulfilment nodes, the traditional grocers have consolidated online orders into automated peri-urban facilities, pairing ambient goods with fresh lines on structured, scheduled delivery runs. Capital expenditure has been redirected from transient gig-economy courier fleets toward automated crate-handling and predictable route densities.
In non-grocery retail, the imperative to compress distribution overheads has birthed an unexpected convergence around out-of-home delivery networks. P2P fashion marketplace Vinted, having established deep consumer reach across France, Spain and the Benelux, has deployed its own locker and drop-off division, Vinted Go, treating parcel collection not as a third-party ancillary cost but as an owned asset class. Similarly, Poland's Allegro has leveraged its dominant domestic position—built on automated locker density pioneered alongside InPost—to anchor its broader Central European ambitions, demonstrating that consumers are willing to forgo home delivery if the alternative avoids steep shipping surcharges.
Wholesale Fulfillment as a Defensive Moat
Out-of-home parcel networks and syndicated line-haul corridors are transforming European logistics from a proprietary marketing gimmick into a shared, capital-intensive utility.
Scale has thus become an existential prerequisite, prompting platform operators to open their proprietary supply chains to outside capital. Zalando’s expansion of its unified logistics platform, which allows multi-channel brands to route inventory through its European distribution footprint regardless of whether the transaction occurred on its own storefront, marks a fundamental strategic pivot. By pooling stock across Germany, the Nordics and southern Europe, the Berlin-based retailer is attempting to convert its heavy physical plant into a high-margin business-to-business utility, mimicking the multi-tenant models that transformed cloud computing.
Regional champions are responding with defensive federations. In the Low Countries, Bol has deepened investments in automated warehousing to shield its cross-border margins against foreign entrants, while France’s Cdiscount has leaned into third-party fulfillment services to offset softer domestic discretionary spending. Yet without continuous capital injections to modernise sortation hubs and secure zero-emission line-haul capacity, standalone national networks will struggle against unified operators capable of amortising fixed fleet costs across multiple territories. The coming phase of European logistics will not be defined by who delivers the fastest, but by who can move freight across internal borders with the least friction.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
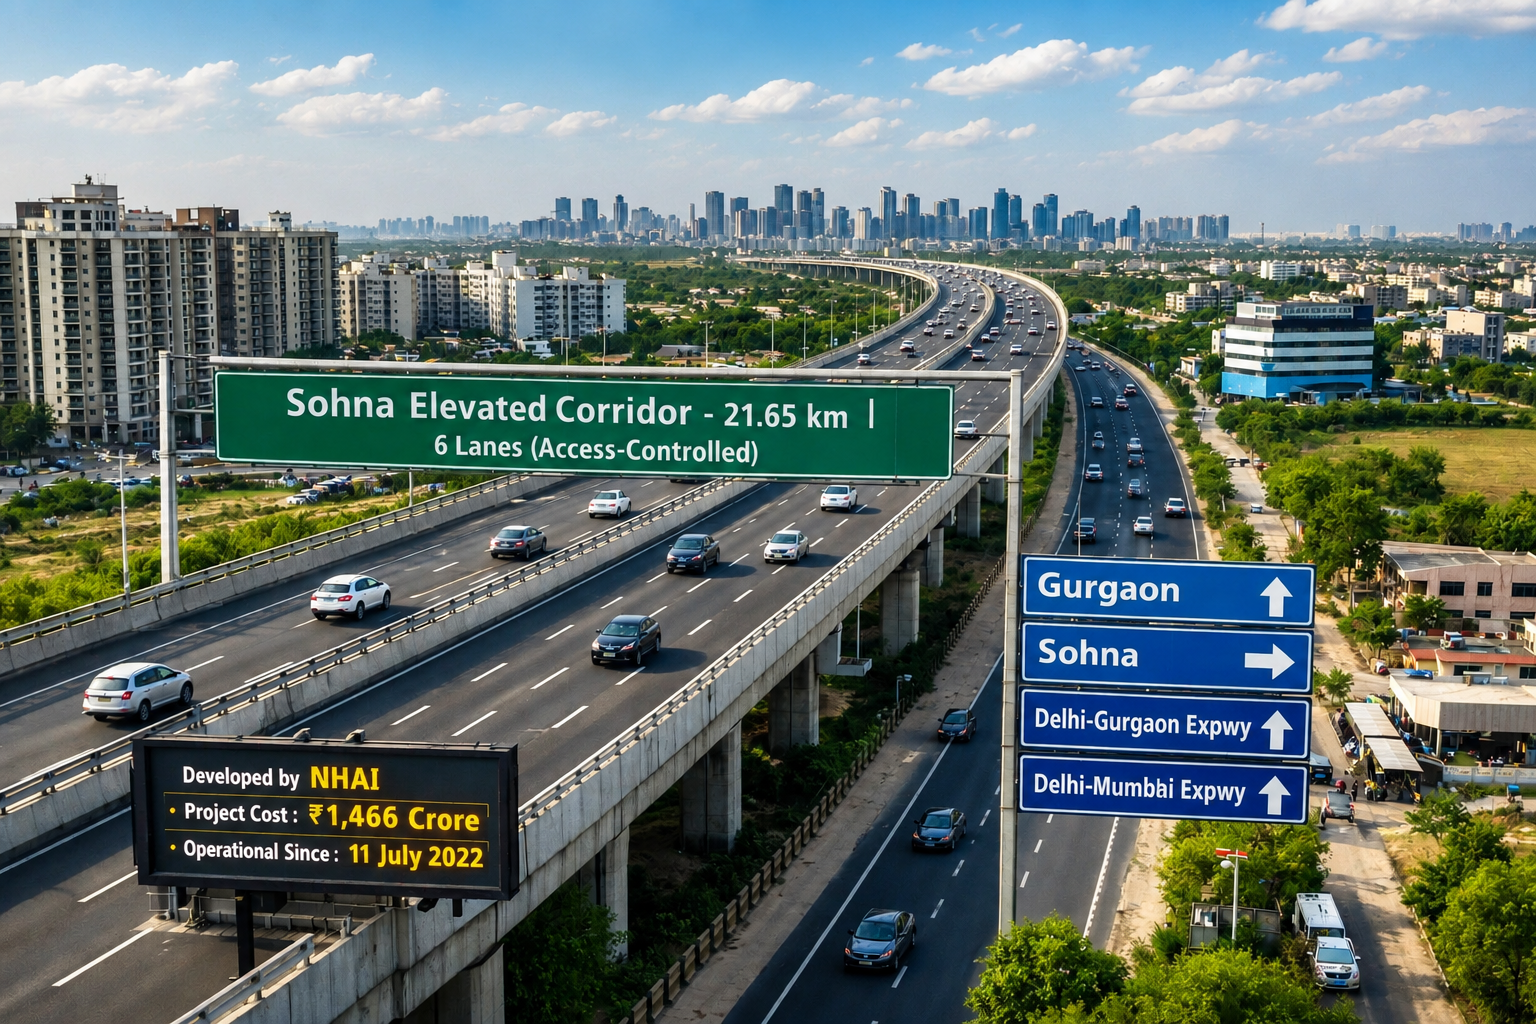
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
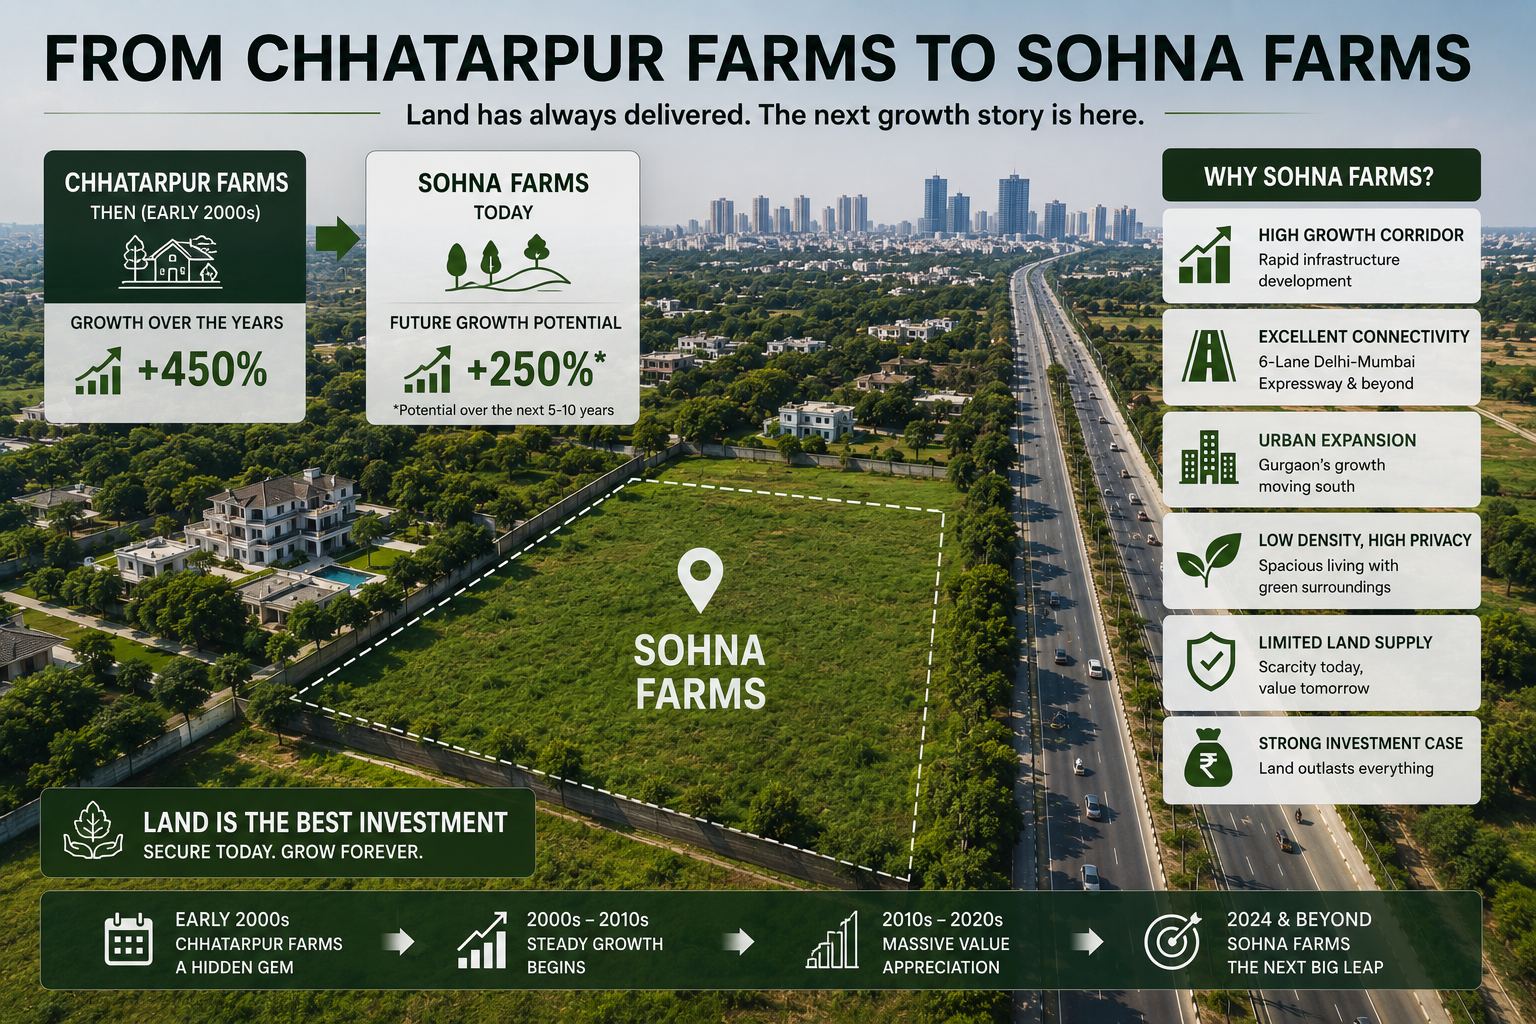
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
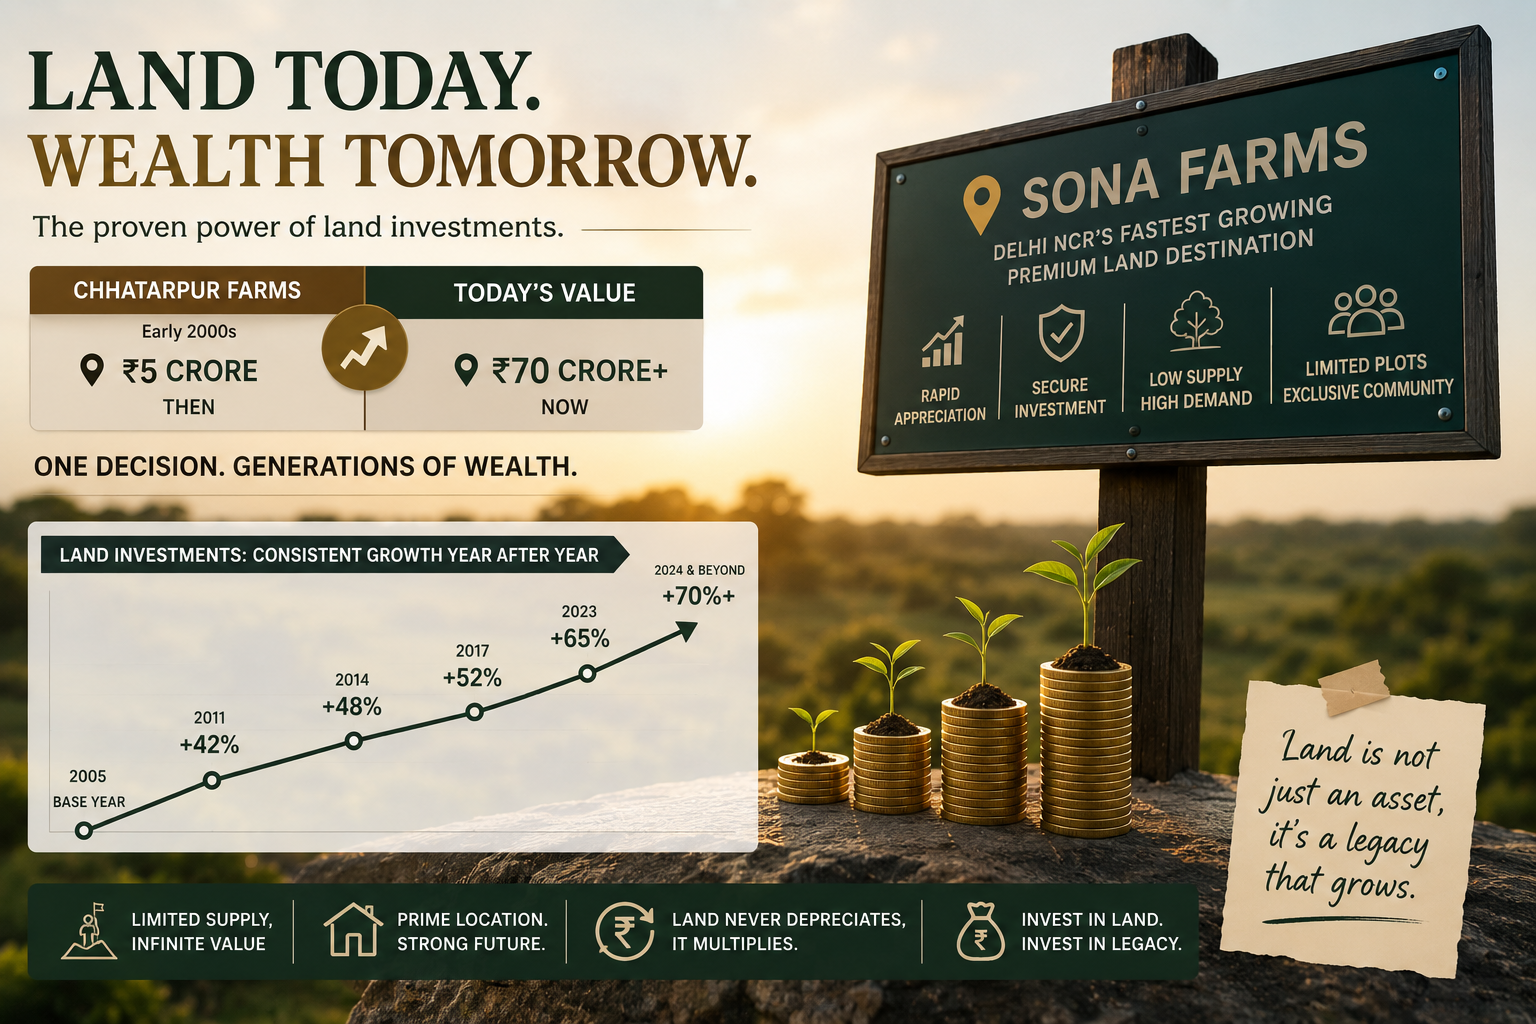
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.