The Decoupled Basket: How Split-Shopping Disrupted Britain’s High-Street Grocers
British households have abandoned the solitary weekly trolley run in favour of calculated multi-channel scavenging, squeezing legacy grocers between staple discounters and premium convenience.

Walk into a suburban Tesco Extra on a Saturday morning, and the cavernous central aisles tell a quiet story of structural leakage. Where families once loaded car boots with a single weekly trolley load worth £120 or more, consumers now execute a fragmented domestic ritual: buying dried goods and produce from German discounters, deploying supermarket loyalty apps defensively for packaged staples, and turning to Marks & Spencer or Deliveroo for impromptu evening meals. The traditional all-in-one shopping trip, the bedrock of post-war British supermarket economics, has broken down.
The phenomenon, known in commercial boardrooms as basket decomposition, has outlasted the peak of the cost-of-living crisis. Even as headline food inflation softened from its double-digit heights, British shoppers retained the spreadsheet-style discipline developed during the inflationary spike. Households have grown accustomed to treating every category as an independent procurement decision, distributing expenditure across three or four competing fascia per week rather than handing their entire budget to a single merchant.
The Erosion of the Big Trolley
Both Tesco and J Sainsbury responded to the structural challenge by pouring hundreds of millions of pounds into Aldi and Lidl price-match mechanisms, while fencing off their most competitive rates behind Clubcard and Nectar schemes. Yet this defensive moat has produced an unintended commercial consequence. While loyalty discounting succeeded in stemming raw volume defection to the discounters, it systematically trained middle-class shoppers to buy almost exclusively on promotion. The profitable, high-margin centre of the basket—ambient branded goods, cleaning supplies, and packaged treats—has hollowed out as consumers substitute private label or defer purchases.
Loyalty apps have successfully defended raw market share, but they have also trained Britain’s middle class to act as ruthless arbitrageurs.
Meanwhile, the premium end of the grocery market has decoupled from the out-of-town hypermarket entirely. Marks & Spencer has captured significant market momentum by repositioning its food halls around immediate, high-value dining solutions, effectively capturing the discretionary expenditure that previously padded out weekend supermarket receipts. A shopper who scrupulously buys tinned tomatoes and laundry detergent at baseline cost will, on the same afternoon, spend £14 on a chilled meal kit and artisan sourdough without hesitation.
The Convenience Overhead
This bifurcation is equally pronounced in the rapid-fulfilment sector. The race for grocery volume has drawn delivery intermediaries such as Deliveroo and Just Eat into long-term commercial tie-ups with physical grocers, alongside specialist micro-depot operations like Ocado Zoom. These partnerships allow traditional operators to access unplanned top-up spend, yet they introduce profound operational friction. Picking bespoke two-item baskets of fresh herbs and wine off standard supermarket shelves incurs substantial picking and platform commission costs that thin convenience margins to the wire.
Across the broader retail landscape, including general merchandise and fast fashion, a similar consumer calculation is unfolding. Platforms such as ASOS and Next have moved aggressively to introduce paid returns and adjust dispatch thresholds precisely because the era of subsidised basket experimentation is over. When consumers buy deliberately and with narrow intent, the logistical overhead of carrying inventory and managing reverse supply chains becomes unsupportable.
The modern British retail sector is coming to terms with the reality that the unified weekly shop is unlikely to return. As algorithmic discounting, quick-commerce delivery, and neighbourhood food halls continue to carve household expenditure into discrete daily transactions, scale of floor space is no longer the defensive asset it once was. Profitability now hinges on capturing specific meal occasions or hyper-efficient staple distribution, leaving operators marooned in the undifferentiated middle with little room to manoeuvre.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
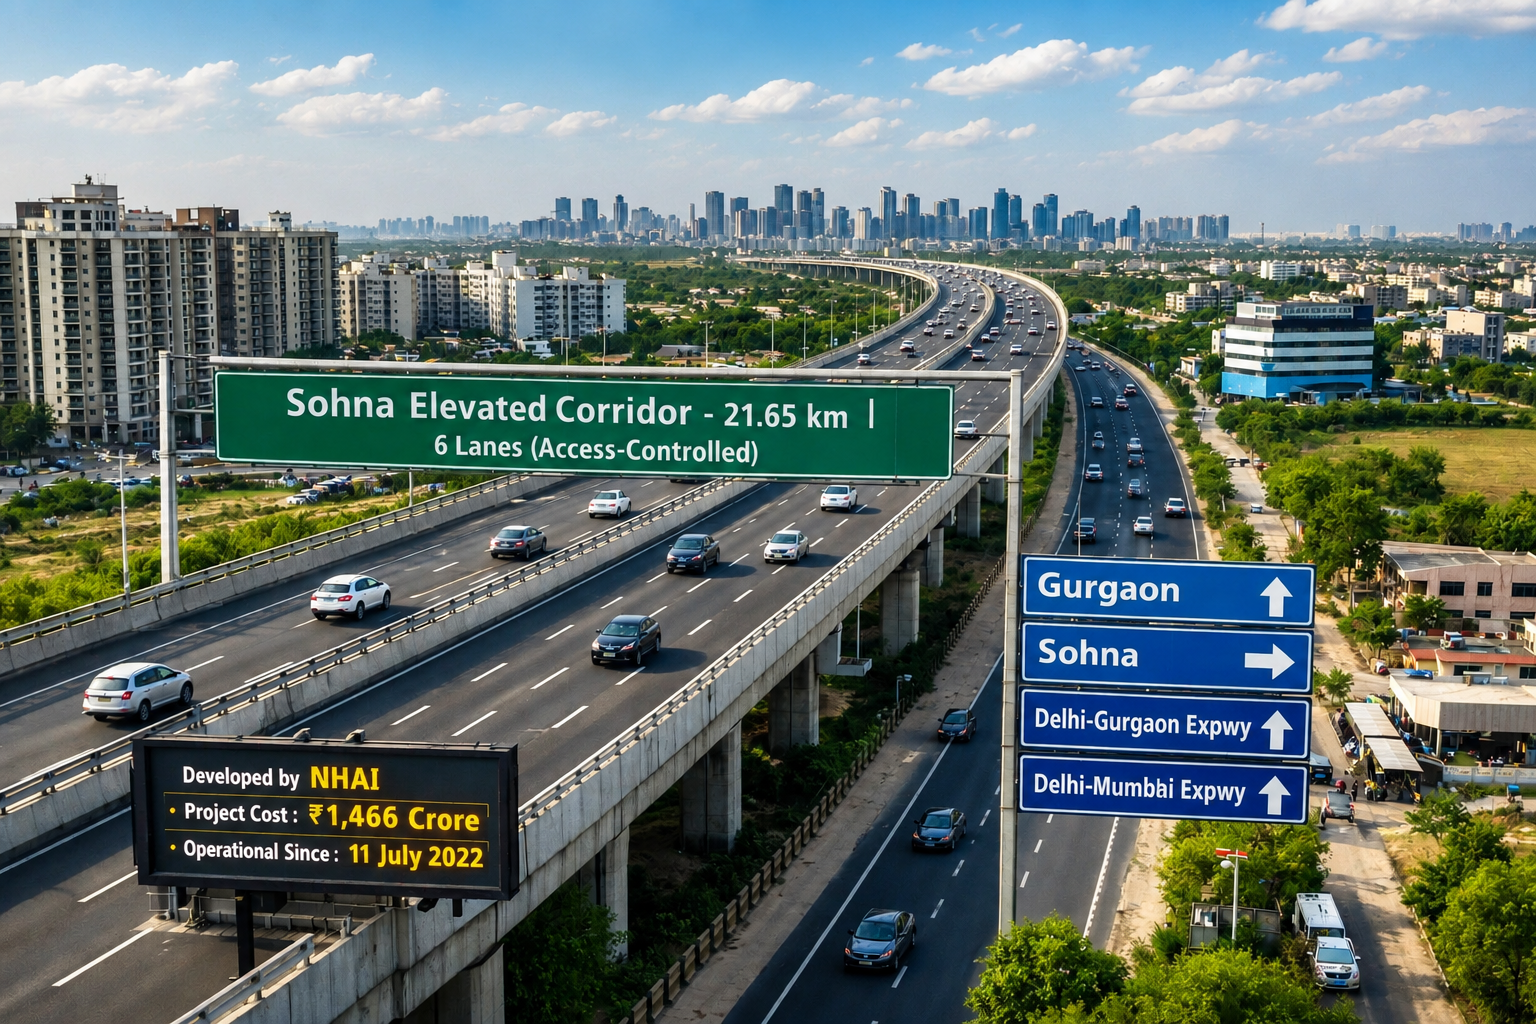
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
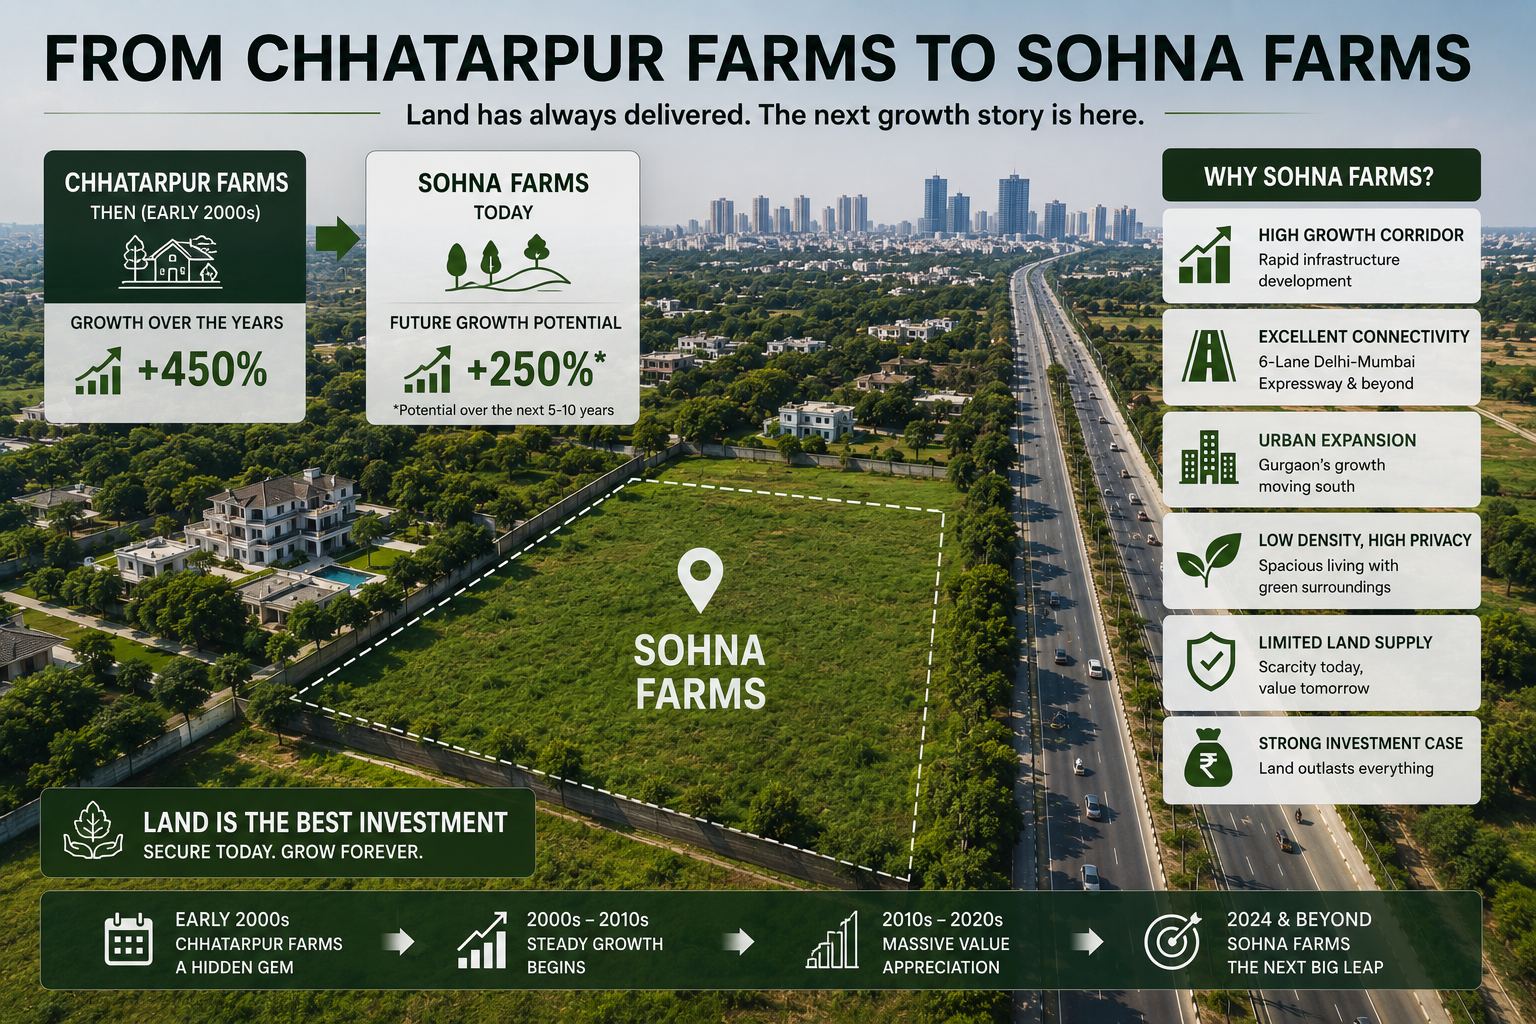
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
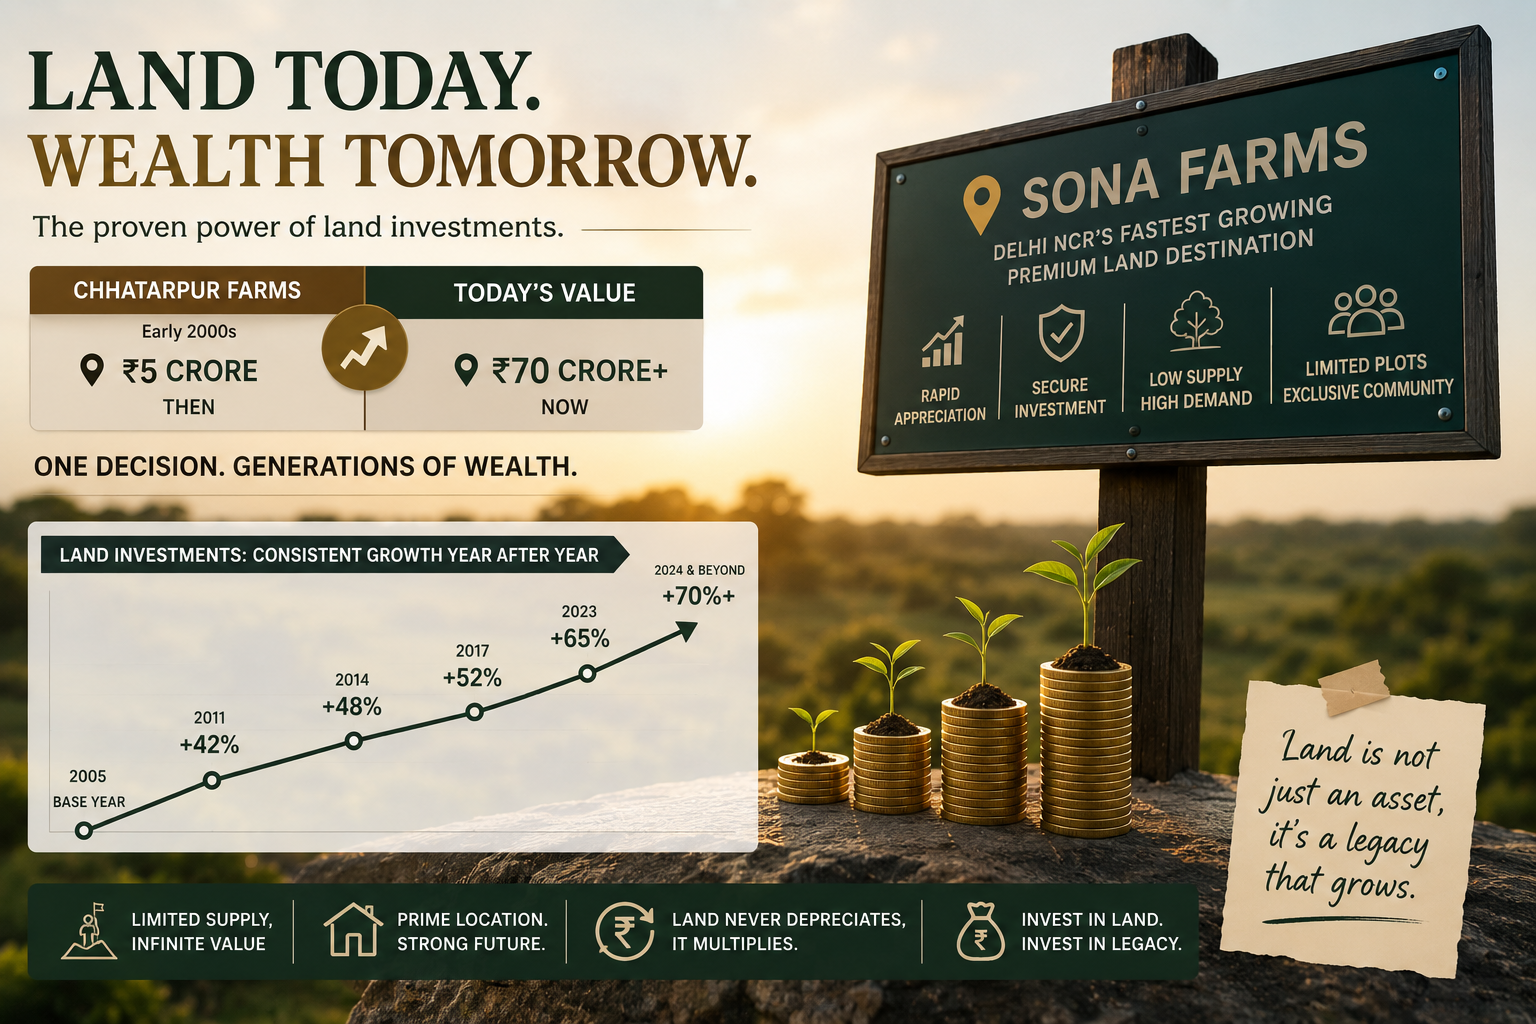
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.