The Differentiated Dilemma: UK DTC Brands Navigate a Shrinking Path to Profit
Direct-to-consumer models face heightened scrutiny as venture capital tightens and established British retailers refine their digital propositions, forcing a strategic re-evaluation for online-first brands.

Consider the trajectory of a brand like Made.com. Once heralded as a disruptor in furniture retail, its eventual collapse into administration underscored a growing challenge for UK direct-to-consumer (DTC) businesses. While its demise was multifactorial, it highlighted the increasing capital intensity and operational complexities inherent in scaling an online-only operation, particularly when competing with incumbents and facing economic headwinds.
The initial allure of DTC – lower overheads, direct customer relationships, and perceived agility – attracted significant investment. For a period, brands like Gymshark, Huel, and Bloom & Wild demonstrated that bypassing traditional retail channels could yield rapid growth and fervent customer bases. However, the landscape has shifted; the cost of customer acquisition has escalated dramatically, and the operational burden of fulfilment, returns, and logistics now often outweighs the benefits of disintermediation.
The Scramble for Attention and Acquisition Costs
Customer acquisition, once a relatively affordable pursuit through social media advertising, has become a prohibitively expensive endeavour. The digital advertising market, dominated by a few large platforms, sees ever-increasing bids for impression share, diminishing the returns on marketing spend. For a new mattress brand or a subscription coffee service, standing out in a crowded digital marketplace requires substantial, often unsustainable, budgets. This trend has been acutely felt by UK DTCs, many of whom relied on efficient digital marketing to fuel their early expansion.
Moreover, the pandemic-driven surge in online shopping, which initially boosted many DTCs, has now stabilised. Consumers are returning to physical stores, and the novelty of pure online shopping has worn off for some categories. This reversion means DTC brands must now compete not just on convenience, but on an entire value proposition that justifies their higher prices or more niche offerings, often without the immediate trust factor of a high-street presence.
The era of rapid, unprofitable DTC expansion, fuelled by easy venture capital, appears to be concluding. Brands must now demonstrate a clear path to self-sustaining profitability.
Established UK retailers are not idly observing this shift. Tesco, Sainsbury's, and Marks & Spencer have significantly invested in their digital capabilities, offering sophisticated e-commerce platforms, click-and-collect services, and often same-day delivery through partnerships or proprietary networks. Their expansive physical footprints provide a crucial advantage, allowing for efficient last-mile delivery and a tangible customer experience that online-only players struggle to replicate at scale.
Evolving Consumer Expectations and Operational Realities
British consumers, increasingly accustomed to rapid delivery and seamless returns from giants like Amazon and pure-play fashion retailers like ASOS and Next, now hold higher expectations across all online purchases. Fulfilling these demands requires sophisticated logistics infrastructure, a significant capital expenditure that many DTCs deferred or outsourced. The razor-thin margins in many retail categories mean that every penny spent on shipping, warehousing, and processing returns directly impacts the bottom line, particularly when dealing with fluctuating demand.
The initial investment thesis for many DTCs often overlooked the long-term operational complexities. Building a brand is one aspect; constructing a resilient, cost-effective supply chain and customer service operation is another entirely. This reality has prompted a strategic shift among the more successful UK DTC brands, with some exploring wholesale partnerships with established retailers or even opening their own physical stores, effectively becoming 'omnichannel' despite their online origins. This move often requires them to cede some of the direct control that was their original raison d'être, highlighting the difficult choices confronting the sector.
As capital markets cool and investor sentiment prioritises profitability over pure growth, the UK's DTC landscape is undergoing a necessary maturation. Brands that can demonstrate robust unit economics, sustainable customer acquisition strategies, and efficient operational models will be the ones to thrive. The rest face increasing pressure to adapt, consolidate, or risk the fate of those who found the direct path unexpectedly circuitous.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
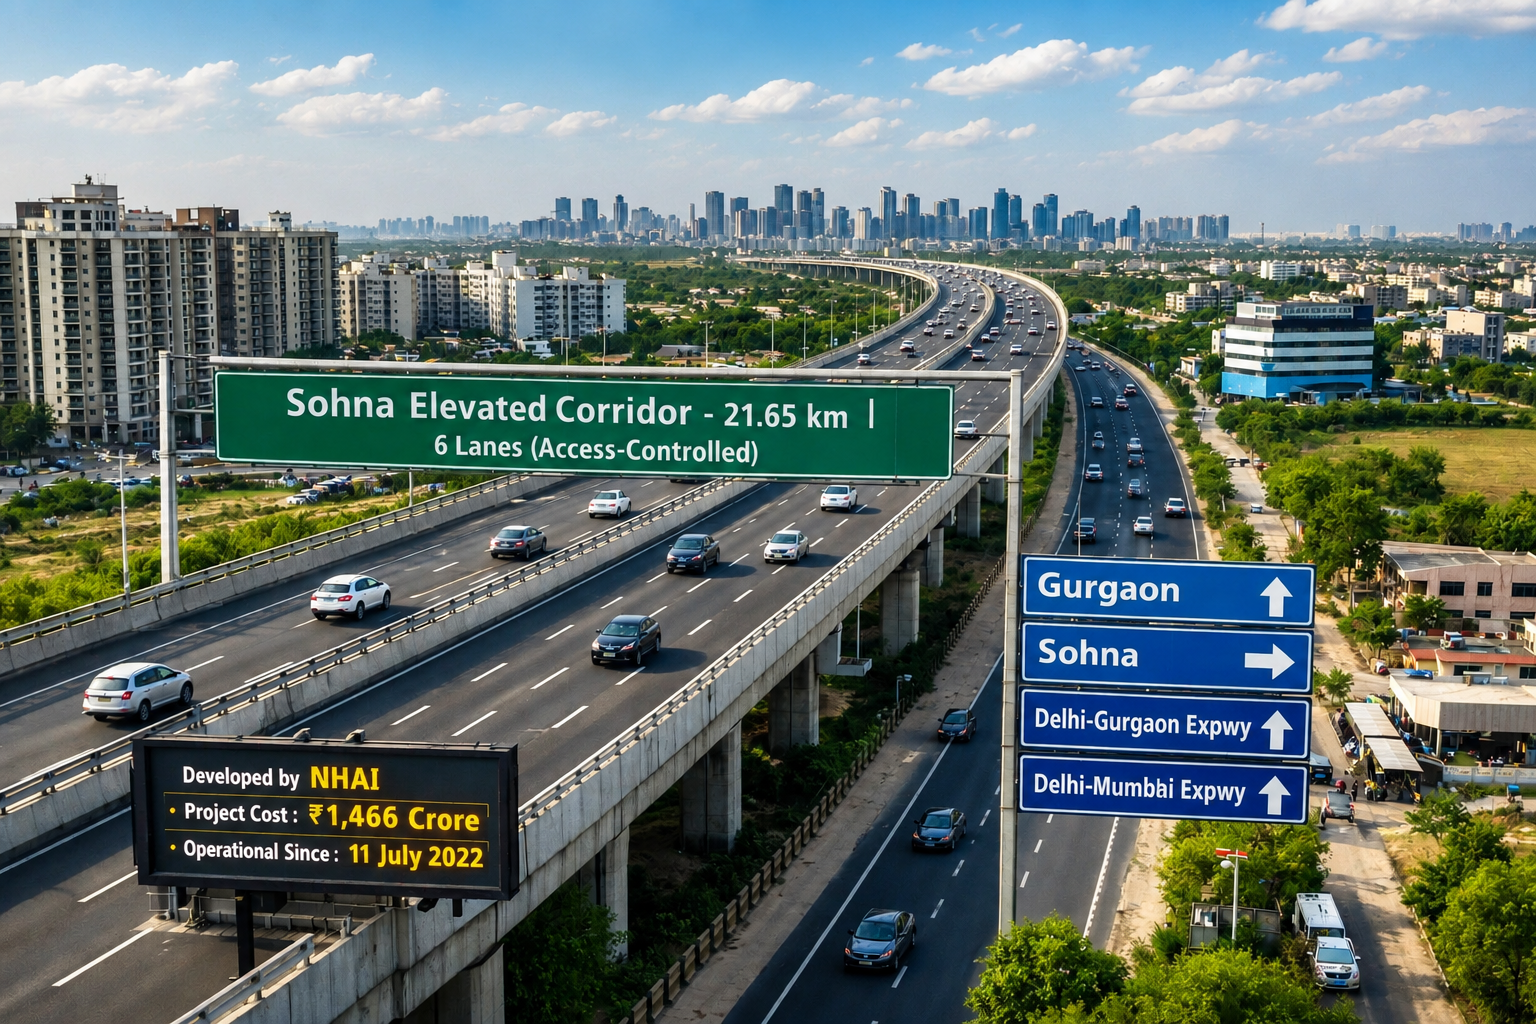
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
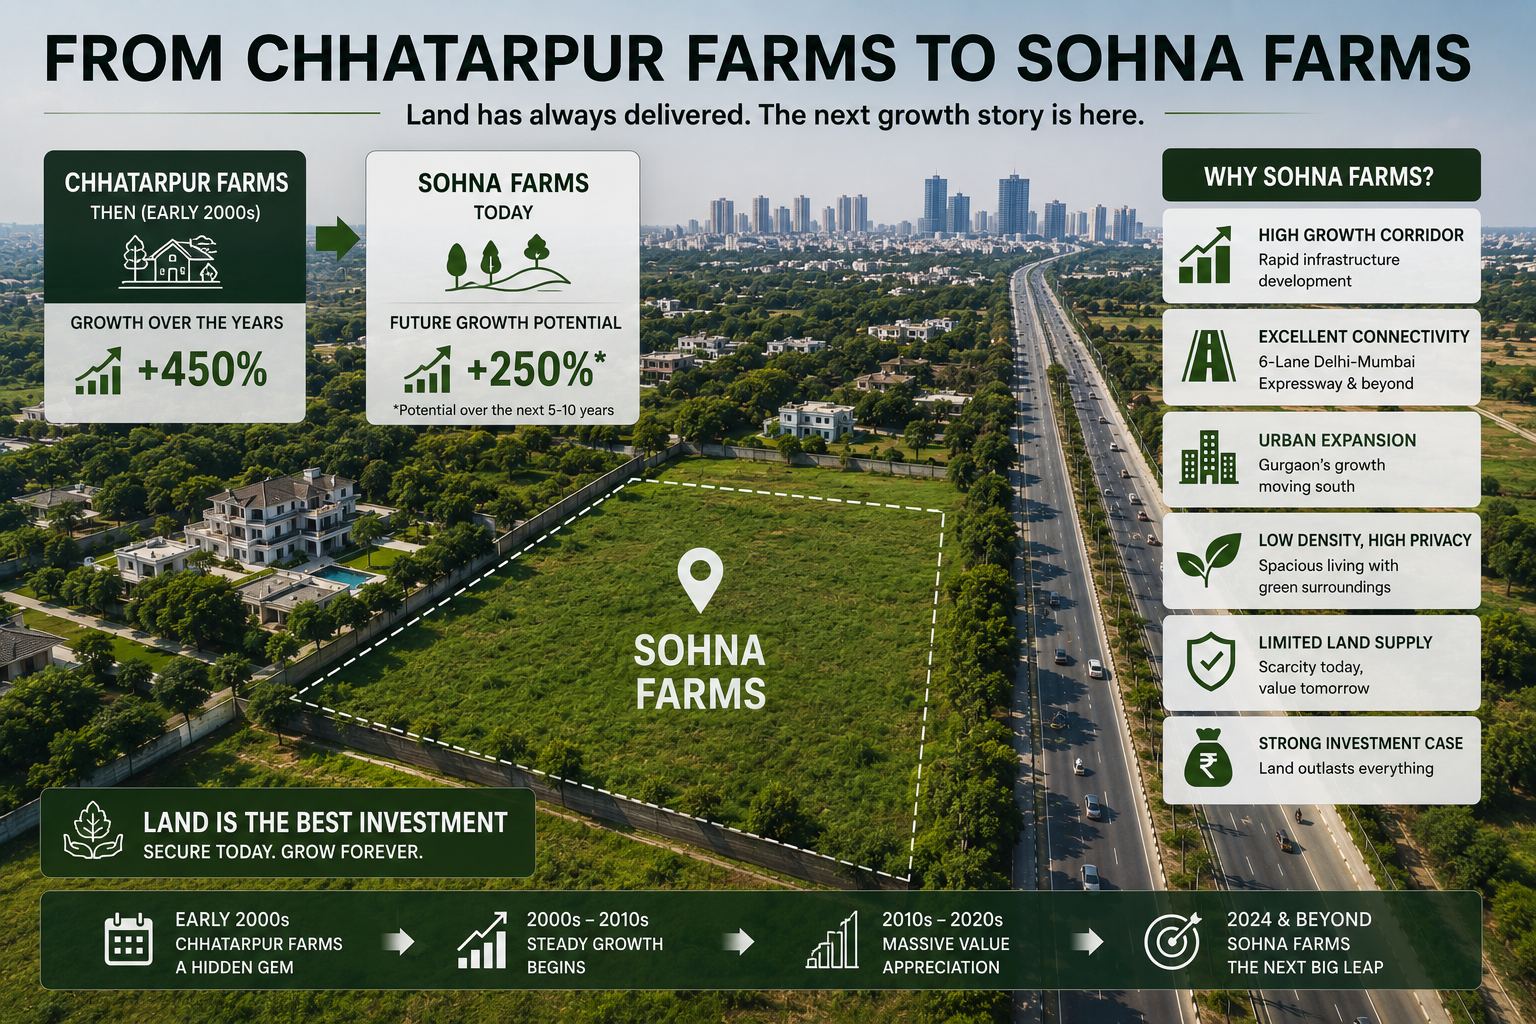
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
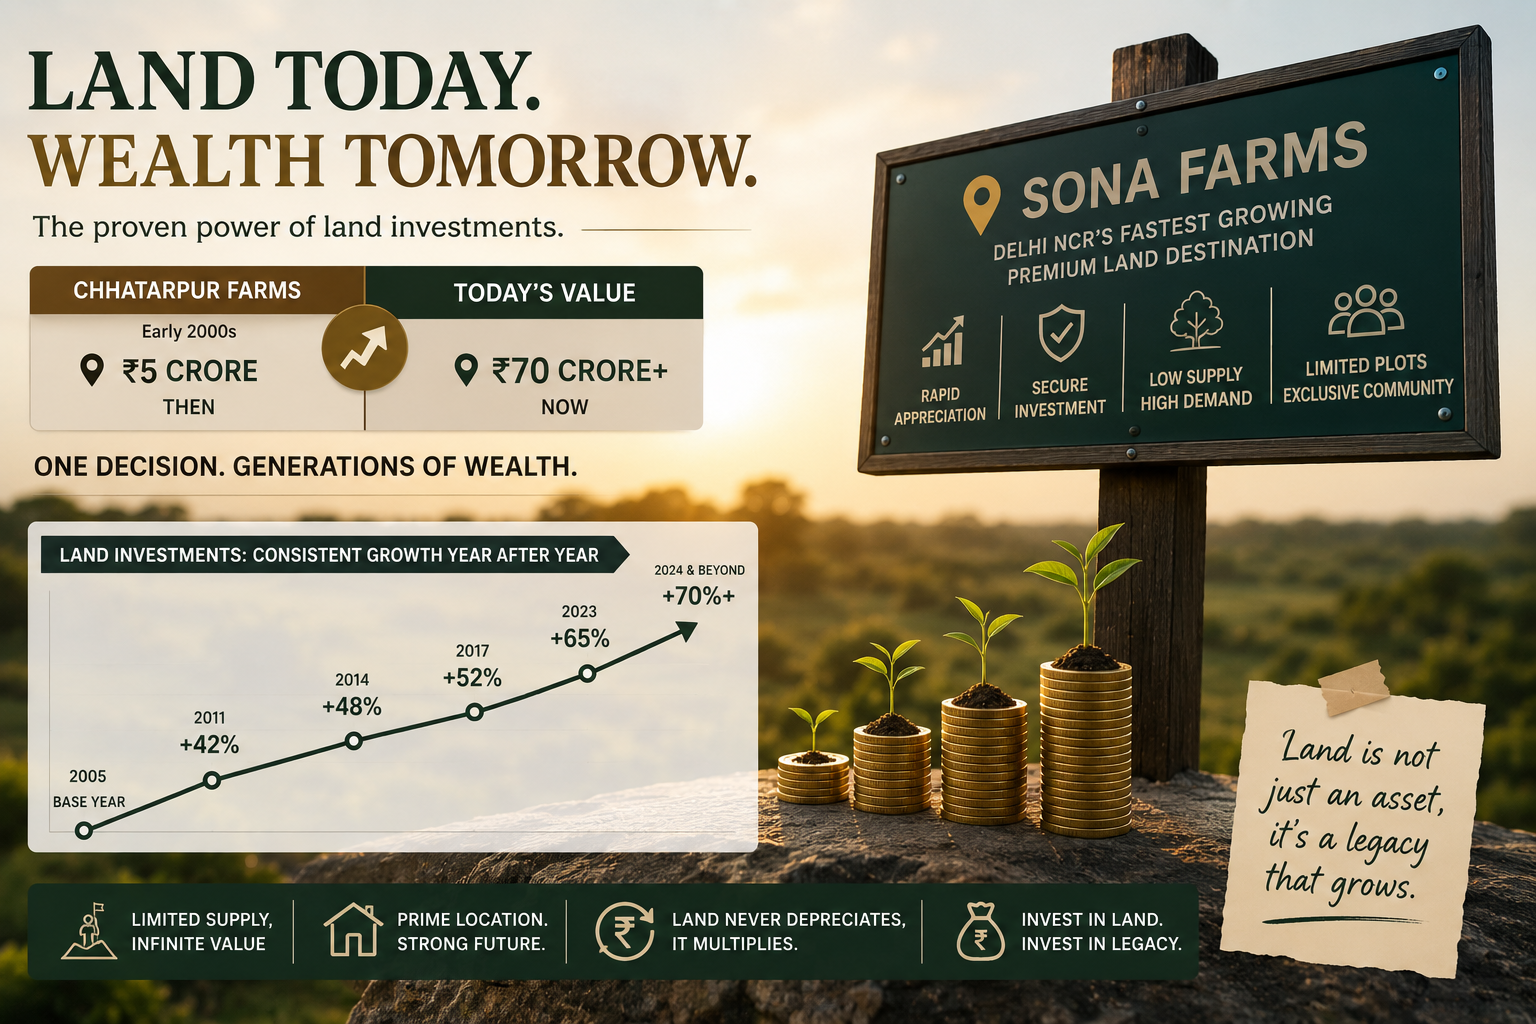
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.