The Doorstep Exchange: How Britain’s Reverse-Logistics Startups Are Capitalising on the End of Free Returns
As high street heavyweights and pure-play e-commerce platforms impose punitive charges on returned parcels, a cohort of domestic logistics upstarts is turning retail’s costliest headache into an enterprise software play.

Inside an unadorned industrial estate in Bermondsey, couriers arrive not with outbound parcels for dispatch, but with hampers of unworn knitwear, ill-fitting trousers, and redundant footwear collected from nearby postcodes within the previous ninety minutes. This reverse flow of merchandise represents the acute battleground of British digital trade. When ASOS, Next, and Boohoo quietly dismantled the decade-long convention of unpenalised postal returns by introducing deductions ranging between £1.50 and £2.00 per parcel, they fundamentally fractured consumer expectations. What traditional carriers view as an unprofitable administrative burden has suddenly become a viable market for venture-backed logistics startups focused entirely on consolidation.
The scale of the underlying liability is difficult to overstate. British consumers maintain one of the highest propensities for online apparel shopping in Western Europe, accompanied by a return rate that routinely hovers around thirty per cent across womenswear categories. For years, the attendant cost of processing, repacking, and re-listing stock was treated by marketing directors as an acceptable price for user acquisition. However, with cost of capital remaining elevated and gross margins under pressure across the London market, retailers can no longer afford to let tens of millions of pounds in inventory languish in postal transit for upwards of a fortnight.
Squeezing Margin from the Wardrobe Floor
The emergent generation of logistics startups does not intend to challenge Royal Mail or Evri on nationwide trunking routes. Instead, these operators concentrate their technology on the first and last mile, deploying label-free doorstep collections and establishing micro-consolidation depots in urban centres. By aggregating returns from multiple retailers—allowing a customer to surrender an ASOS parcel, a Next coat, and a pair of Marks & Spencer shoes in a single handover without printing a single barcode—these firms compress collection expenses while accelerating the speed at which items can be authenticated and routed back into merchant warehouses.
Every extra day a piece of seasonal clothing spends in the postal network directly erodes its terminal resale value, especially ahead of quarterly clearance periods. An item returned within twenty-four hours can typically be resold at full price; an item returned after twelve days frequently requires a markdown of twenty to forty per cent. Venture capital, previously burnt by the lavish cash burn of rapid-delivery grocery networks, has begun shifting capital toward these reverse-logistics providers precisely because their unit economics hinge on enterprise contracts rather than consumer subsidies.
Repurposing the Ruins of Quick Commerce
The historical failure of British e-commerce was treating transportation as a frictionless illusion rather than an expensive, resource-intensive transaction.
Intriguingly, the physical infrastructure supporting this pivot frequently borrows from the contraction of the rapid grocery boom. Where platforms such as Deliveroo, Just Eat, and various shuttered dark-store operators previously competed for rapid impulse orders, vacant light-industrial real estate across major British cities is being repurposed into sorting hubs. Some early-stage firms are already pitching their networks to supermarkets like Sainsbury's and Tesco, exploring whether grocery delivery vans on return journeys from residential streets might be utilised to hoover up apparel returns, thereby monetising dead capacity in the domestic supply chain.
Yet significant structural barriers remain. The business model depends upon sustained volume and deep technological integration with legacy enterprise resource planning systems used by older British retailers. If an upstart’s software cannot immediately trigger a customer refund the moment a driver scans a parcel at the doorstep, the consumer proposition collapses. Moreover, if high street operators decide that bringing shoppers into physical stores via click-and-collect counters remains their most effective lever for footfall and incremental sales, purely digital collection startups may find their addressable customer base confined to affluent metropolitan suburbs.
For founders operating in Shoreditch and Manchester, the coming financial year will determine whether returns management is an enduring enterprise category or merely an ephemeral operational niche. The era of subsidised convenience in British retail has definitively concluded; the companies capable of extracting liquidity from consumer indecision, however, are finding that frugality pays its own dividends.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
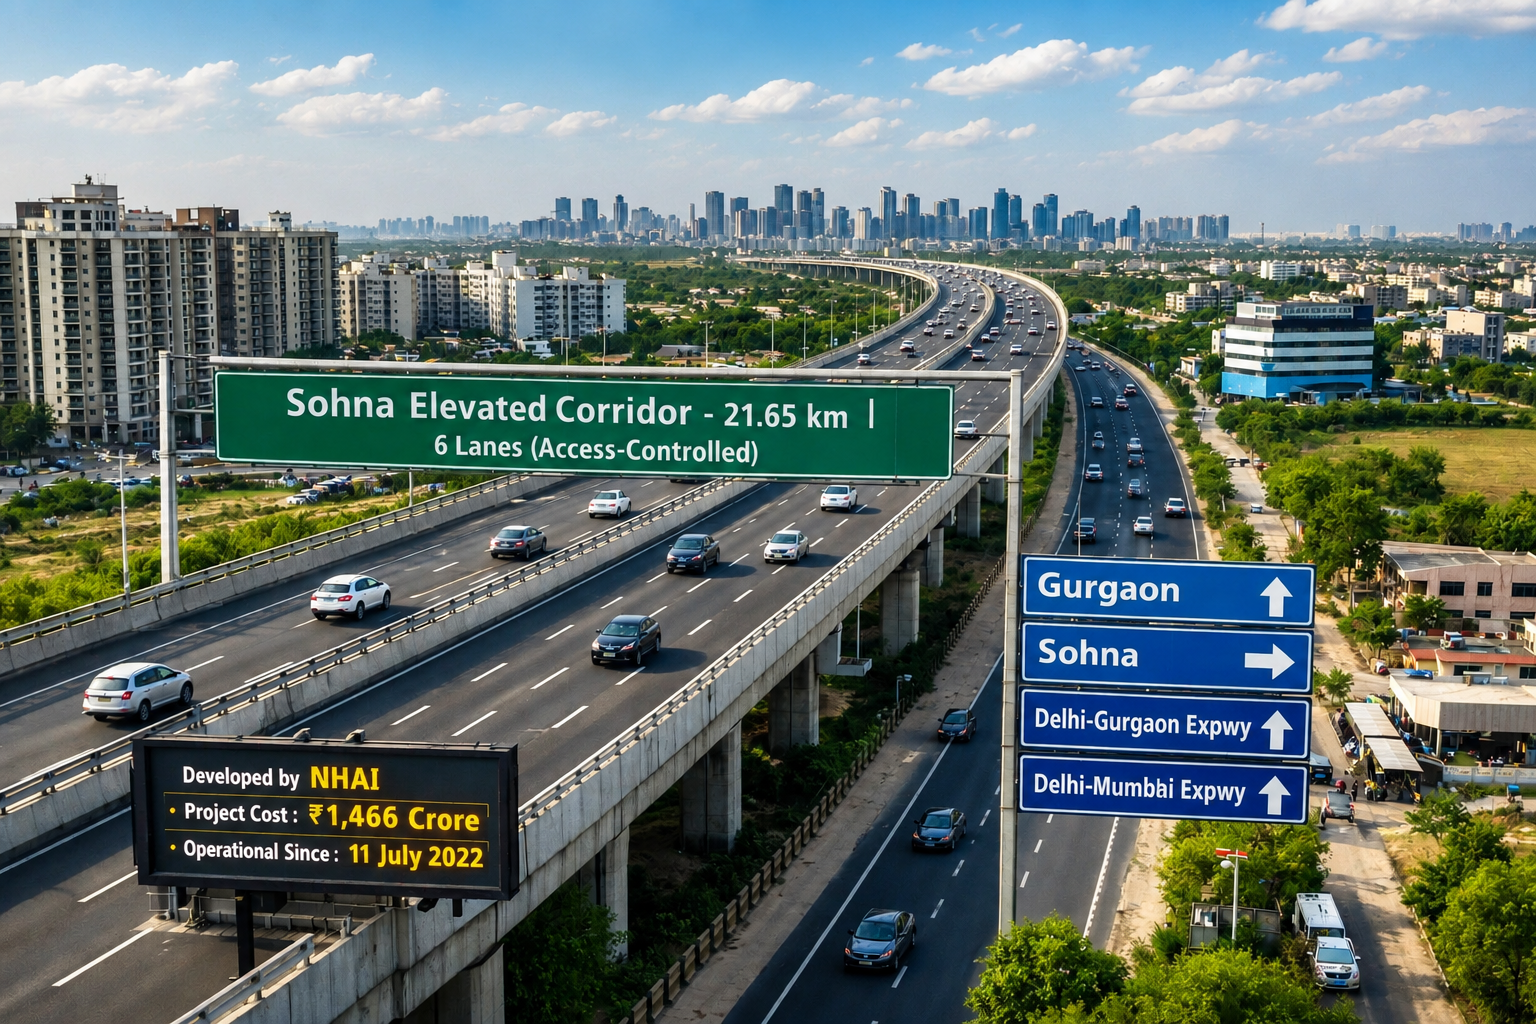
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
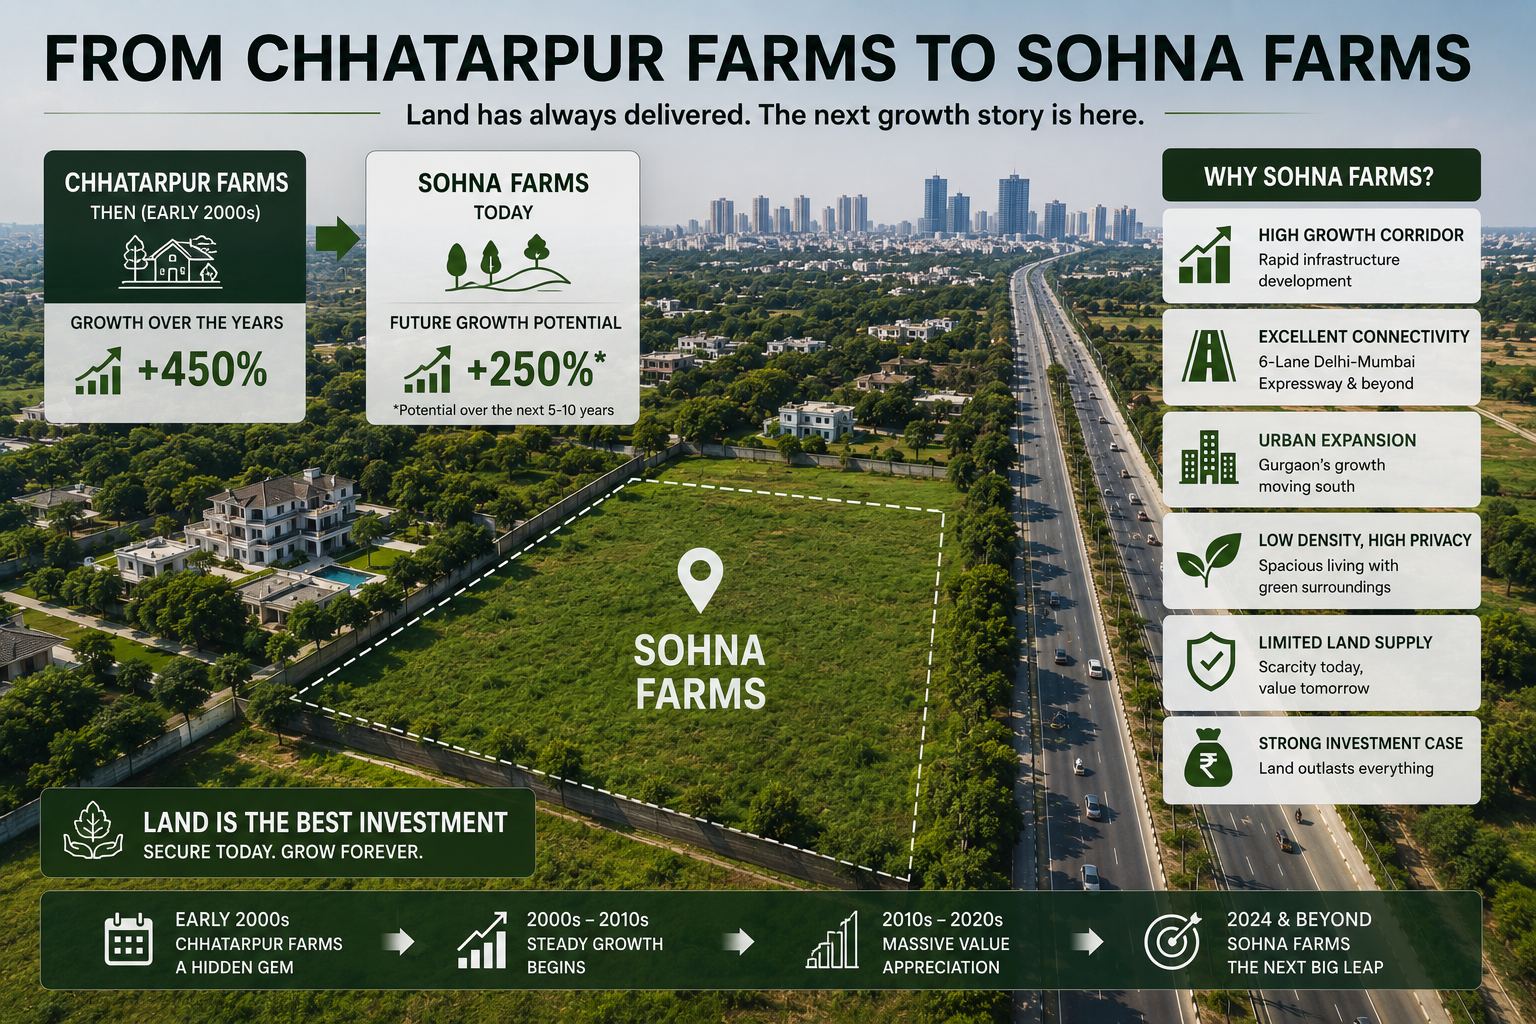
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
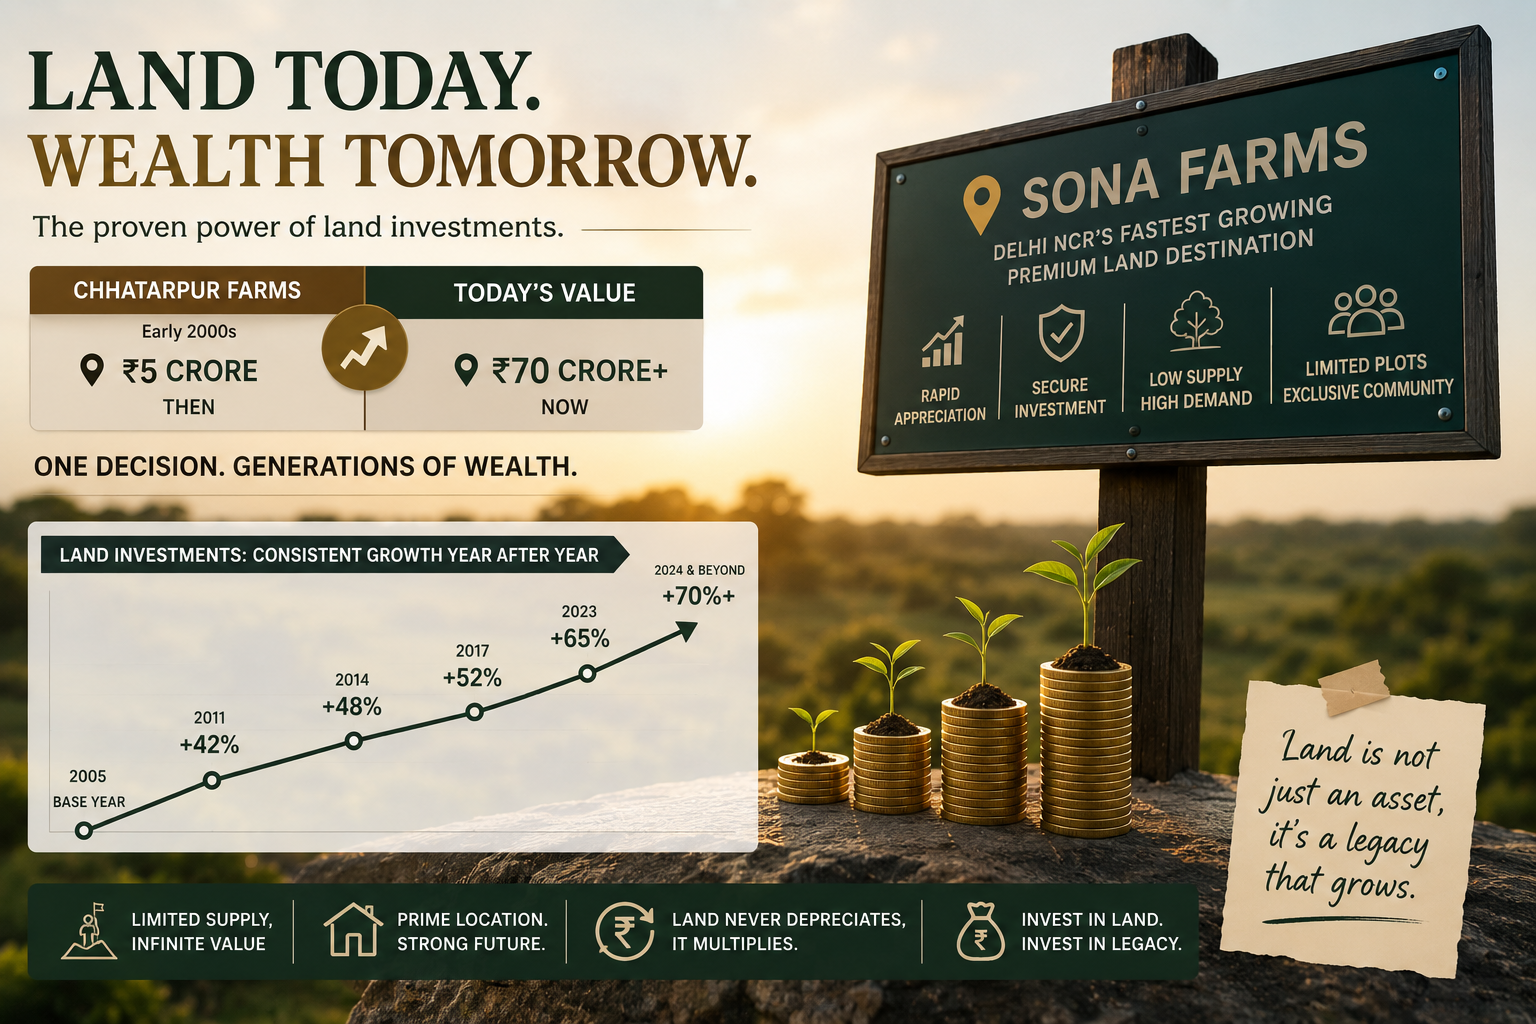
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.