The Doorstep Retreat: British Retailers Recalculate the Cost of the Final Mile
Confronted by escalating courier overheads and stubbornly high return volumes, the United Kingdom's leading merchants are dismantling the era of subsidised home delivery.

Across suburban distribution hubs outside Northampton and Milton Keynes, fleet dispatchers are managing a quiet restructuring of domestic freight. Where delivery vans once departed logistics yards dedicated almost exclusively to individual residential addresses, an increasing proportion of manifest volume is now directed toward forecourts, railway stations, and neighbourhood collection counters. The economic assumptions that sustained free, unconditional doorstep delivery across the British retail sector have fractured under cumulative pressures: driver wage adjustments, fuel volatility, and municipal clean-air charges.
The strategic recalculation is particularly pronounced among Britain's apparel merchants. When Next broke long-standing industry precedent by introducing fees on courier returns, rivals initially hesitated. Today, ASOS and Marks & Spencer have similarly tightened policies, penalising serial returners and imposing modest surcharges on standard collections. Processing an individual returned garment can incur upwards of £3 to £6 in direct inspection, restocking, and reverse-haulage costs. In an operating climate shaped by sluggish consumer discretionary spending, absorbing those outlays on low-margin items has become untenable.
The Economics of Out-of-Home Consolidation
Consequently, logistics capital is moving decisively into out-of-home delivery networks. Automated locker terminals and parcel collection counters situated in convenience stores are no longer treated as peripheral options for rural drop-offs; they represent the most viable operational hedge against urban margin dilution. Consolidating dozens of orders into a single modular locker bank outside a local supermarket eliminates the costly friction of missed residential deliveries on narrow, congestion-prone terraced streets. Retailers are actively encouraging the behavioural shift, offering reduced dispatch fees for shoppers willing to complete the final five hundred metres on foot.
Grocery operators face an adjacent challenge, balancing capital allocation between dedicated warehouse automation and existing high-street footprints. Ocado continues to pursue heavy automation through centralised customer fulfilment centres, relying on proprietary software to optimise drop densities across vast metropolitan catchments. By contrast, Tesco and Sainsbury's have increasingly deployed in-store picking and local micro-fulfilment hubs carved out of surplus backroom floor space. This spatial proximity allows the traditional grocers to compress the final haul while collaborating with on-demand delivery platforms like Deliveroo and Just Eat to defend high-margin convenience trade.
Fleet Decarbonisation and the Urban Squeeze
Suburban doorstep drop-offs were built on venture-backed delivery subsidies; the present era demands that physical density pays for itself.
Municipal policy is accelerating the transition away from ad-hoc residential visits. The expansion of London's Ultra Low Emission Zone and parallel clean-air frameworks across Birmingham, Bristol, and Manchester have forced freight carriers to accelerate capital expenditure on electric commercial vehicles. While battery-electric vans reduce tailpipe charges, their range profiles and elevated purchase prices demand higher asset utilisation. Operators can ill afford vans idling at the kerb while a courier waits for a domestic doorbell to be answered.
British shoppers, who historically embraced online shopping faster than their continental counterparts, are adapting to a more regimented delivery framework. The expectation of unlimited next-day doorstep service at negligible cost is being steadily dismantled. In its place, the United Kingdom's logistics map is hardening around consolidated pick-up points, tiered delivery pricing, and an insistence that convenience must be paid for at point of sale.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
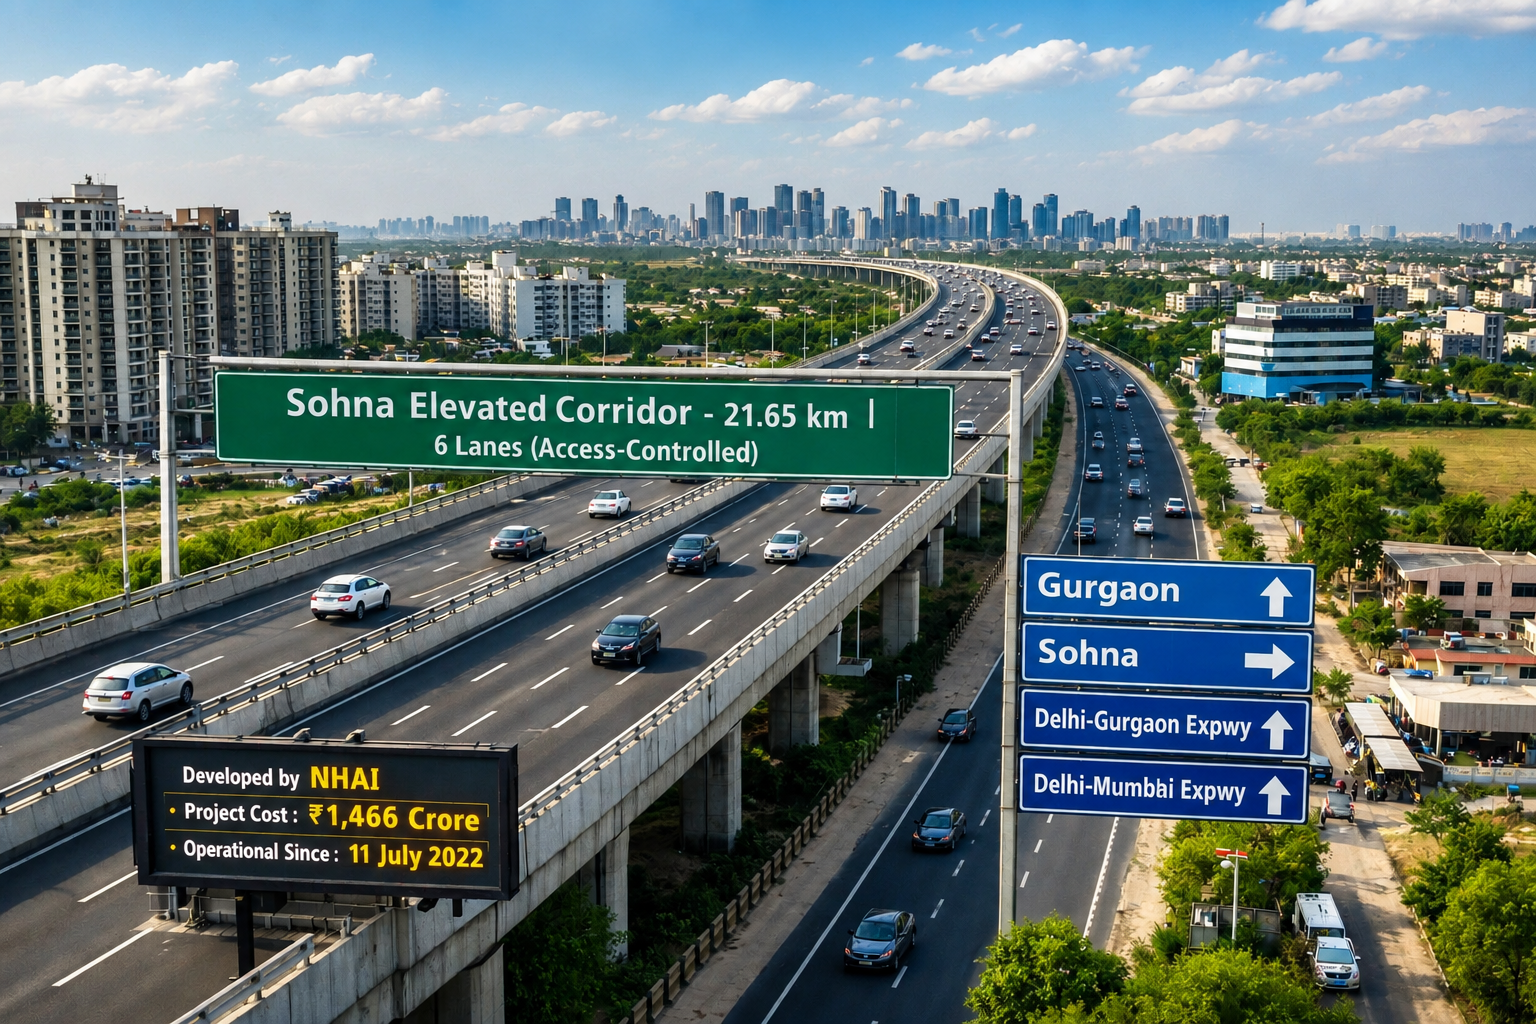
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
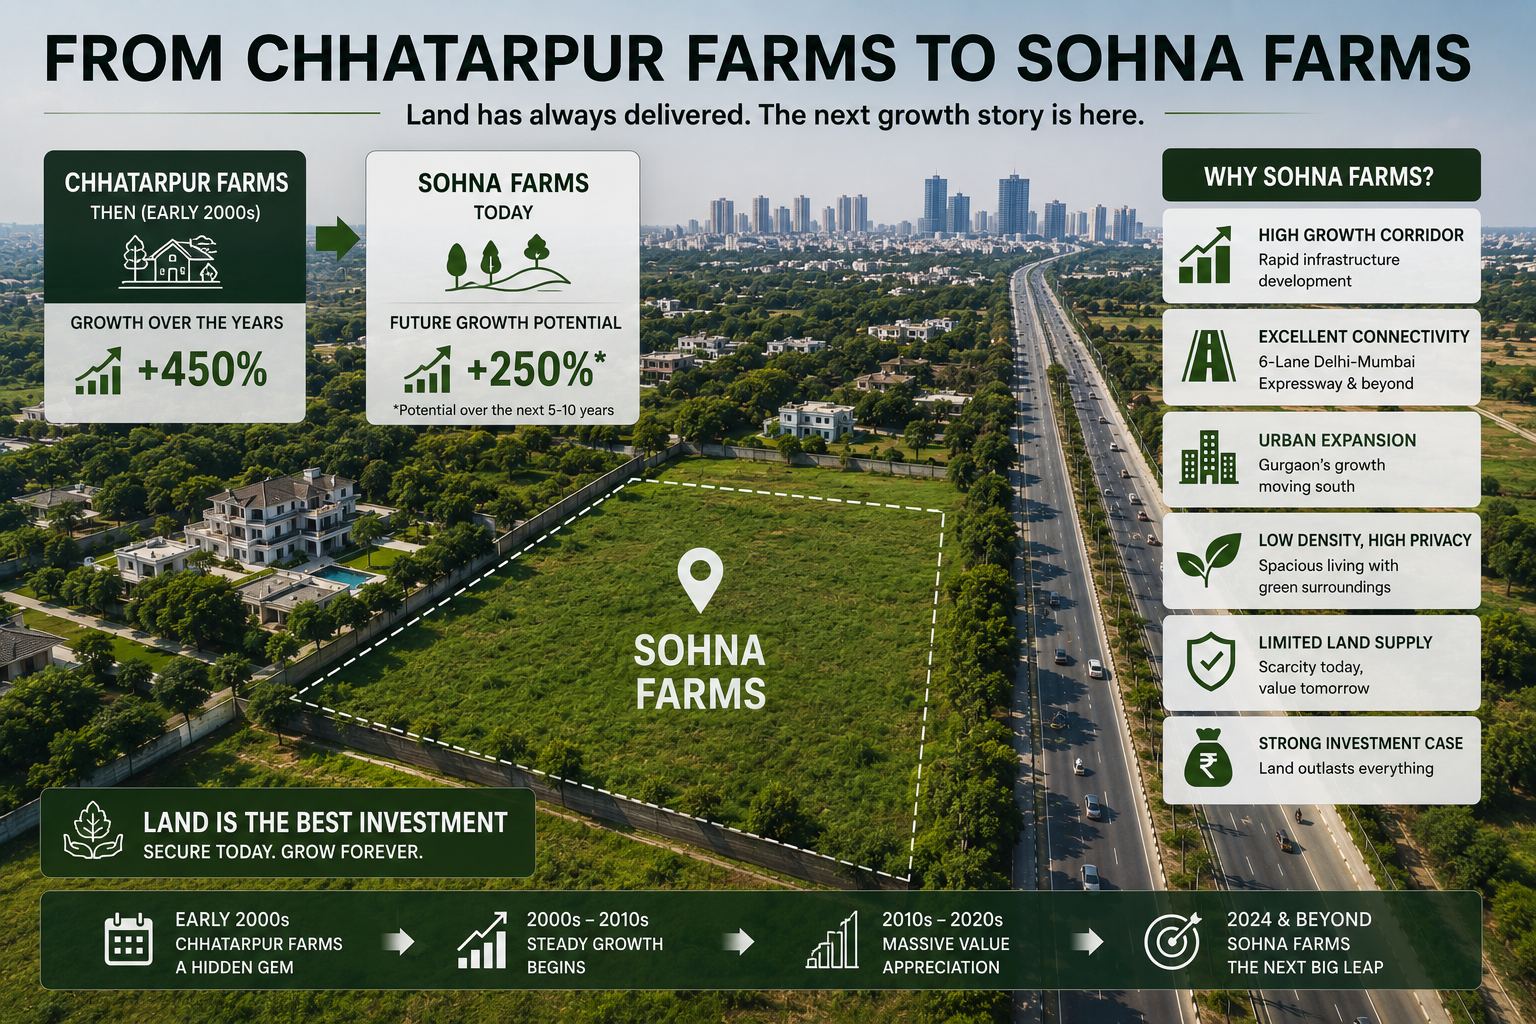
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
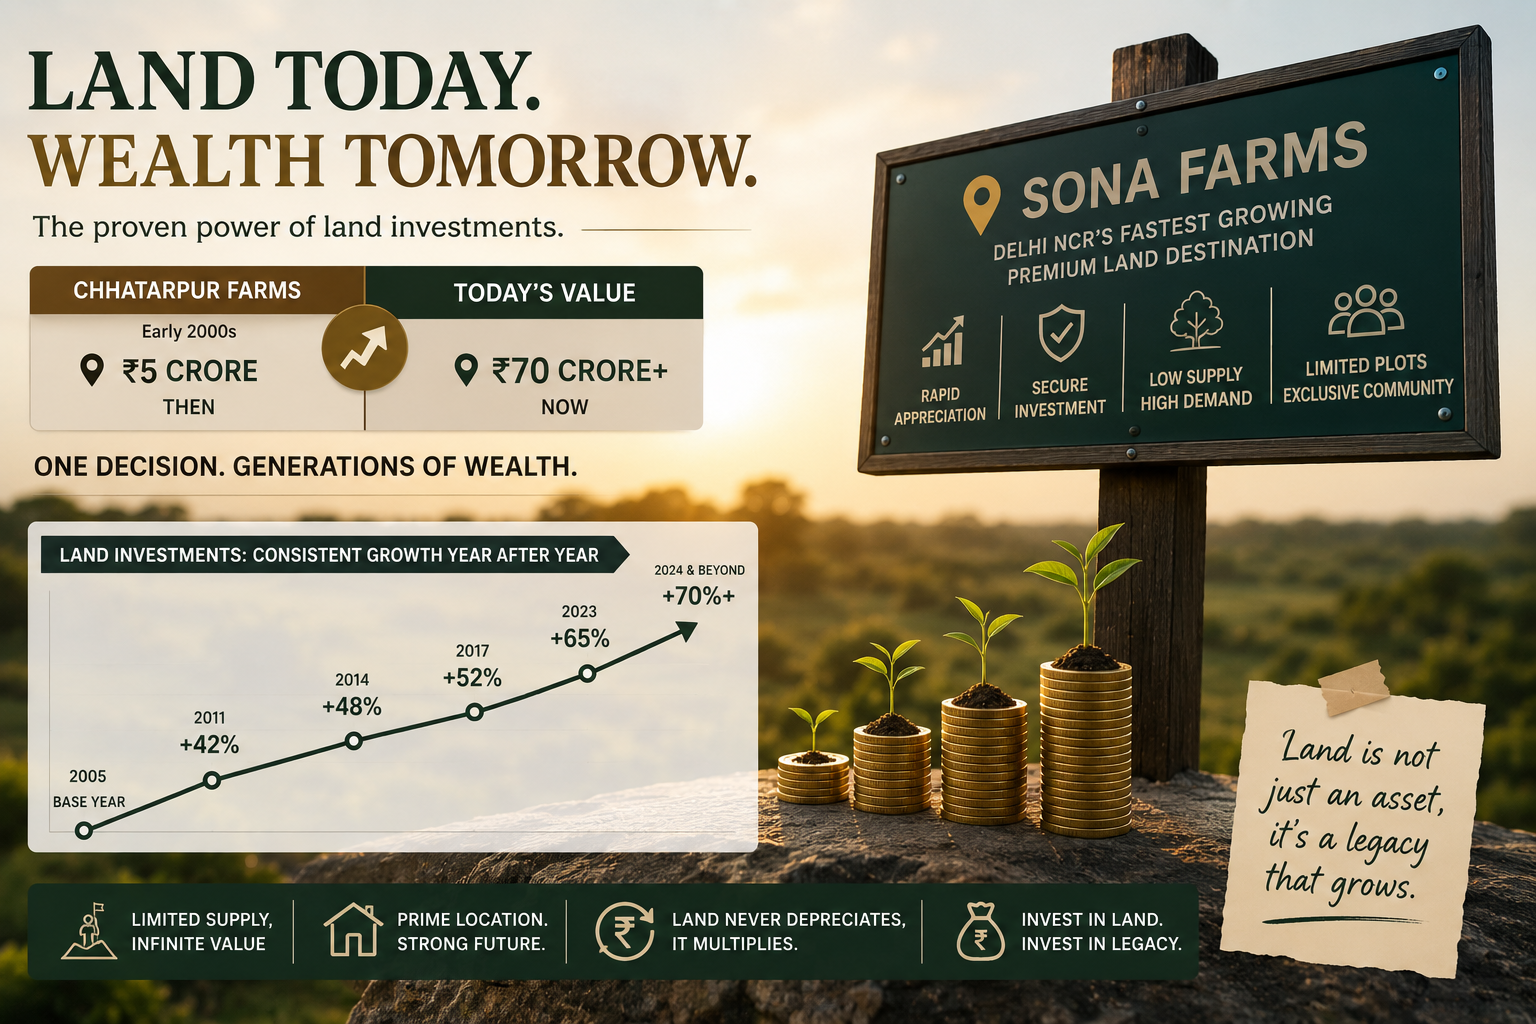
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.