The Ghost Fleet Departs: How British Retail Tech Shifted from Dark Stores to Returns Management
Having burned through venture subsidies on 15-minute grocery runs, the UK's early-stage commerce sector is pivoting toward the costly, unglamorous plumbing of high-street reverse logistics.

Across former railway arches in Bermondsey and nondescript industrial units behind Battersea, the roller shutters that once sheltered moped fleets for rapid-grocery ventures now sit mostly silent. Three years after venture capital poured hundreds of millions of pounds into promises of fifteen-minute milk and bread deliveries, the British commerce startup landscape has enacted a decisive, unglamorous retreat. The collapse or consolidation of early pandemic pioneers has given way to an entirely different enterprise cohort: software engineers building back-end plumbing for the country's most entrenched high-street names.
This shift marks a structural realignment rather than a temporary retreat. With interest rates hovering around five per cent, early-stage investors have abandoned consumer-facing aggregators that burn cash on rider subsidies and rider acquisition. Instead, seed and Series A funding across London, Manchester and Bristol is consolidating around reverse logistics, micro-inventory optimisation, and returns automation—areas where legacy giants such as Marks & Spencer, Next, and Tesco are willing to sign commercial multi-year contracts to protect their operating margins.
The Margin Bleed of the Spare-Room Wardrobe
Nowhere is this imperative clearer than in apparel, where online return rates have stubbornly lingered between 25 and 30 per cent of total orders. The habit of bracket-buying—ordering three sizes of the same garment with the deliberate intent of returning two—has evolved from a harmless consumer quirk into a balance-sheet crisis. When ASOS, Boohoo, and Zara introduced nominal return fees of £1.99 to £3.95 over the past two years, they signalled an end to frictionless post-purchase generosity. Yet charging the consumer covers only a fraction of the physical handling, re-bagging, and markdown costs incurred when stock sits trapped in transit for weeks.
The era of subsidising consumer convenience has collapsed into an urgent hunt for recovered margin behind the corporate firewall.
A fresh crop of British enterprise startups has stepped into this breach. Rather than operating vans or taking inventory risk, these firms build algorithmic routing engines that determine where a returned parcel should go before it ever reaches a central depot. If a tailored coat returned in Leeds is out of stock in a nearby Marks & Spencer branch, the software routes it directly to local store inventory rather than sending it on a 200-mile round trip to an East Midlands fulfilment centre. By shaving days off the re-listing cycle, retailers salvage full-price sales that would otherwise decay into clearance racks.
Platform Co-optation and Corporate Prudence
The competitive dynamic has also changed because the incumbent retailers are no longer asleep at the wheel. Next's Total Platform—which handles logistics, digital operations, and credit for third-party brands—has proven that legacy distribution scale can be monetised as a software service. Meanwhile, Ocado's technology division continues to license its automated grid systems to global supermarket chains, demonstrating that the ultimate prize in British retail technology is proprietary infrastructure rather than delivery intermediation.
Consequently, modern retail founders in the UK are building modular tools designed to integrate with established warehouse networks rather than displace them. Deliveroo and Just Eat continue to fight for high-margin grocery partnerships with Sainsbury's and Waitrose, but their scope remains confined to immediate convenience baskets. The deeper operational challenge—reconciling fragmented stock files, managing peak-demand parcel surcharges, and cutting cross-docking labour costs—belongs to the quiet B2B platforms operating out of Shoreditch and Edinburgh.
For the British retail sector, this represents a welcome return to economic discipline. The extravagant experiments that attempted to construct parallel logistics networks have yielded to pragmatism: the winning startups of this cycle will not be household names on consumer smartphones, but lines of code embedded deep within the enterprise resource systems of Britain's largest retail boardrooms.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
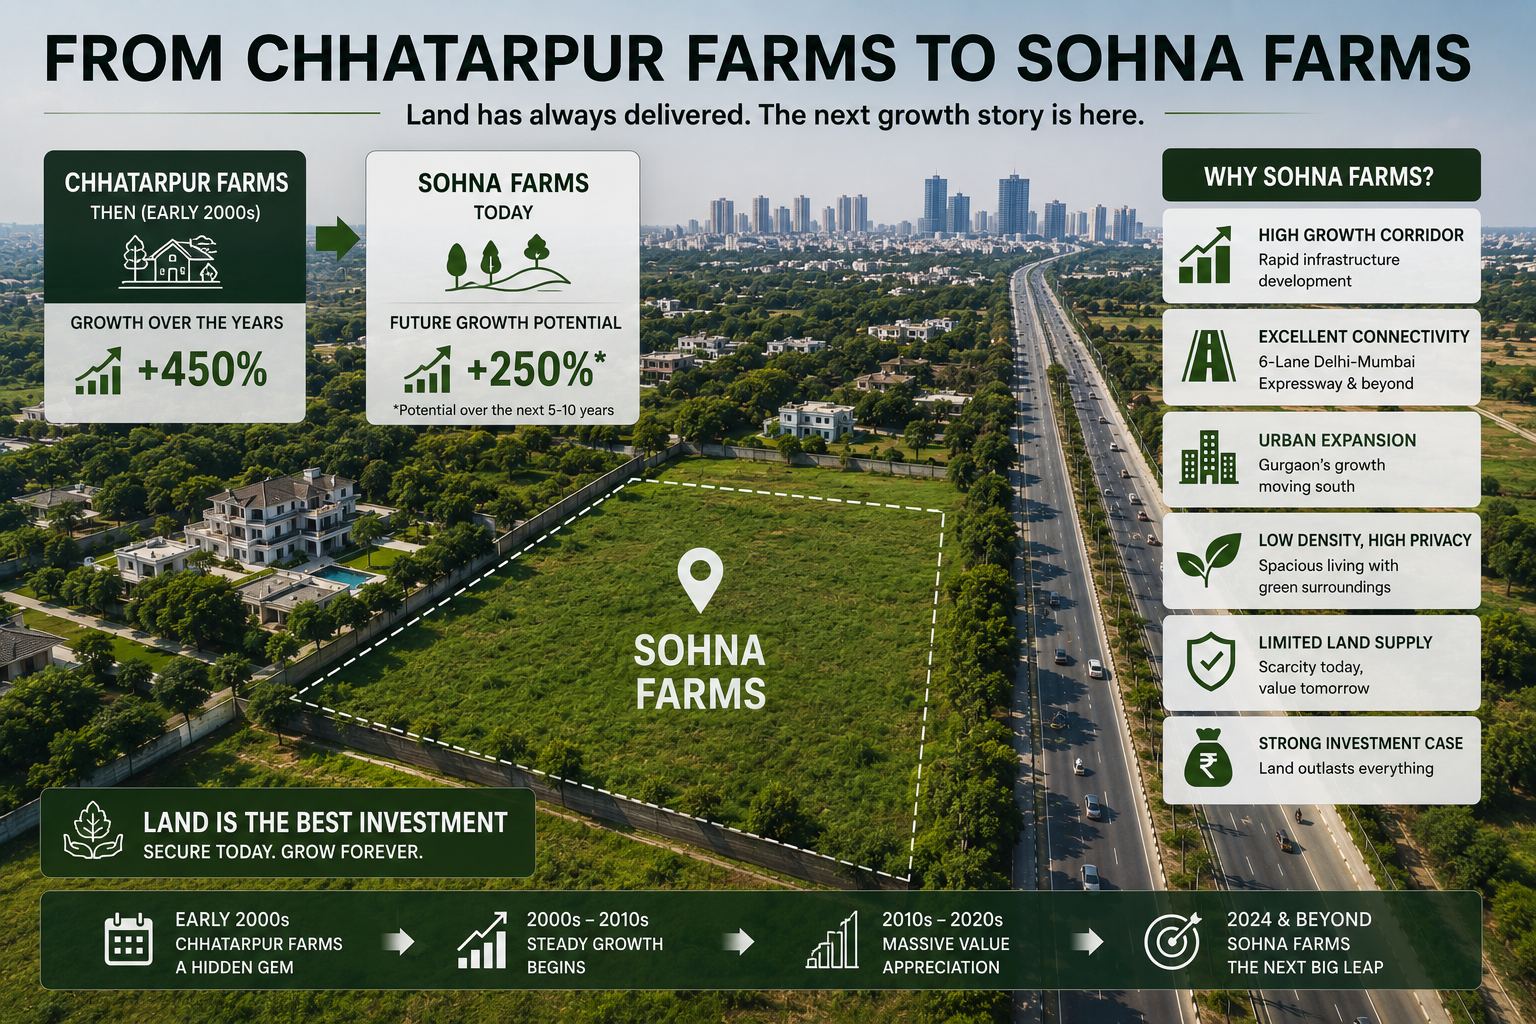
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
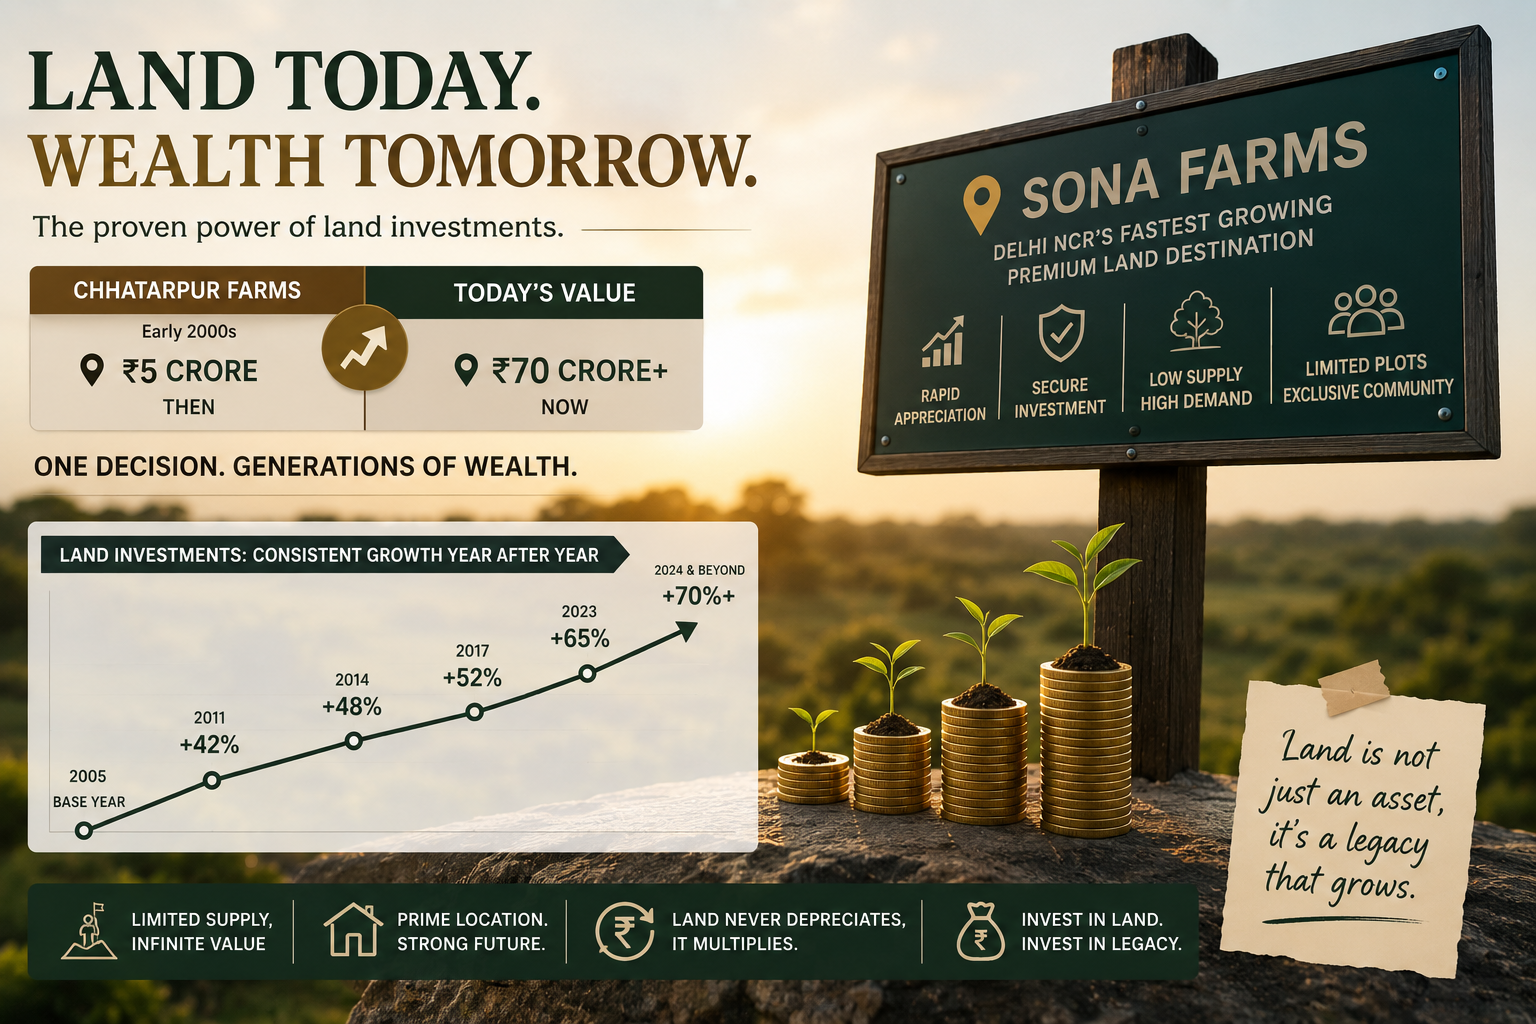
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.