The High Street’s Creator Conundrum: Inside the Race to Commercialise Britain’s Digital Storefronts
As rising customer acquisition costs corrode digital balance sheets, established British retailers are scrambling to turn social broadcasters into direct sales infrastructure.

Inside Marks & Spencer’s digital innovation unit, the metric commanding executive attention is no longer raw click-through rate, but the conversion velocity of individual staff recommendations broadcast over vertical video. What began five years ago as an experimental exercise in colleague advocacy has quietly matured into a commercial countermeasure. British apparel and grocery merchants, having weathered double-digit increases in Meta and Google ad rates, are confronting a fundamental migration: shoppers are no longer browsing digital storefronts directly, but purchasing items routed through individual creators on platforms whose checkouts never touch a high street domain.
The implications for the domestic retail sector are profound. For two decades, British e-commerce relied on predictable search engine real estate and coupon affiliates to drive traffic toward centralised web shops. Today, that architecture is decaying. With fashion pure-plays such as ASOS and Boohoo navigating protracted operational restructurings, the balance of commercial leverage has tilted toward short-form video feeds where product discovery and transaction take place in a single swipe. For retail operators already managing compressed margins, adapting to this decentralised sales force is rapidly becoming an imperative rather than an experiment.
The Escalating Cost of Passive Discovery
The underlying driver of this transformation is arithmetic. Performance marketing in the United Kingdom has grown prohibitively expensive, with customer acquisition costs in apparel and beauty climbing steadily over the past twenty-four months. A conventional paid social campaign that once delivered an adequate return on ad spend now frequently operates near breakeven after factoring in packaging and delivery overheads. In contrast, creator commerce aligns incentives differently: retailers surrender an agreed commission—frequently between 8 and 15 per cent—only when an actual sale is logged.
When product discovery detaches permanently from the merchant destination, traditional retailers risk being downgraded to passive fulfillment utilities for social platforms.
This calculation has prompted divergent responses across the British high street. While Next continues to rely on its formidable Total Platform distribution ecosystem to absorb third-party brands, others are aggressively courting external influencers to defend market share. Grocers are not immune. Sainsbury's and Tesco have observed pantry goods, specialty sauces, and kitchen gadgets shift briskly through social platforms, prompting quick-commerce couriers like Deliveroo and Just Eat to experiment with creator-curated grocery bundles designed to capture spontaneous domestic orders.
Returns Friction and the Margin Squeeze
Yet the creator model introduces acute operational hazards, particularly in Britain’s notoriously return-heavy clothing sector. Impulsive purchases driven by live broadcasts often suffer from elevated return rates, which can exceed 30 per cent for fast-moving womenswear. For domestic operators, absorbing the reverse logistics on a £25 dress purchased via a third-party social link quickly erodes whatever margin the lower acquisition cost provided. Platform transaction fees, combined with courier surcharges from Royal Mail or Evri, mean that poor-quality sales can rapidly become cash-negative.
Furthermore, retaining ownership of the consumer relationship remains the central strategic dilemma. When an individual purchases an M&S cashmere jumper or an ASOS trench coat directly through an algorithmic feed, the platform—not the retailer—captures the first-party data and payment relationship. British retailers risk spending millions of pounds servicing orders where they have no direct mechanism to encourage repeat visits. Those that survive this shift intact will be the operators capable of using creator storefronts as top-of-funnel acquisition, while swiftly migrating buyers into proprietary loyalty schemes before the next broadcast begins.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
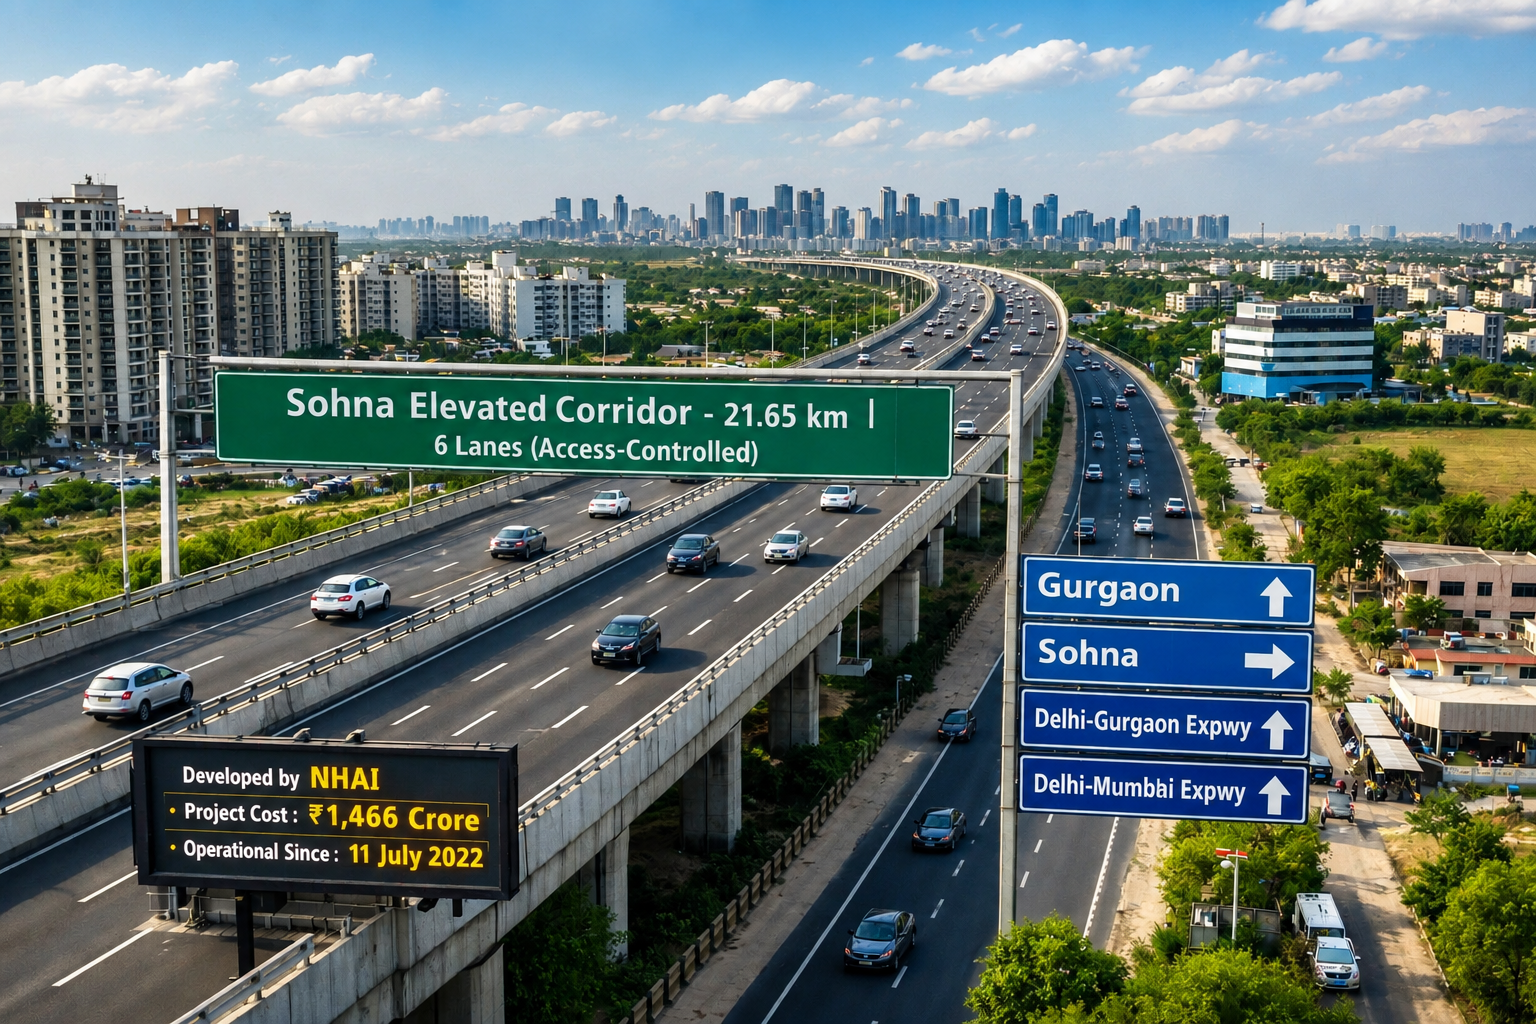
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
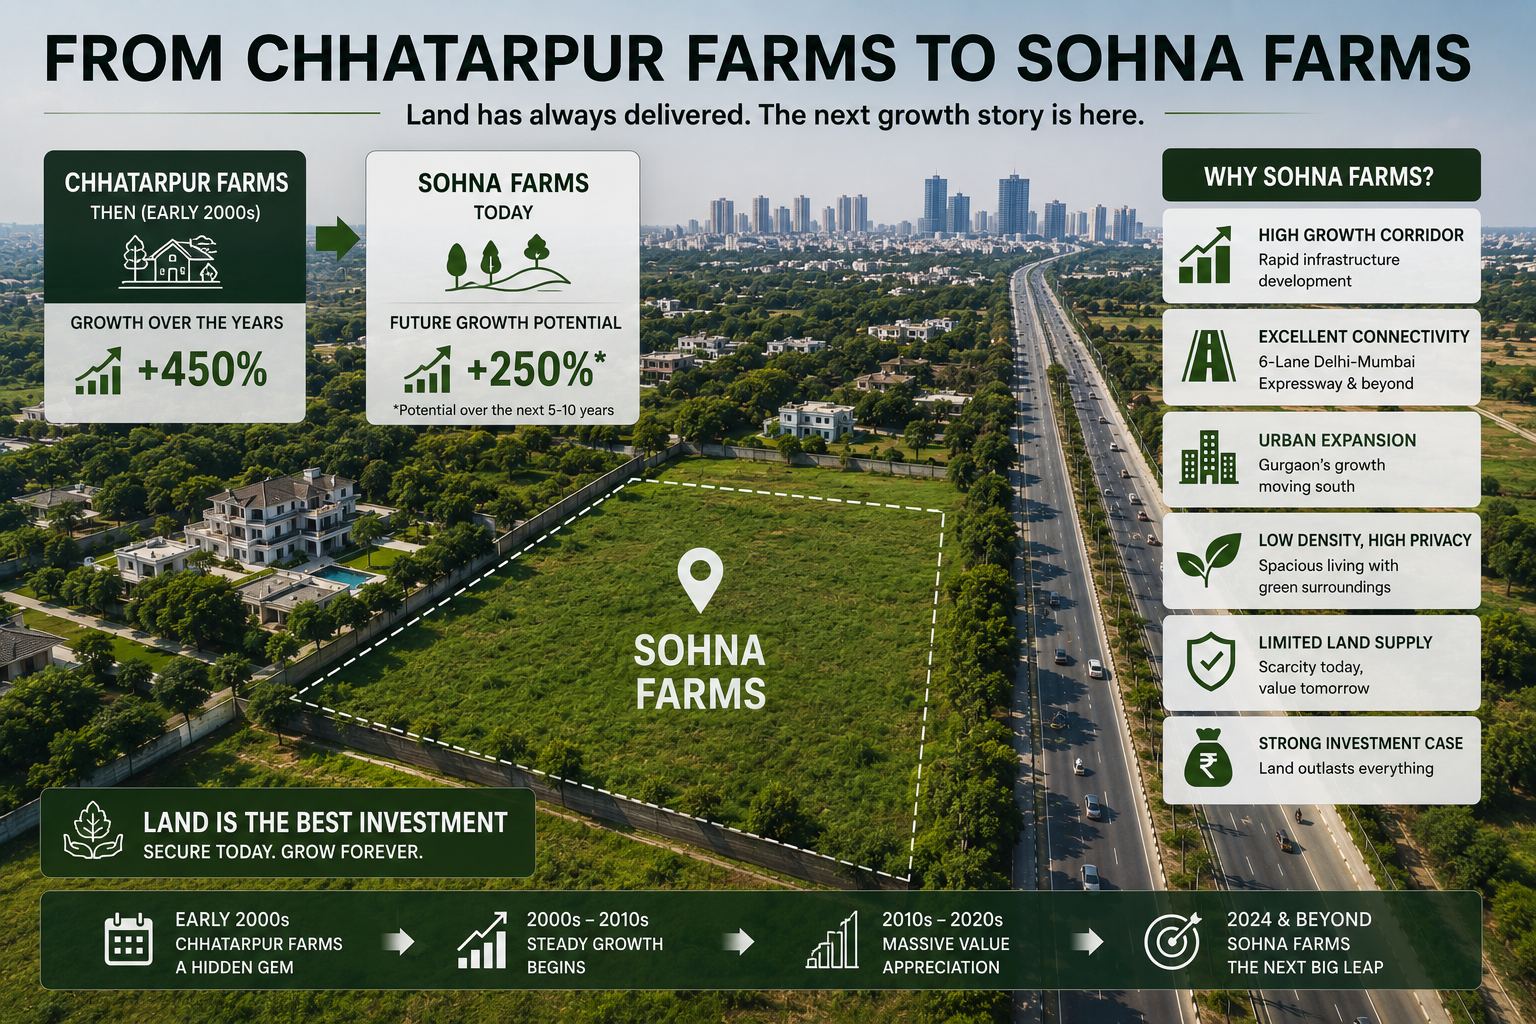
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
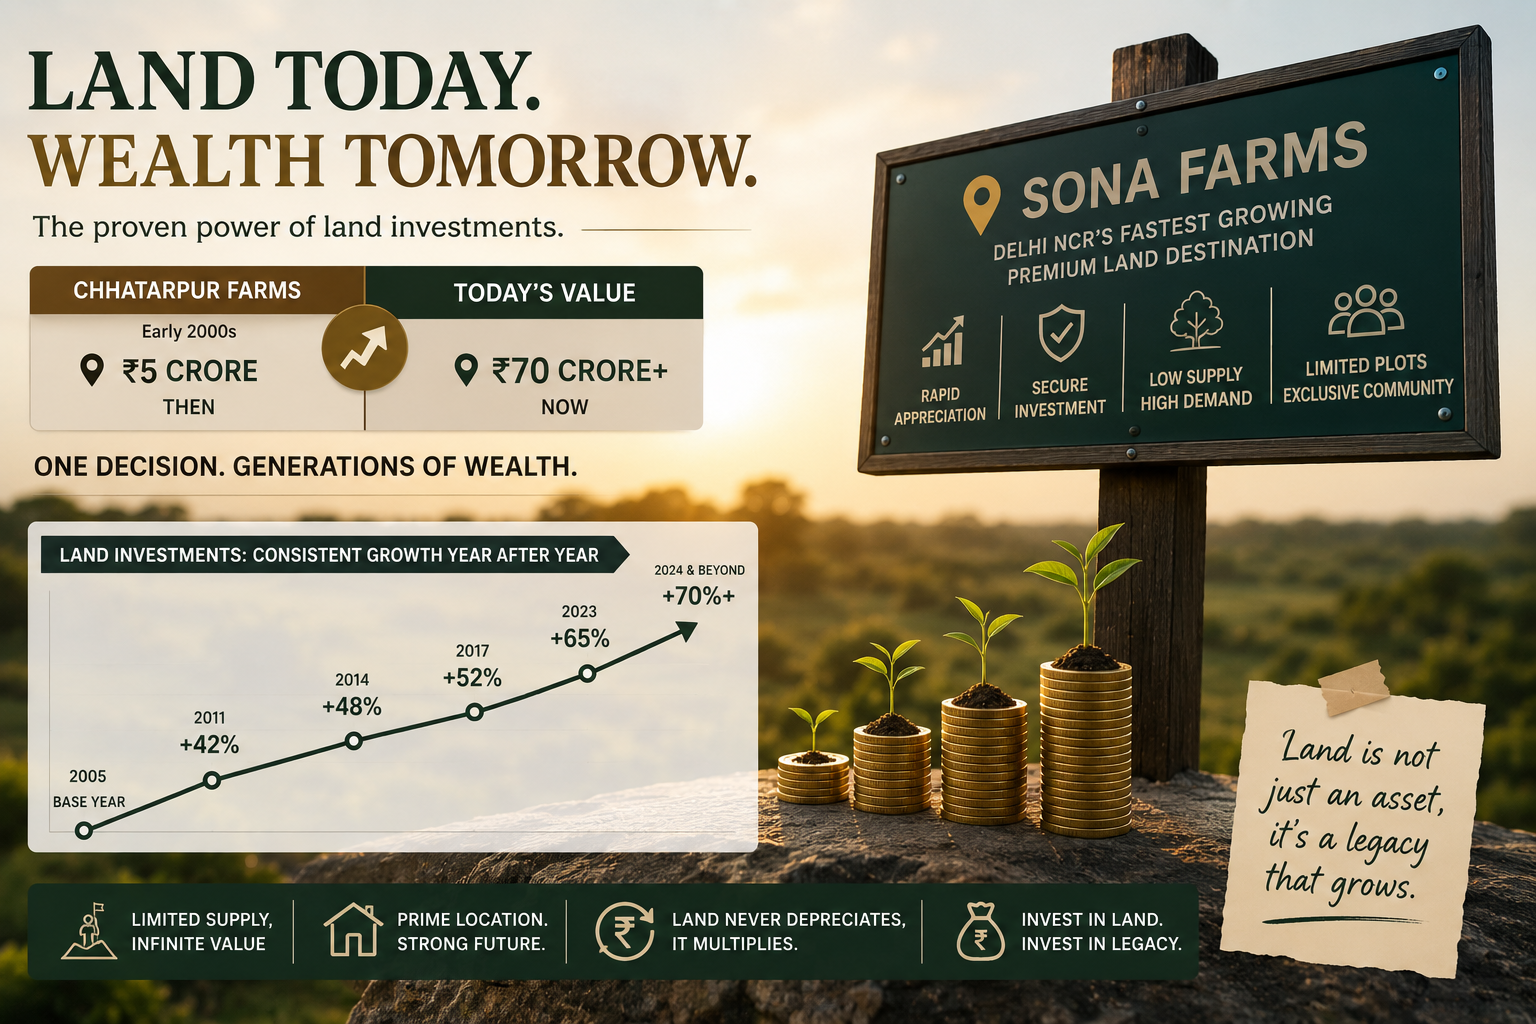
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.