The Last-Mile Gauntlet: European Grocers' Digital Shelf Ambition
European grocery retailers are navigating a complex digital transformation, with e-commerce profitability remaining an elusive prize. The continent's fragmented logistics and diverse consumer habits present a unique challenge to even the most established players.

Carrefour's recent strategic adjustments, including a renewed focus on its loyalty programme and a measured expansion of its e-commerce capabilities in its core markets, underscore a broader trend among European grocers. While the pandemic spurred an initial surge in online grocery adoption, the subsequent recalibration reveals a fundamental struggle: how to convert digital enthusiasm into sustainable, profitable operations across a continent defined by diverse regulatory landscapes and consumer preferences.
The initial land-grab for instant grocery, exemplified by the rapid rise and equally swift retrenchment of players like Gorillas and Flink, demonstrated a strong consumer appetite for convenience but highlighted the formidable unit economics of hyper-local delivery. Traditional retailers, including REWE and Lidl, observed these dynamics, cautiously investing in their own digital infrastructures rather than fully embracing venture capital-funded models that prioritised scale over immediate returns. This patient approach is now yielding dividends as the market consolidates.
The Legacy Burden Versus Agility
Established supermarket chains operate with vast physical footprints and entrenched supply chains, assets that are simultaneously their greatest strength and their most significant impediment to digital transformation. Re-engineering these systems for e-commerce, which often demands different warehouse configurations, picking strategies, and last-mile logistics, represents a substantial capital expenditure. Conversely, pure-play online grocers, unburdened by legacy infrastructure, can design their operations from the ground up for digital efficiency, yet they often lack the brand recognition and procurement scale of their traditional counterparts.
Consider the varied market responses: In France, the drive-through model remains prevalent, reflecting consumer preferences for click-and-collect and the existing automotive culture. Germany, conversely, saw a slower initial uptake of online grocery, perhaps due to a strong discount retail presence and a preference for in-store shopping. Italy and Spain are demonstrating accelerated growth from a lower base, with a focus on both express delivery and scheduled slots, often leveraging existing supermarket networks.
The path to profitability in European online grocery hinges less on innovation in consumer-facing applications and more on the meticulous optimisation of warehousing, order fulfilment, and last-mile delivery networks. This is an operational challenge at its core.
Cross-border expansion, a strategy pursued by general merchandise platforms like Zalando and Allegro, proves significantly more challenging for perishable goods. The varying cold chain requirements, food safety regulations, and consumer tastes from Poland to Portugal create formidable barriers. Even within single markets, urban density and rural sprawl necessitate different delivery models, from electric vans in city centres to third-party courier partnerships for less concentrated areas.
Technology as the Enabler, Not the Panacea
The critical differentiator lies in the integration of robust SaaS platforms that can orchestrate inventory management, route optimisation, and customer relationship management. Companies like Ocado provide a comprehensive suite of technologies, but their high capital cost can be prohibitive. Many European grocers are therefore pursuing modular solutions, integrating various providers for warehouse automation, last-mile routing algorithms, and demand forecasting. The goal is a seamless operational backbone that reduces picking errors, minimises waste, and optimises delivery routes to lower per-order costs.
The landscape is still evolving, but a clearer picture of sustainable online grocery models is emerging. It involves a hybrid approach: leveraging existing physical stores as micro-fulfilment centres, investing strategically in automated dark stores for high-demand areas, and building flexible delivery networks. The retailers that master this intricate balance, while also understanding the nuances of regional consumer behaviour, are poised to capture a greater share of Europe's digital grocery spend, which is projected to expand significantly over the coming decade.
The next frontier is not merely about getting groceries to the door, but doing so with a level of efficiency that allows for consistent profitability, transforming what was once a pandemic-driven necessity into a fundamental pillar of modern European commerce.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
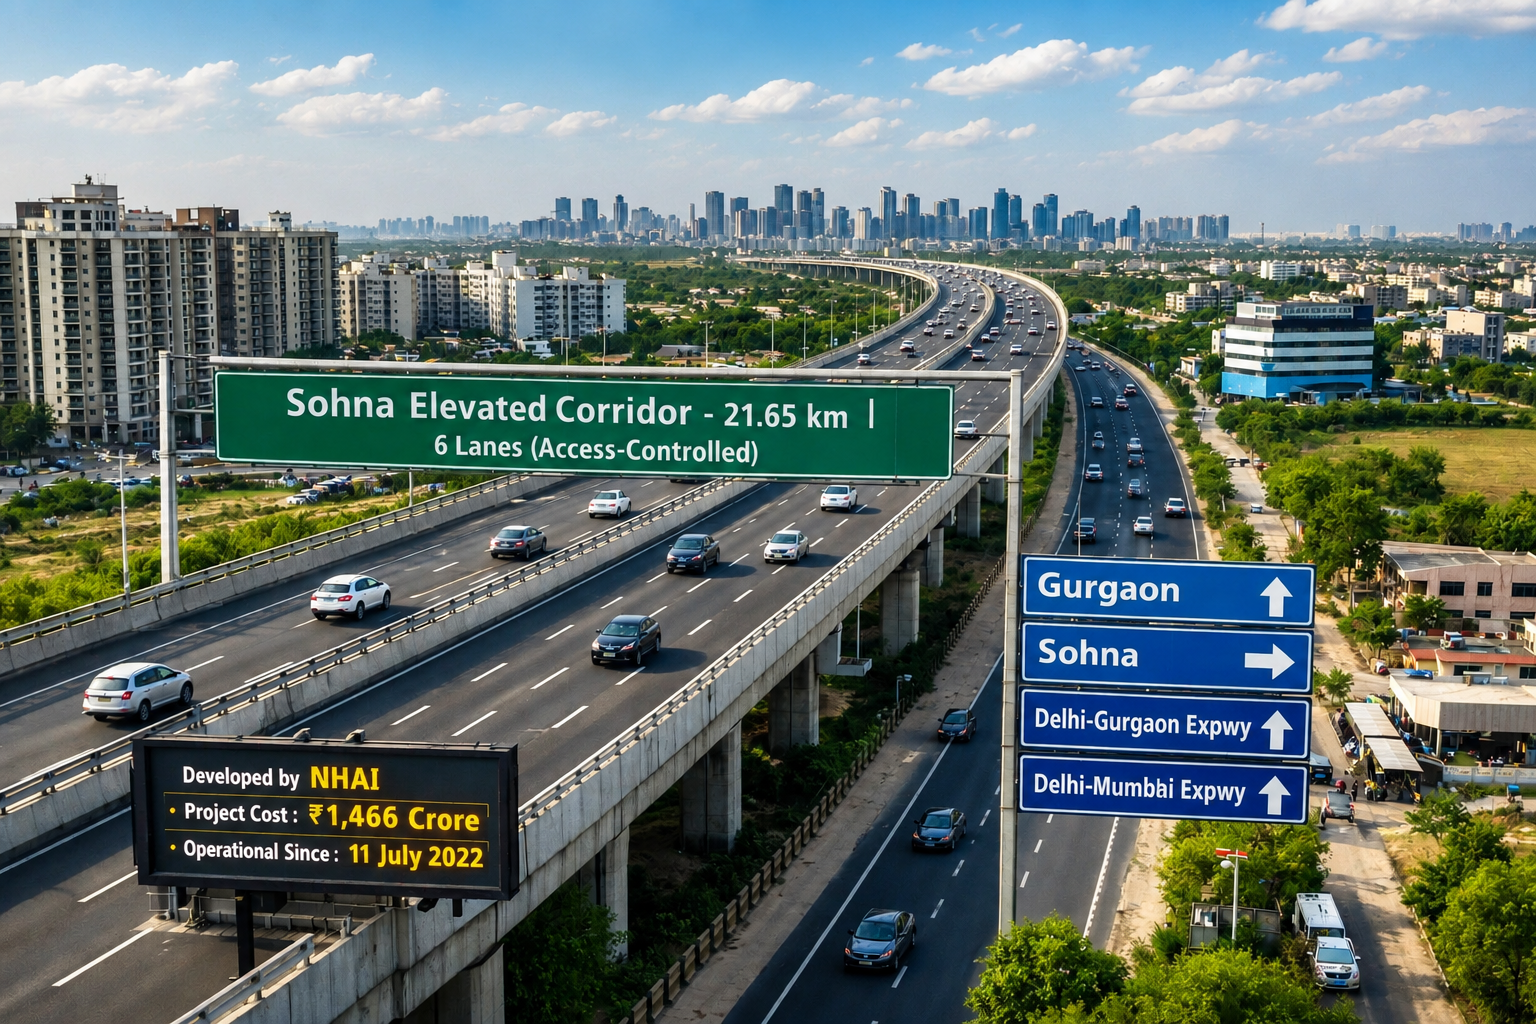
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
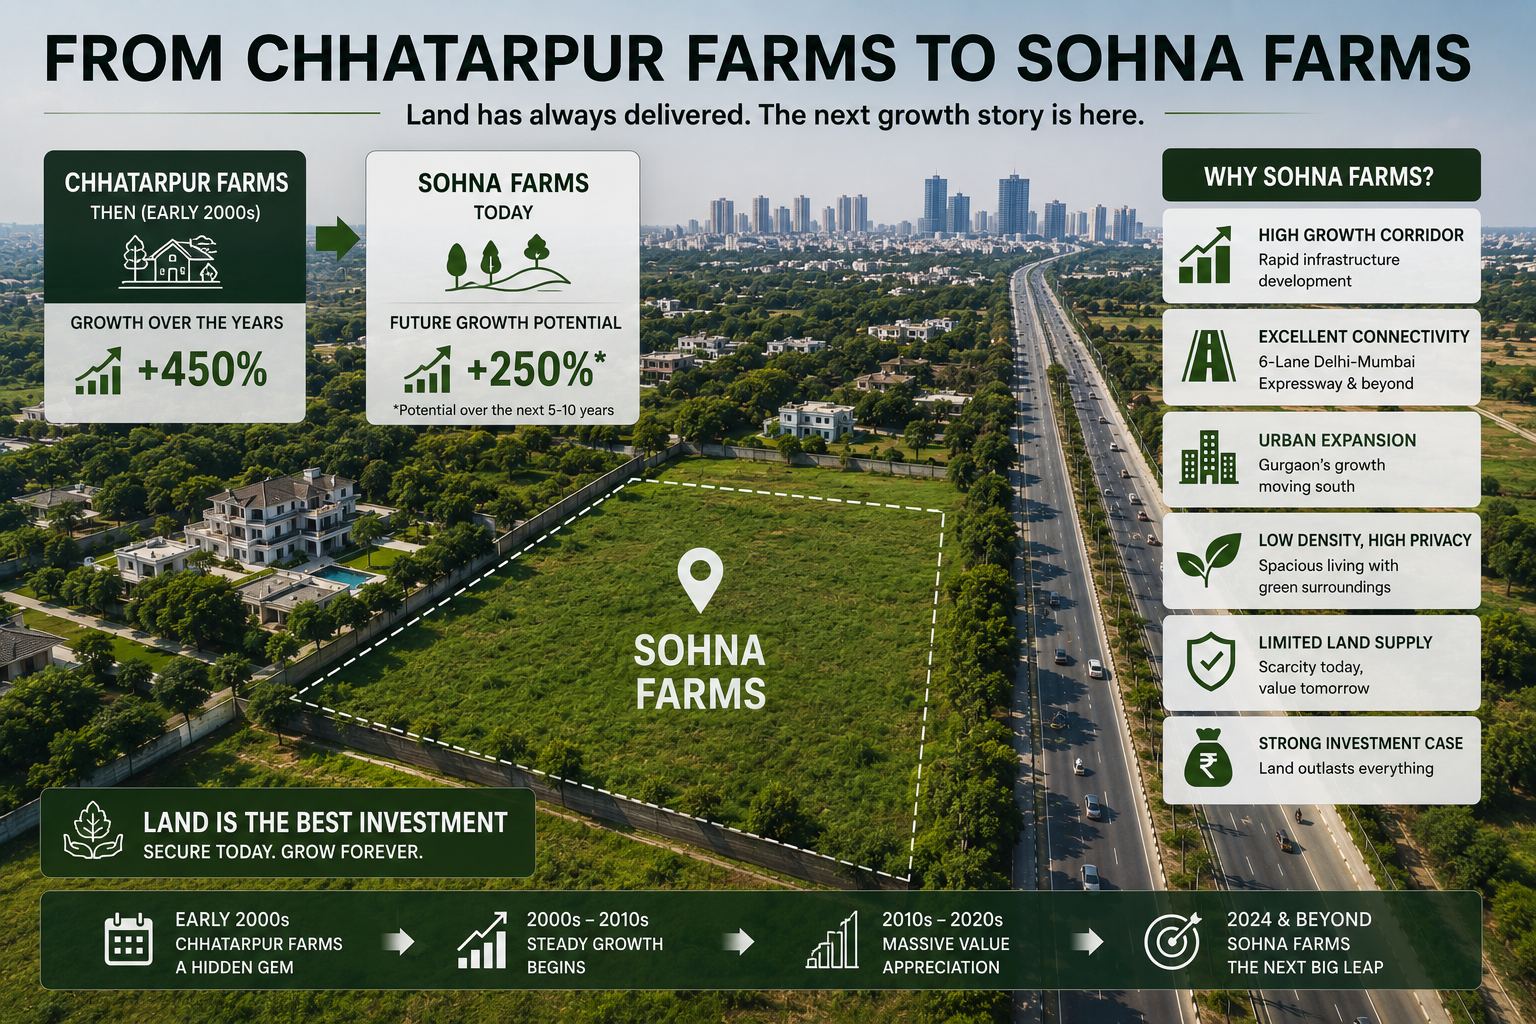
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
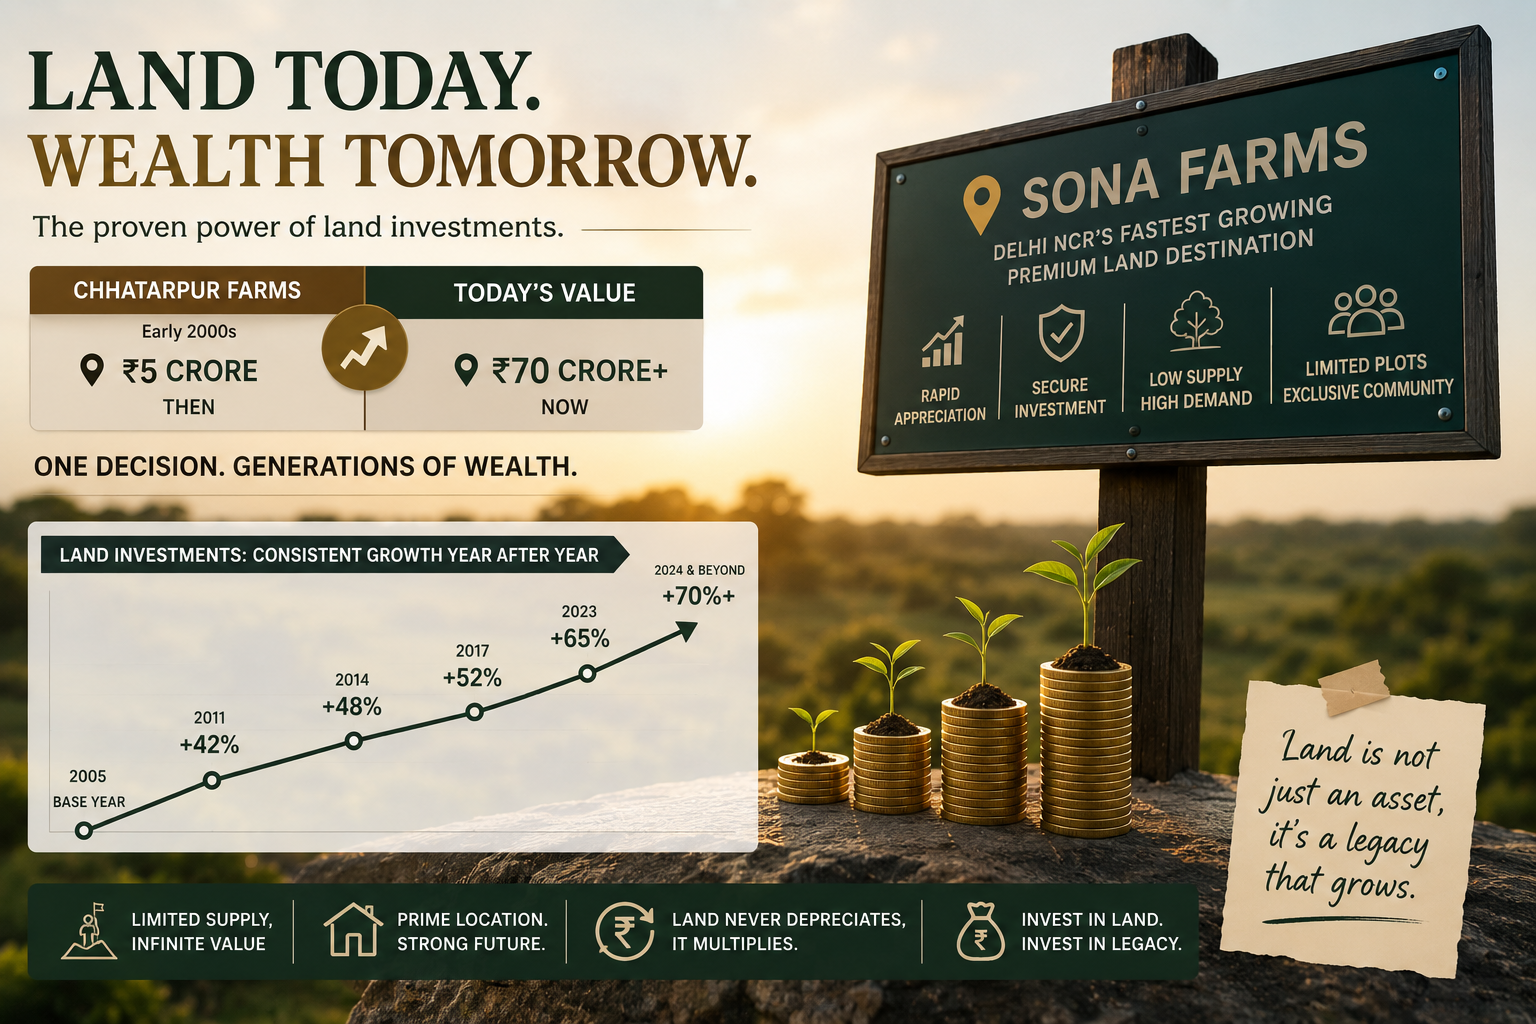
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.