The Last Mile's Shifting Ground: EU Logistics Rethink Supply Chain Density
European retailers and logistics providers are recalibrating their strategies for the final delivery leg, navigating rising costs, consumer expectations, and a fragmented regulatory landscape across the continent.

The distinctive orange livery of a Flink delivery cyclist, once a ubiquitous sight in major German and Dutch urban centres, has become a rarer phenomenon. While not a complete retreat, the company’s strategic contraction from numerous smaller European markets, such as France and Spain, signals a broader industry recognition: the ‘last mile’ in e-commerce, particularly for groceries and instant delivery, represents a formidable economic challenge. This recalibration is forcing a fundamental rethink among traditional retailers, pure-play e-commerce giants, and specialised logistics firms alike, as they seek sustainable models for fulfilling orders across a diverse European geography.
For years, the imperative was speed and coverage, often at any cost. Investment poured into dark stores and micro-fulfilment centres, driven by a perception that consumers prioritised immediacy above all else. However, the subsequent years revealed the true operational expenses associated with this model, including labour, real estate in prime urban locations, and the amortisation of specialised delivery fleets. Companies like Gorillas, after burning through substantial capital, ultimately merged with a competitor, a testament to the sector's unsustainability under prevailing conditions.
The Cost of Convenience: A Margin Squeeze
The financial reality bites hardest when considering the average order value in instant grocery versus the fixed and variable costs of each delivery. While consumers embraced the convenience, their willingness to pay a premium for expedited service has often not offset the underlying operational burden. Traditional grocers like Carrefour in France or REWE in Germany, with their existing store networks, possess a natural advantage: they can leverage brick-and-mortar locations as click-and-collect points or local fulfilment hubs at a fraction of the cost of purpose-built dark stores. This hybrid approach allows for greater capital efficiency and a more flexible response to localised demand fluctuations.
E-commerce behemoths such as Zalando, which operates across multiple EU markets from Poland to Italy, and Dutch-Belgian platform Bol.com, face similar challenges but on a different scale. Their high-volume, non-perishable goods allow for more centralised warehousing and trunk haul optimisation. Yet, the final leg to the consumer’s door, especially in densely populated urban cores or sparsely populated rural areas, still commands a significant portion of the total logistics budget. This pressure is exacerbated by consumer demands for flexible delivery windows and free returns, which erode already thin margins.
The persistent pursuit of delivery speed without a commensurate revenue stream for that premium service has proven a precarious venture for many operators. The emphasis is now firmly on cost efficiency and strategic market selection.
Cross-Border Complexities and Infrastructure Gaps
The regulatory mosaic and infrastructure variances across the EU further complicate logistics strategies. A consolidated customs union simplifies trade, but national labour laws, urban access restrictions, and differing road networks present persistent hurdles for cross-border e-commerce players like Allegro, expanding from its Polish base, or Vinted, facilitating second-hand trade across the continent. Navigating these discrepancies requires sophisticated planning and often mandates local partnerships or bespoke solutions, adding layers of expense and complexity.
For example, delivering an item from a warehouse in Germany to a customer in the south of France involves navigating distinct transport regulations, often requiring multiple carriers or handover points. The last mile in a sprawling city like Paris or Rome differs significantly from a delivery in a Nordic capital or a Spanish rural town. This fragmentation underscores why many logistics operators are now investing heavily in data analytics and artificial intelligence to optimise routing, predict demand, and enhance fleet utilisation, seeking incremental gains across thousands of daily deliveries.
Looking ahead, the European logistics landscape is poised for further consolidation and specialisation. The era of unchecked expansion for quick commerce may be largely over, replaced by a more pragmatic approach focused on profitability and targeted market penetration. Traditional retailers will continue to integrate their online and offline channels, while pure-play e-commerce firms will increasingly seek efficiencies through automation in warehousing and intelligent network design, ensuring that the final delivery is not merely fast, but financially viable.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
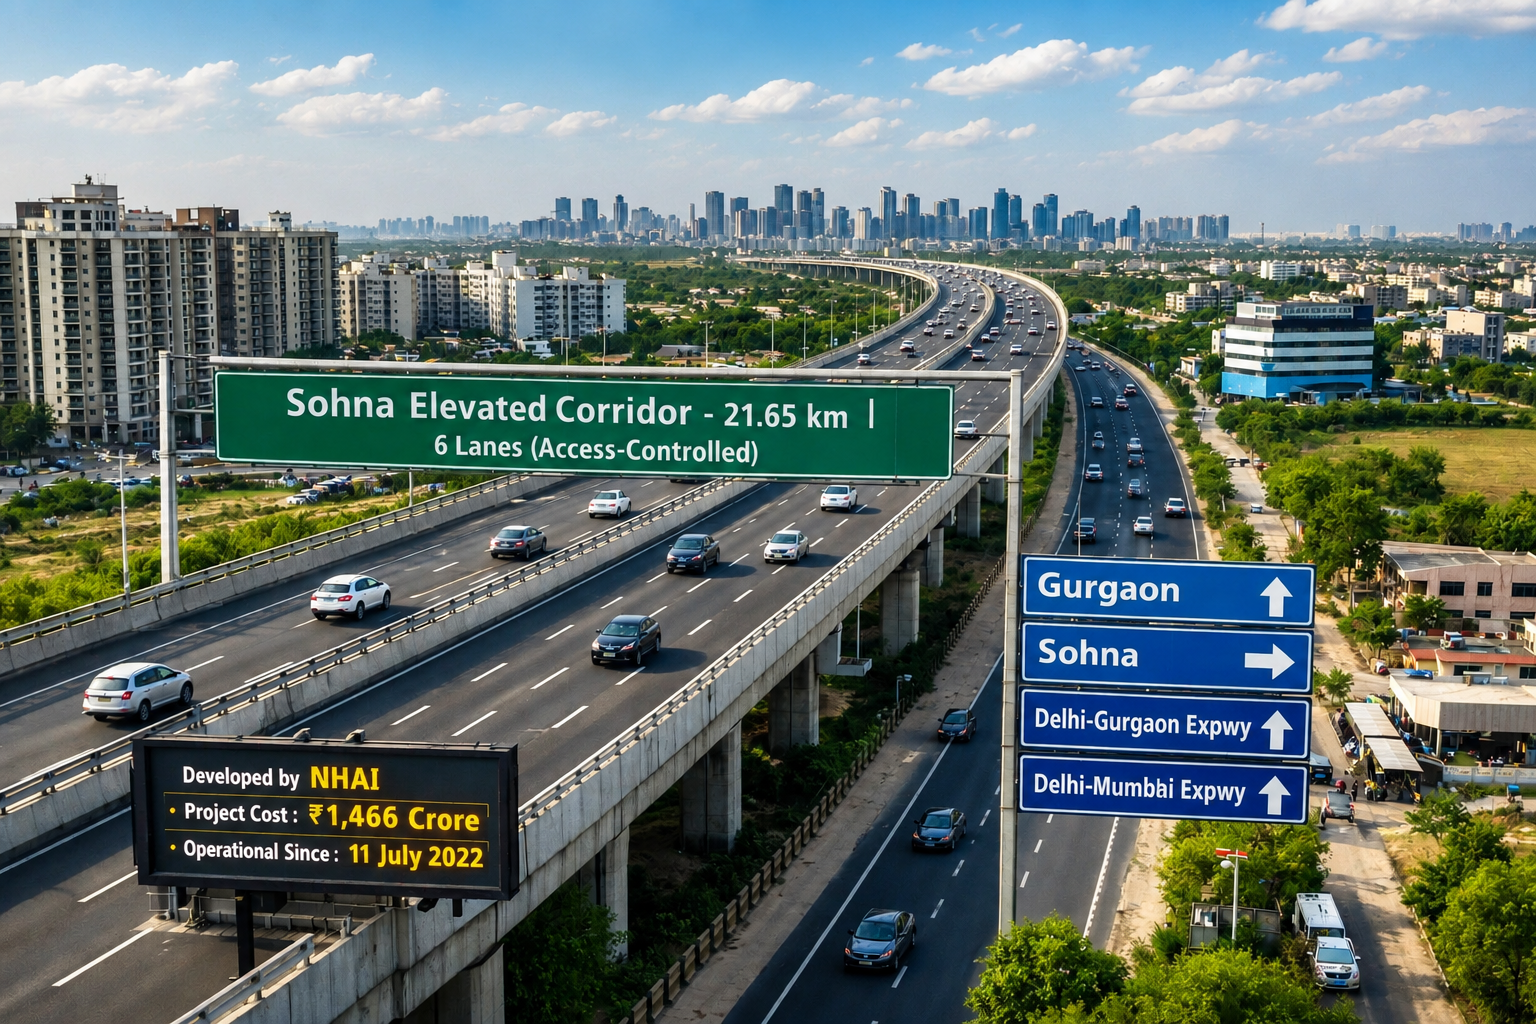
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
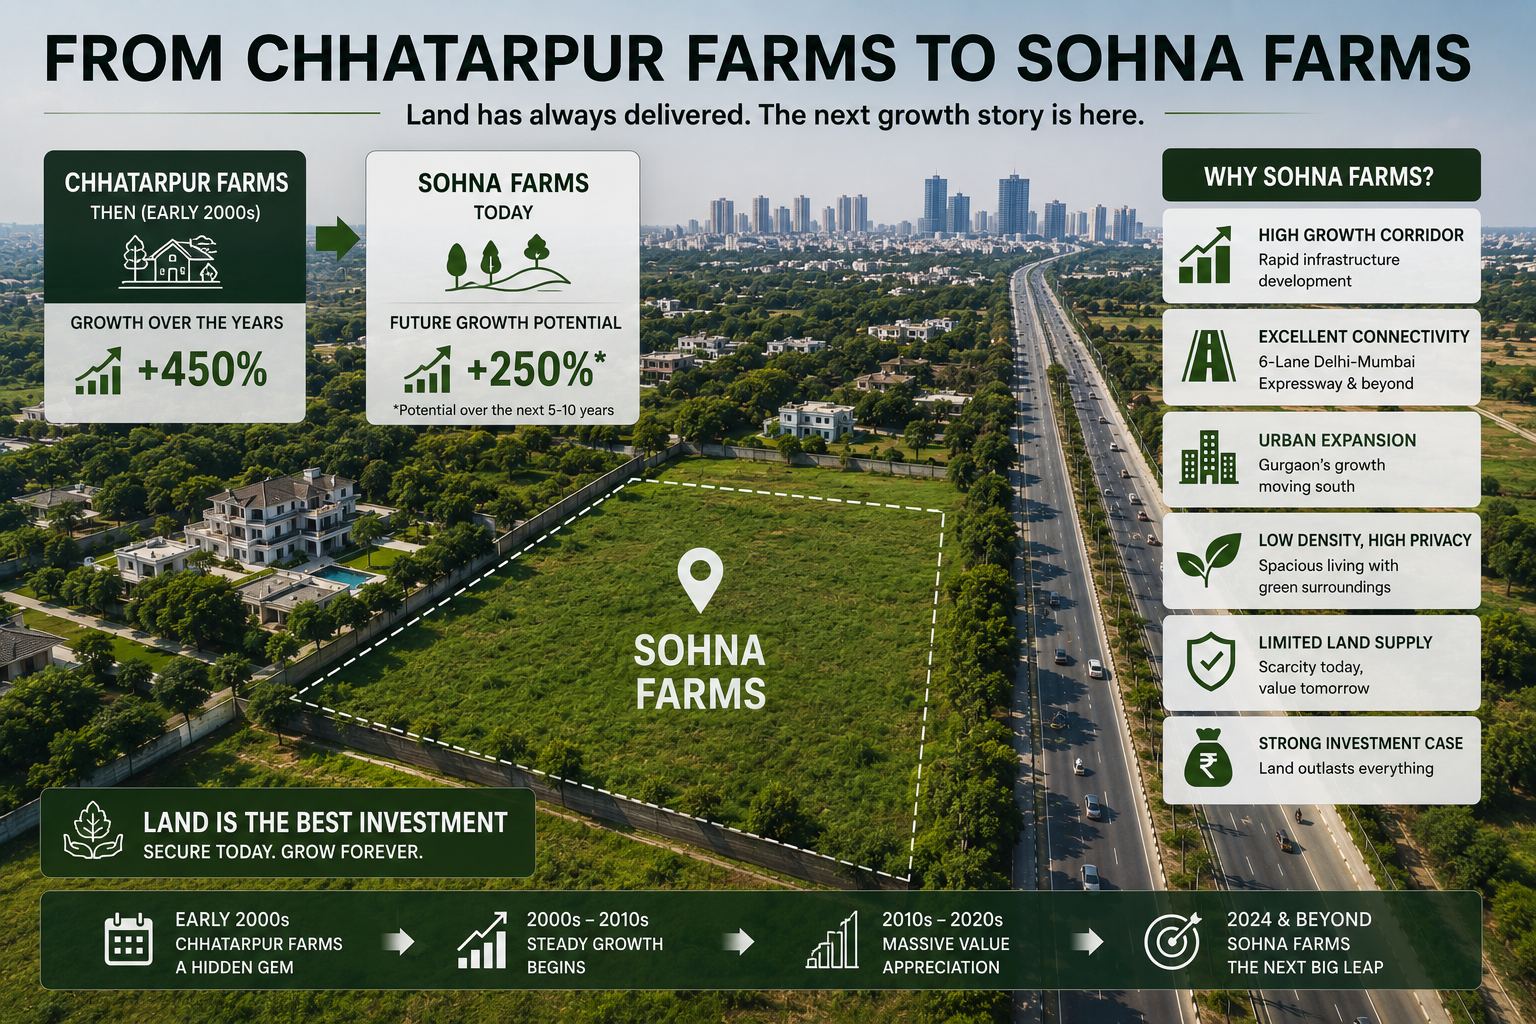
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
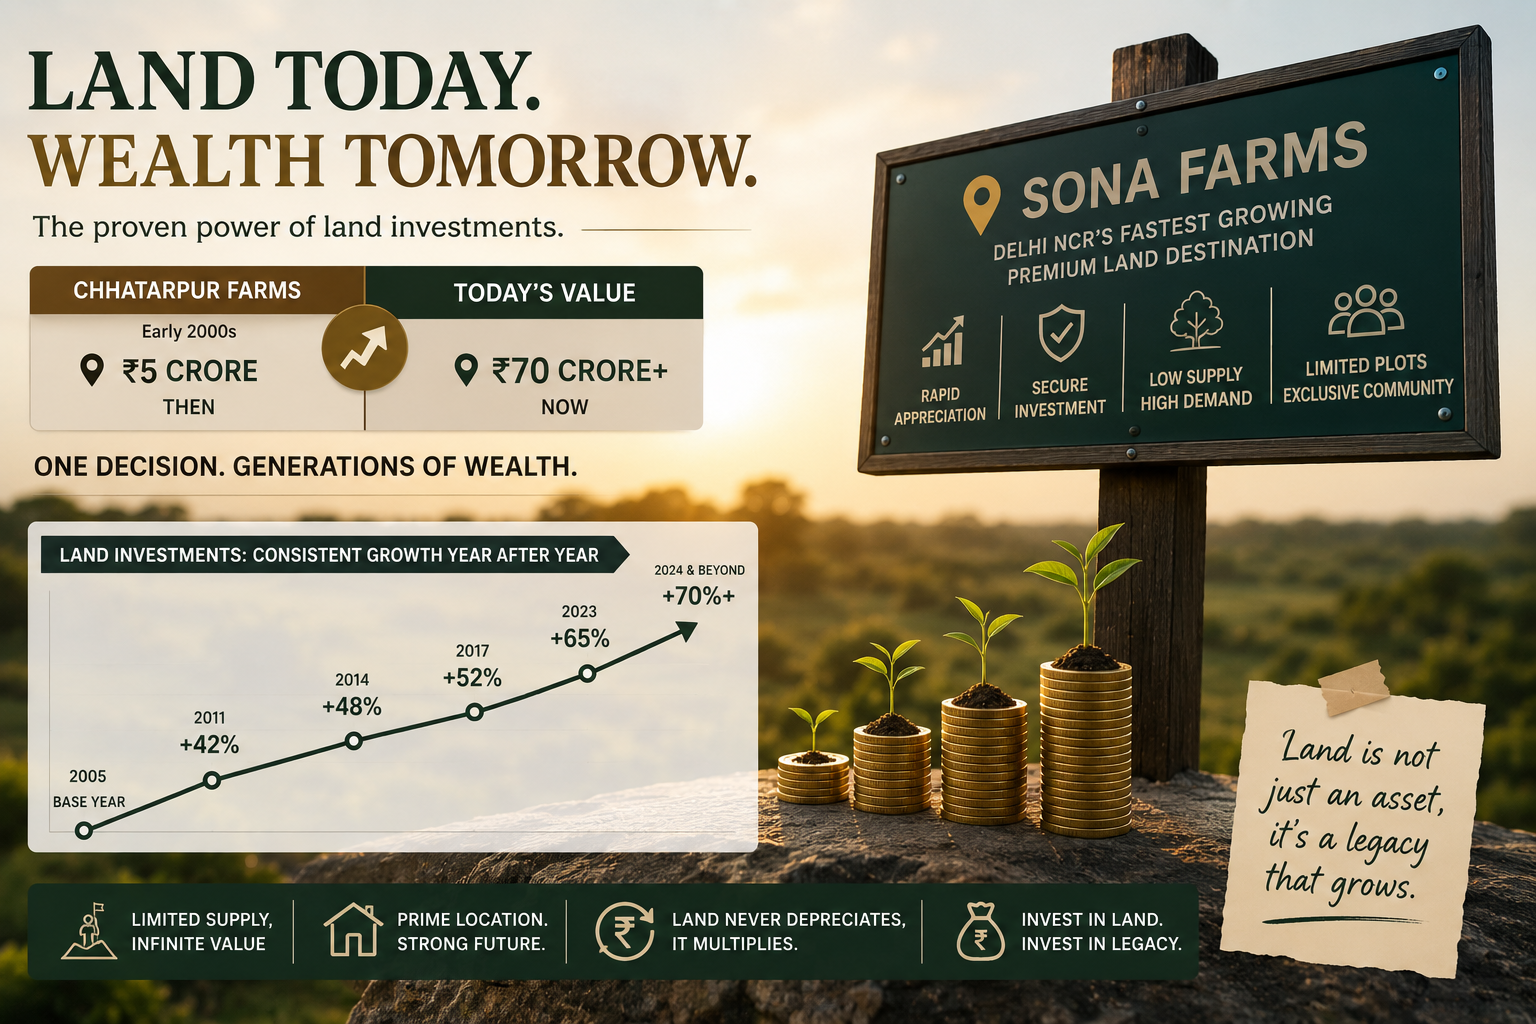
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.