The Modular Reckoning: Why Europe’s Retail Giants Are Dismantling Monolithic Commerce Stacks
Faced with fragmented payment rails and divergent tax regimes from Warsaw to Madrid, continental merchants are abandoning rigid enterprise suites in favour of bespoke, composable infrastructure.

Inside Carrefour’s digital hubs in Paris and Madrid, the engineering challenge of operating across diverse national markets has reached an architectural breaking point. For over a decade, continental retail groups relied on sweeping enterprise software agreements with North American vendors, entrusting their catalogues, inventory databases, and checkout funnels to single-vendor enterprise suites. Yet as cross-border trade accelerates between France, Germany, Spain, and Poland, those rigid monoliths are proving ill-suited to the practical realities of European digital trade.
The core difficulty lies in continental Europe’s structural diversity. While the European Union represents a single market on paper, digital commerce remains stubbornly provincial. A unified checkout stack that functions flawlessly for a shopper in Frankfurt often stumbles when confronted with Poland’s Blik system, Dutch iDEAL requirements, or the complex electronic invoicing mandates recently enacted in Italy and France. For multi-territory players like Zalando or Ahold Delhaize’s Bol, adapting a centralised proprietary platform to accommodate regional payment methods, national fiscalisation rules, and localized return logistics has become an expensive engineering bottleneck.
The friction of twenty-seven jurisdictions
To overcome these operational hurdles, European engineering leadership is pivoting toward composable commerce—an architectural model that swaps all-in-one software suites for modular, application programming interface (API) driven components. Instead of licensing a single platform that dictates every layer from product catalogue to customer interface, merchants assemble distinct, interchangeable services. Under this paradigm, an enterprise can deploy a specialised Munich-engineered pricing engine alongside a French retail-media module and a Scandinavian subscription billing service, without destabilising the underlying enterprise resource planning core.
The financial implications of this migration are substantial. Enterprise retailers across the euro area routinely commit tens of millions of euros annually to maintain and patch legacy commerce cores that cannot dynamically scale during peak promotional events. When regional operators attempt to rival the technological agility of domestic champions such as Poland's Allegro or second-hand marketplace Vinted—both of which scaled on highly bespoke, microservice-based infrastructure—the inflexibility of off-the-shelf software becomes a measurable drag on margin.
The illusion of a frictionless single market dissipates the moment an enterprise attempts to process fiscal receipts across three neighbouring euro-area jurisdictions within a single database schema.
Sovereign infrastructure and cross-border agility
A parallel catalyst is the growing insistence on infrastructural sovereignty. European merchants are increasingly wary of over-dependence on foreign cloud providers and proprietary SaaS ecosystems that lock customer data into overseas data centres. The Schwarz Group, parent of discount giant Lidl, demonstrated the extreme version of this strategy by developing its own cloud and software stack, StackIT, turning internal infrastructure requirements into an independent commercial offering. While few retailers possess the capital reserves to build sovereign data centres, the desire for autonomy is steering mid-market merchants toward open, cloud-agnostic microservices that allow rapid vendor substitution.
This architectural decentralisation is also reshaping the grocery and rapid-delivery landscape. The legacy of Europe’s quick-commerce shakeout—which saw pioneers like Gorillas absorbed and survivors such as Flink refine their unit economics—demonstrated that survival depends on micro-optimisations at the edge. Modern supermarket operators such as REWE and Cdiscount now treat their commerce stacks not as back-office utilities, but as algorithmic supply networks that must synchronise local depot picking with immediate digital storefront updates across hundreds of autonomous micro-regions.
The transition carries undeniable implementation hazards; managing dozens of loosely coupled software vendors demands sophisticated internal technical talent, which remains scarce and expensive across the continent. Yet for retailers operating in Europe's fragmented landscape, the cost of systemic inflexibility now outweighs the complexity of systems integration. The era of the all-encompassing enterprise suite is waning, replaced by an ecosystem of discrete, modular tools engineered to bend along national lines without breaking.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
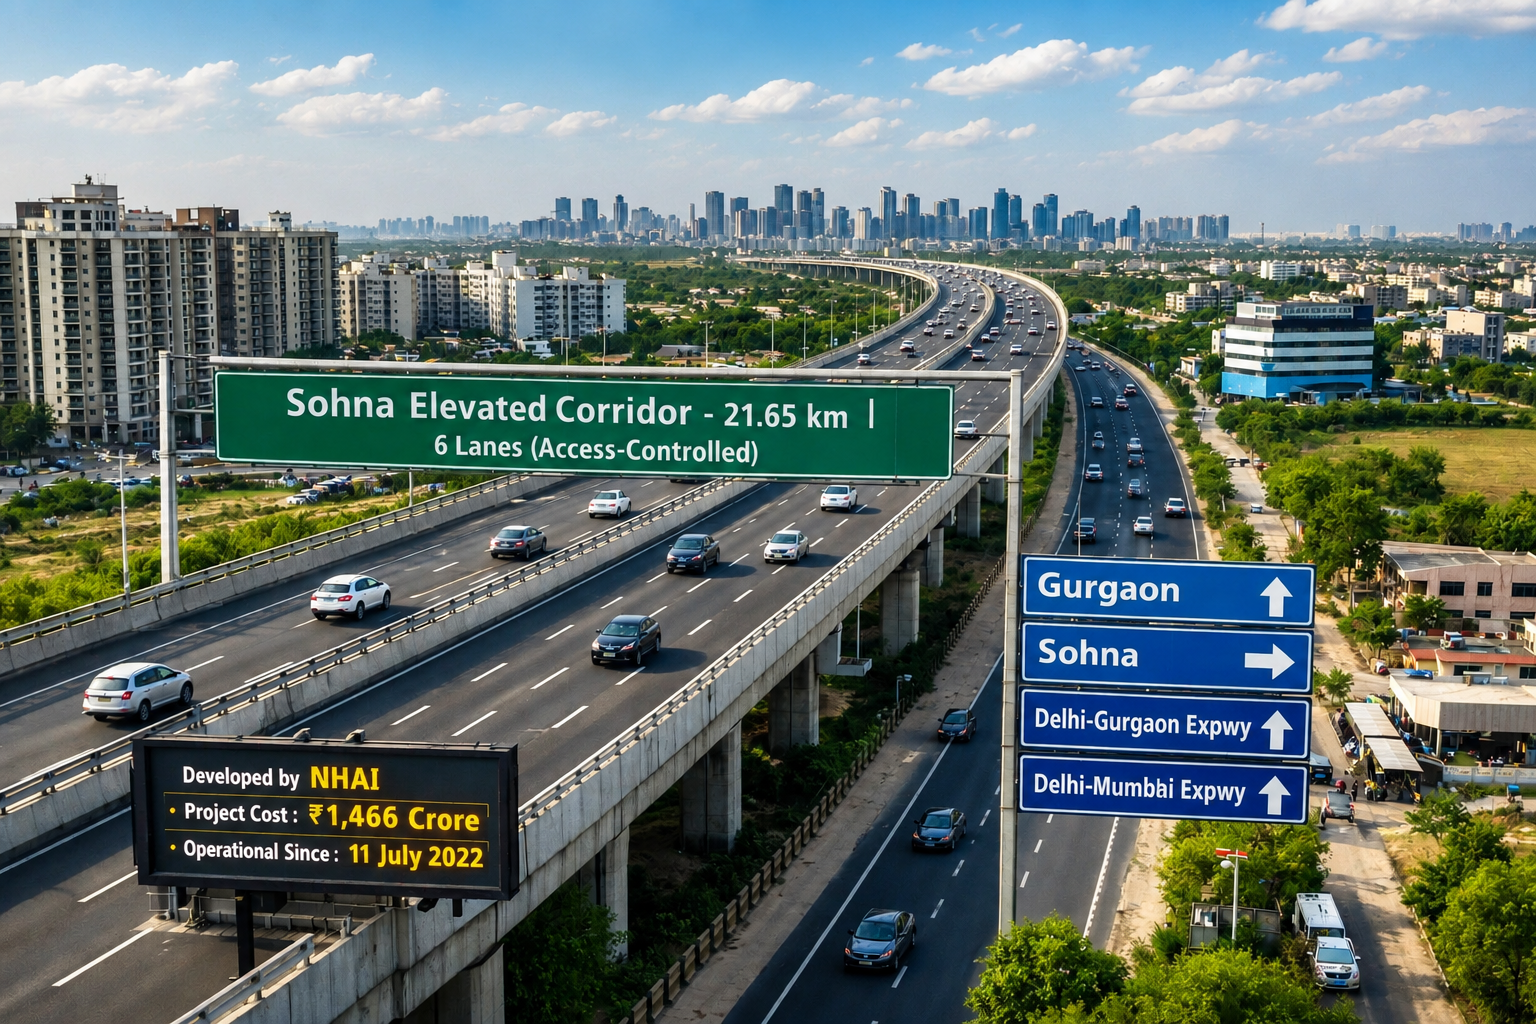
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
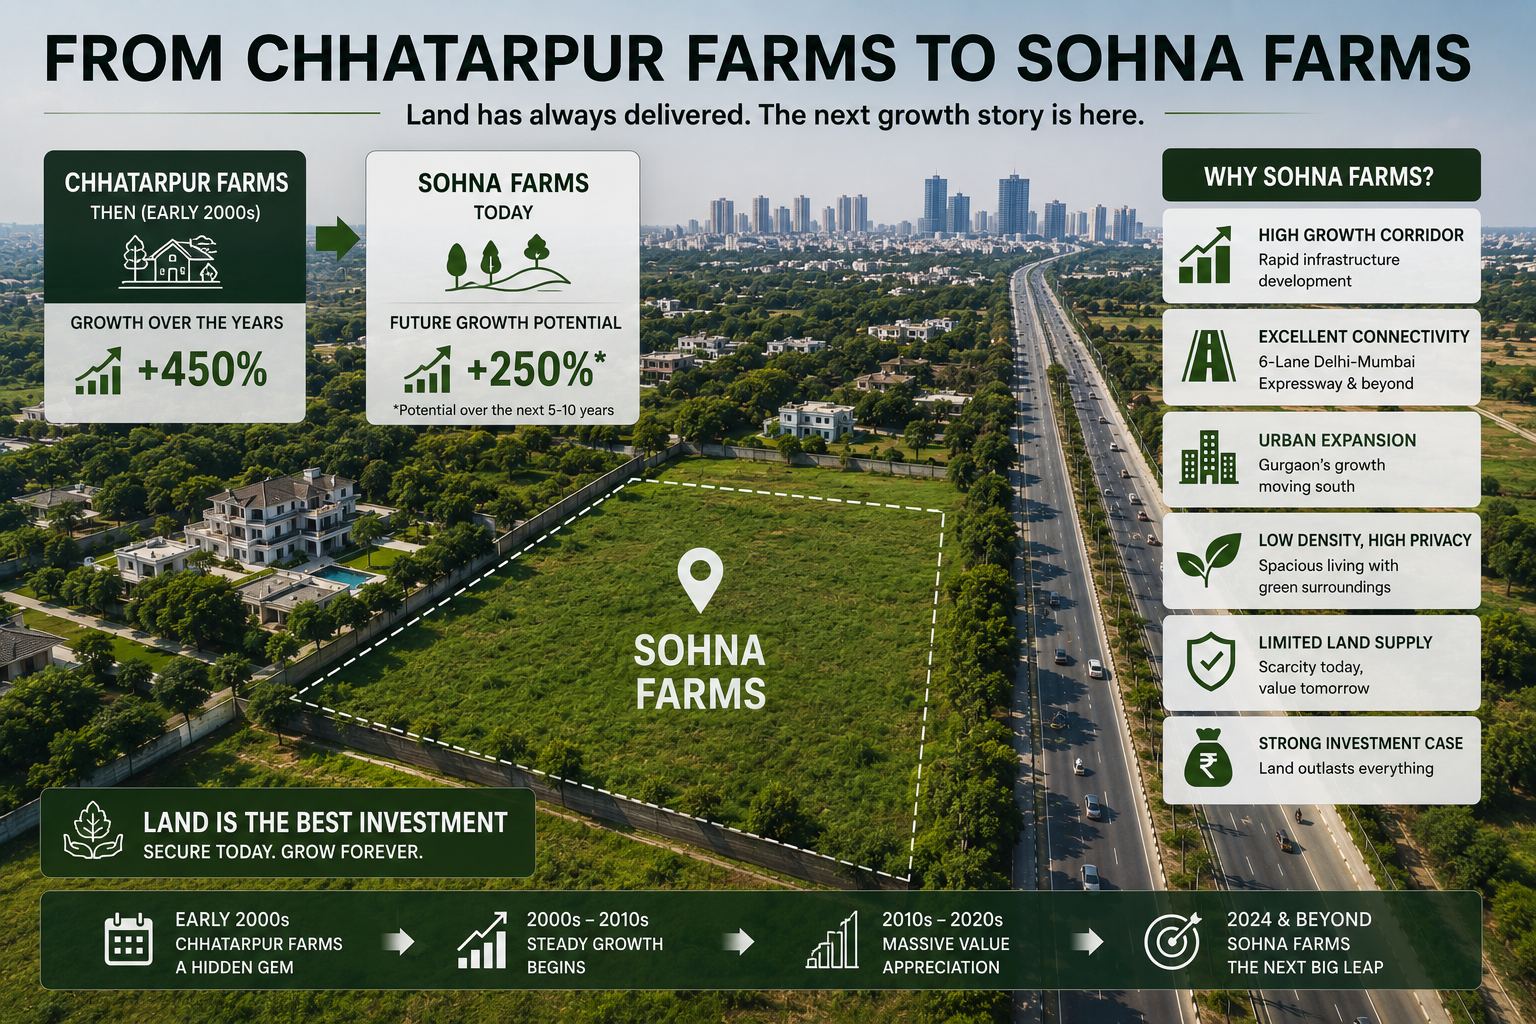
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
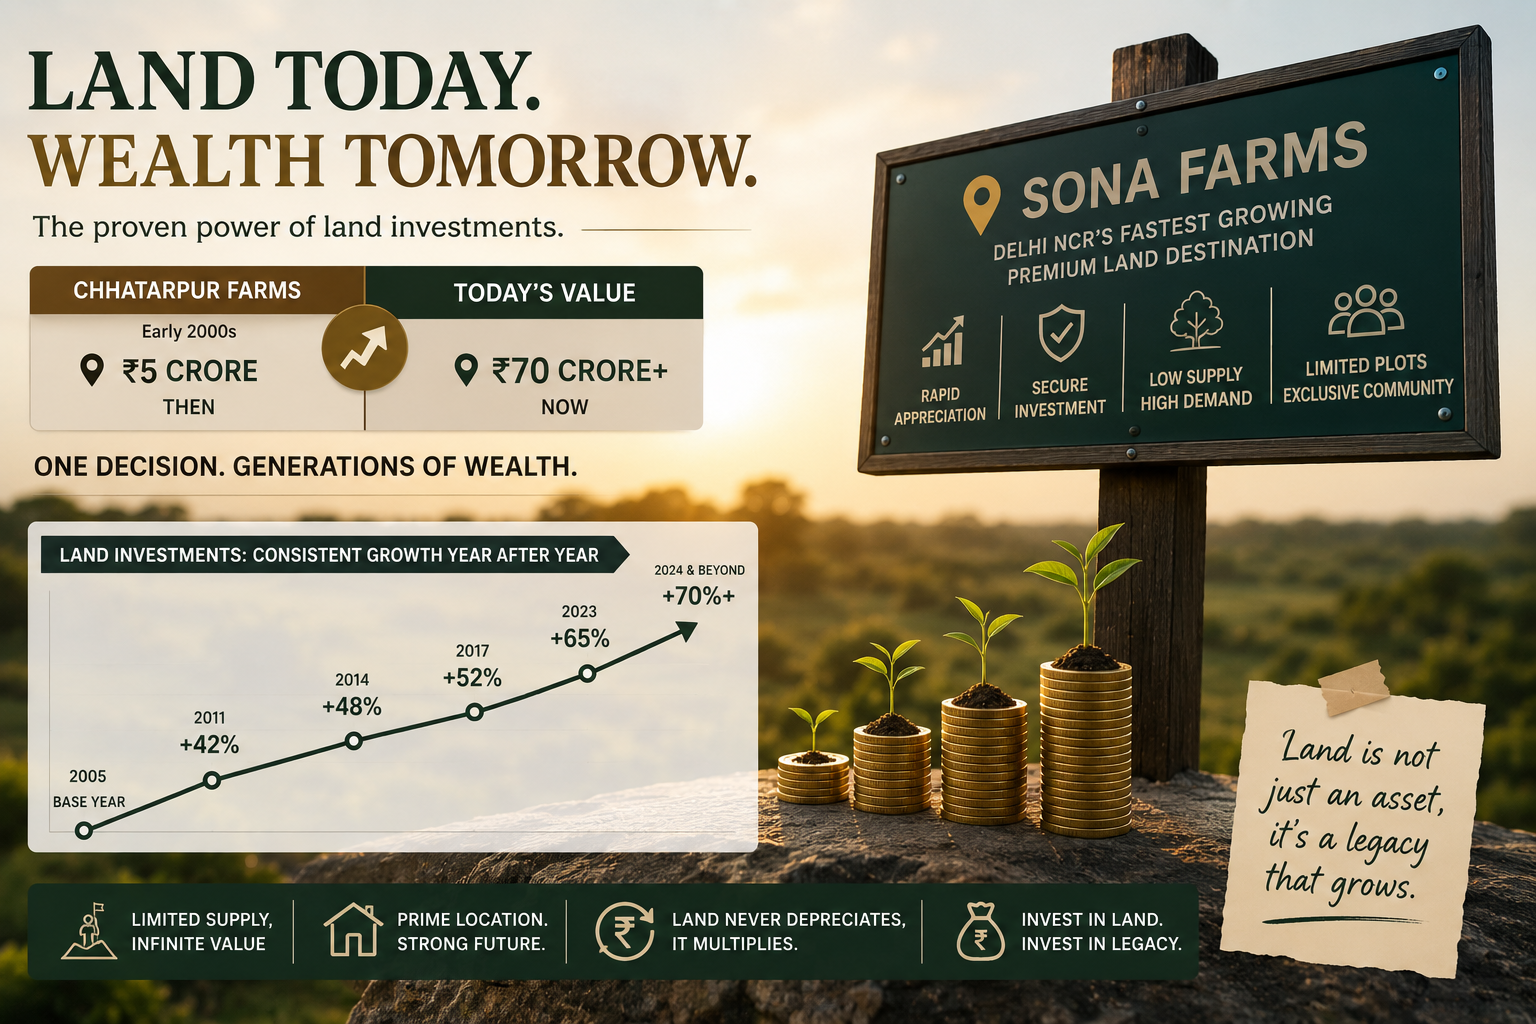
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.