The Modular Retrenchment: How Europe’s Retail Giants Are Dismantling Their Custom Digital Stacks
Faced with cross-border compliance burdens and tightening capital discipline, merchant boards from Berlin to Warsaw are trading bespoke proprietary code for composable commerce architecture.

Inside the engineering centres of Berlin, Paris, and Poznań, enterprise retail teams are methodically dismantling monolithic software architectures that once swallowed tens of millions of euros in capital expenditure. From Zalando opening its logistics infrastructure to third parties to Poland's Allegro and French stalwart Carrefour integrating modular marketplace engines, the ambition to construct proprietary digital stacks entirely from scratch has evaporated. In its place sits a colder, balance-sheet-driven procurement strategy rooted in composable software-as-a-service.
The macroeconomic pressures prompting this pivot are straightforward. A prolonged period of elevated interest rates has eradicated European boardroom tolerance for perpetual software development cycles that fail to yield defensible margins. Furthermore, the brutal correction across the continent’s venture-backed quick-commerce sector—which saw Gorillas absorbed into foreign ownership and Flink forced into defensive restructuring—served as a sobering demonstration: hyper-customised software architecture offers zero salvation when operating unit economics turn upside down.
The Burden of Internal R&D
For more than a decade, continental heavyweights operated under the assumption that true sovereignty required custom-built digital moats. German grocery leaders such as REWE and Lidl poured substantial capital into proprietary systems, attempting to engineer bespoke solutions for everything from micro-fulfilment routing to customer loyalty databases. Yet maintaining these custom stacks across fragmented European territories proved unexpectedly punishing. Every territorial expansion required bespoke development to handle divergent value-added tax regimes, mandatory fiscalisation hardware in Italy, local payment rails such as BLIK in Poland or iDEAL in the Netherlands, and distinct language hierarchies.
Maintaining those bespoke systems gradually siphoned engineering capacity away from commercial innovation, turning core technology divisions into maintenance departments. Composable commerce vendors and specialised API-first platforms have seized this opening. Established operators including Bol in the Benelux and Cdiscount in France have steadily unbundled their legacy monoliths, delegating product information management, checkout orchestration, and cross-border catalogue mapping to multi-tenant cloud providers whose costs are amortised across thousands of corporate clients.
The illusion that a proprietary checkout engine constitutes a sustainable retail moat has been firmly dispelled by five years of brutal margin compression.
Marketplace Federation and Borderless Compliance
The rapid rise of multi-seller marketplace models across Europe has further accelerated this unbundling. As Vilnius-born Vinted proved the capital efficiency of pure platform mechanics, traditional merchant groups sought to replicate those commission-based economics without absorbing corresponding balance-sheet inventory risk. Constructing multi-vendor settlement engines, anti-fraud screening, and seller onboarding portals internally demands years of dedicated software development; modern marketplace infrastructure software enables an established grocer or department store to onboard external sellers within months.
European Union regulatory directives have delivered the final blow to custom software development. Stringent mandates regarding digital product passports, cross-border pricing transparency under the Omnibus Directive, and the strict technical enforcement of the Digital Services Act mean that any proprietary stack requires perpetual, costly compliance revisions. By shifting to specialist SaaS infrastructure, a retailer operating across France, Spain, and Germany effectively outsources the compliance burden to software vendors whose primary commercial obligation is ensuring their code remains legally compliant across twenty-seven sovereign jurisdictions.
What remains of European retail computing is a markedly more standardised, pragmatic landscape. The historic aspiration to build an entirely sovereign, self-contained digital commerce stack has yielded to rigorous financial discipline. As competition from cross-border discount platforms intensifies, the European retailers best positioned to defend their home markets will not be those harbouring the most complex custom codebases, but those carrying the lightest technical overhead.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
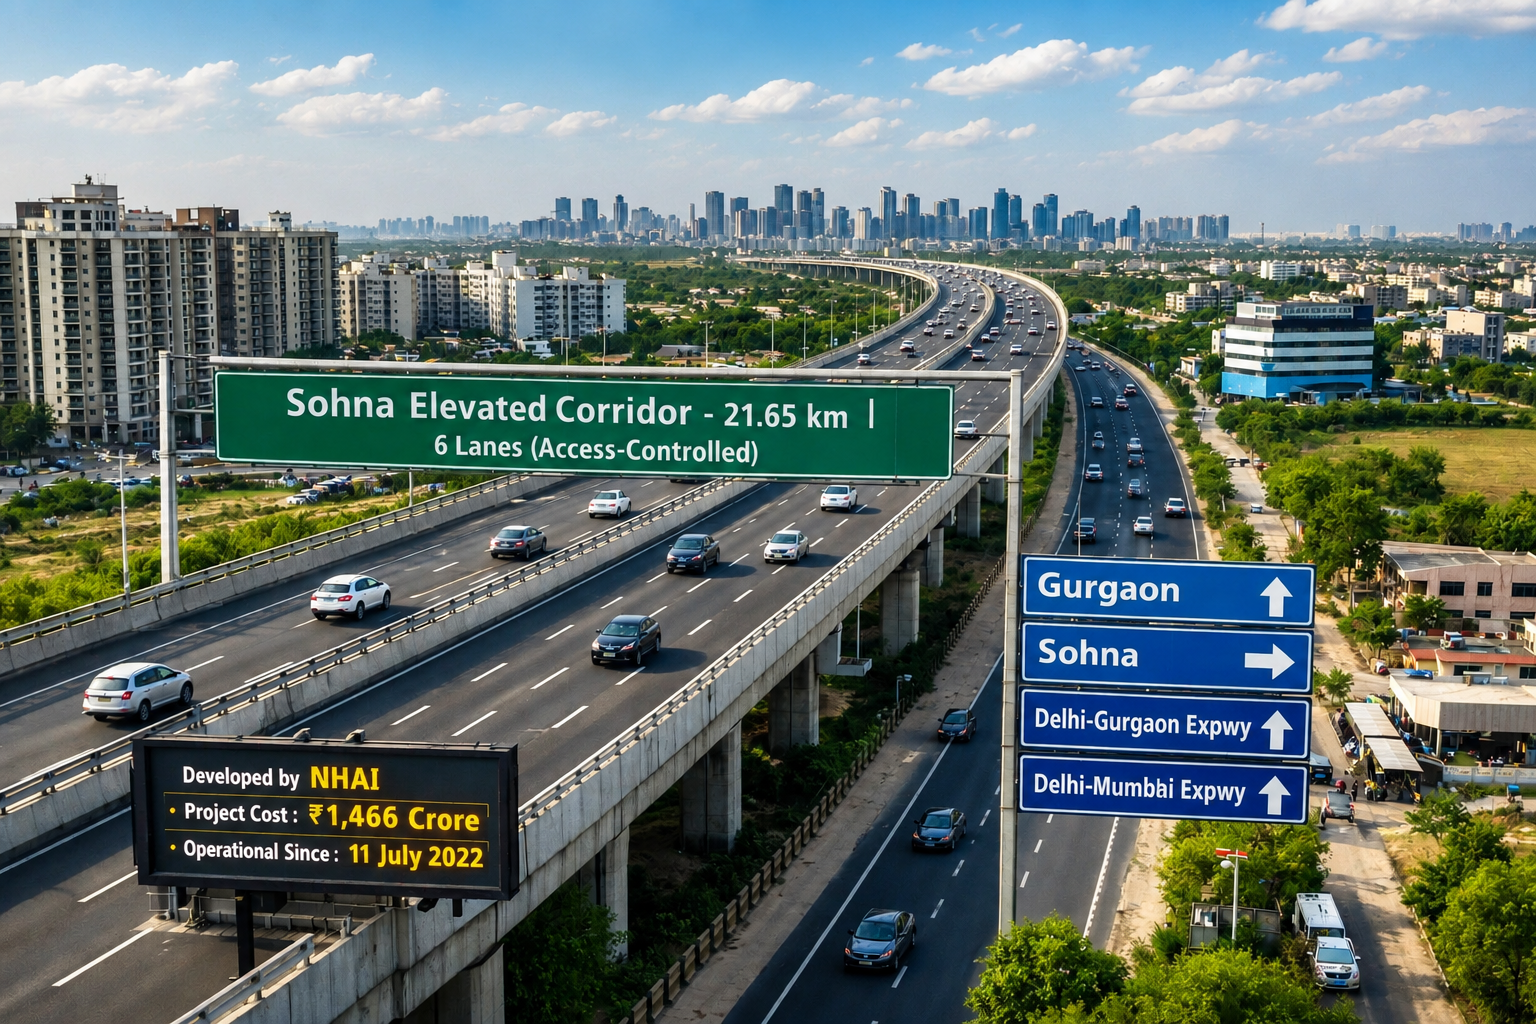
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
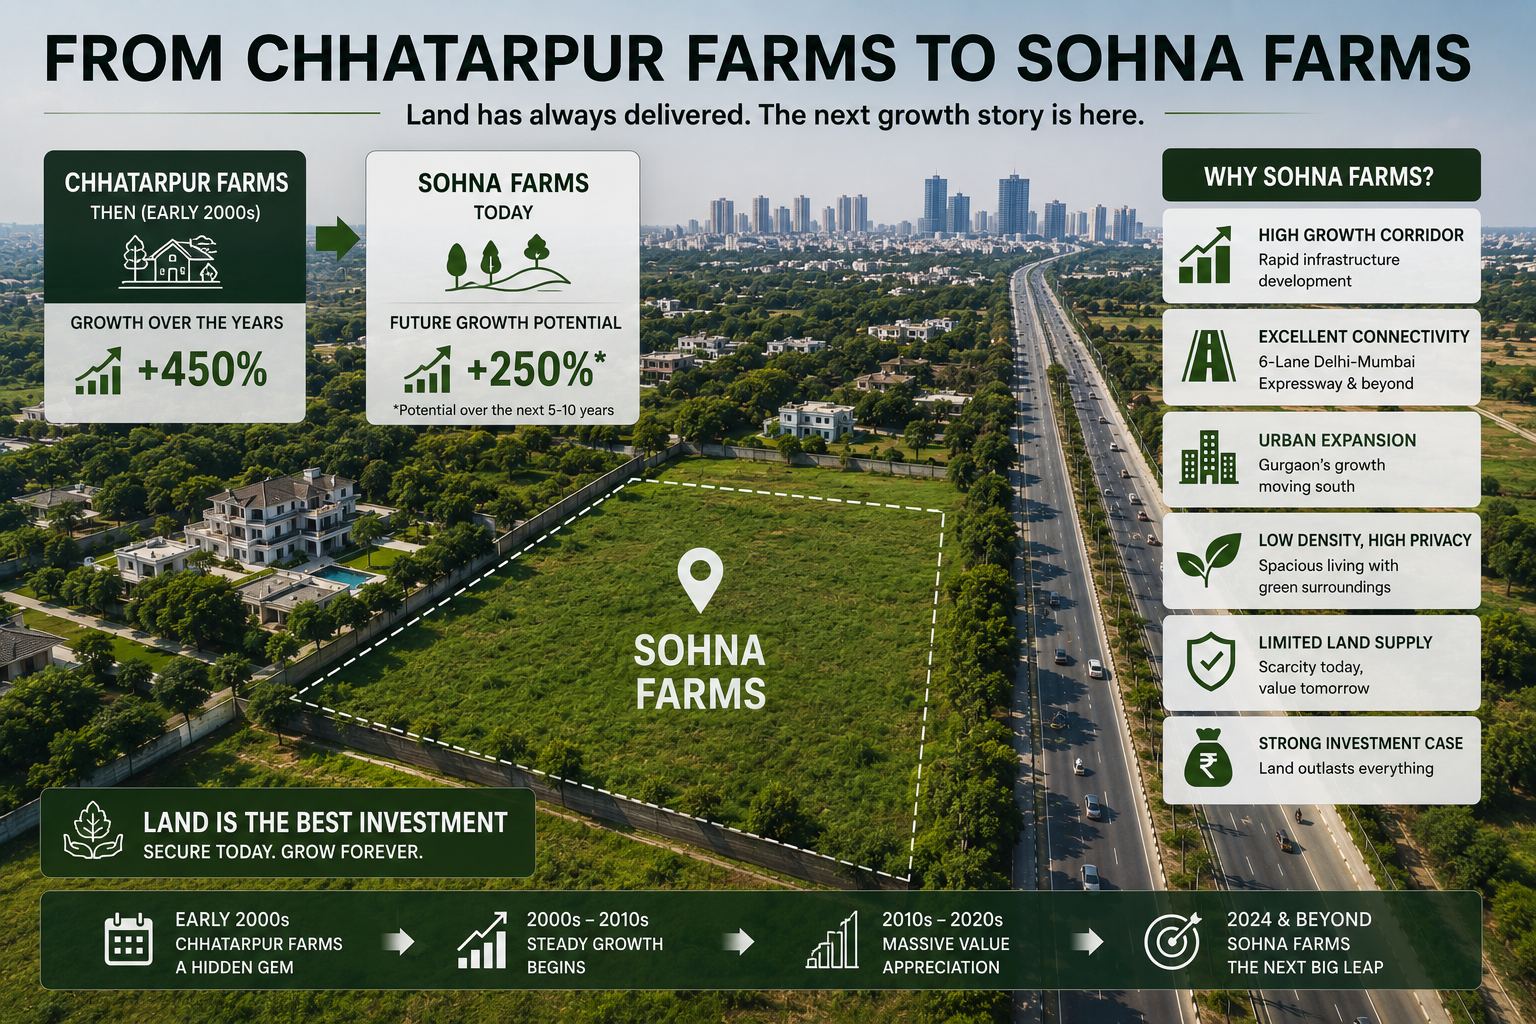
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
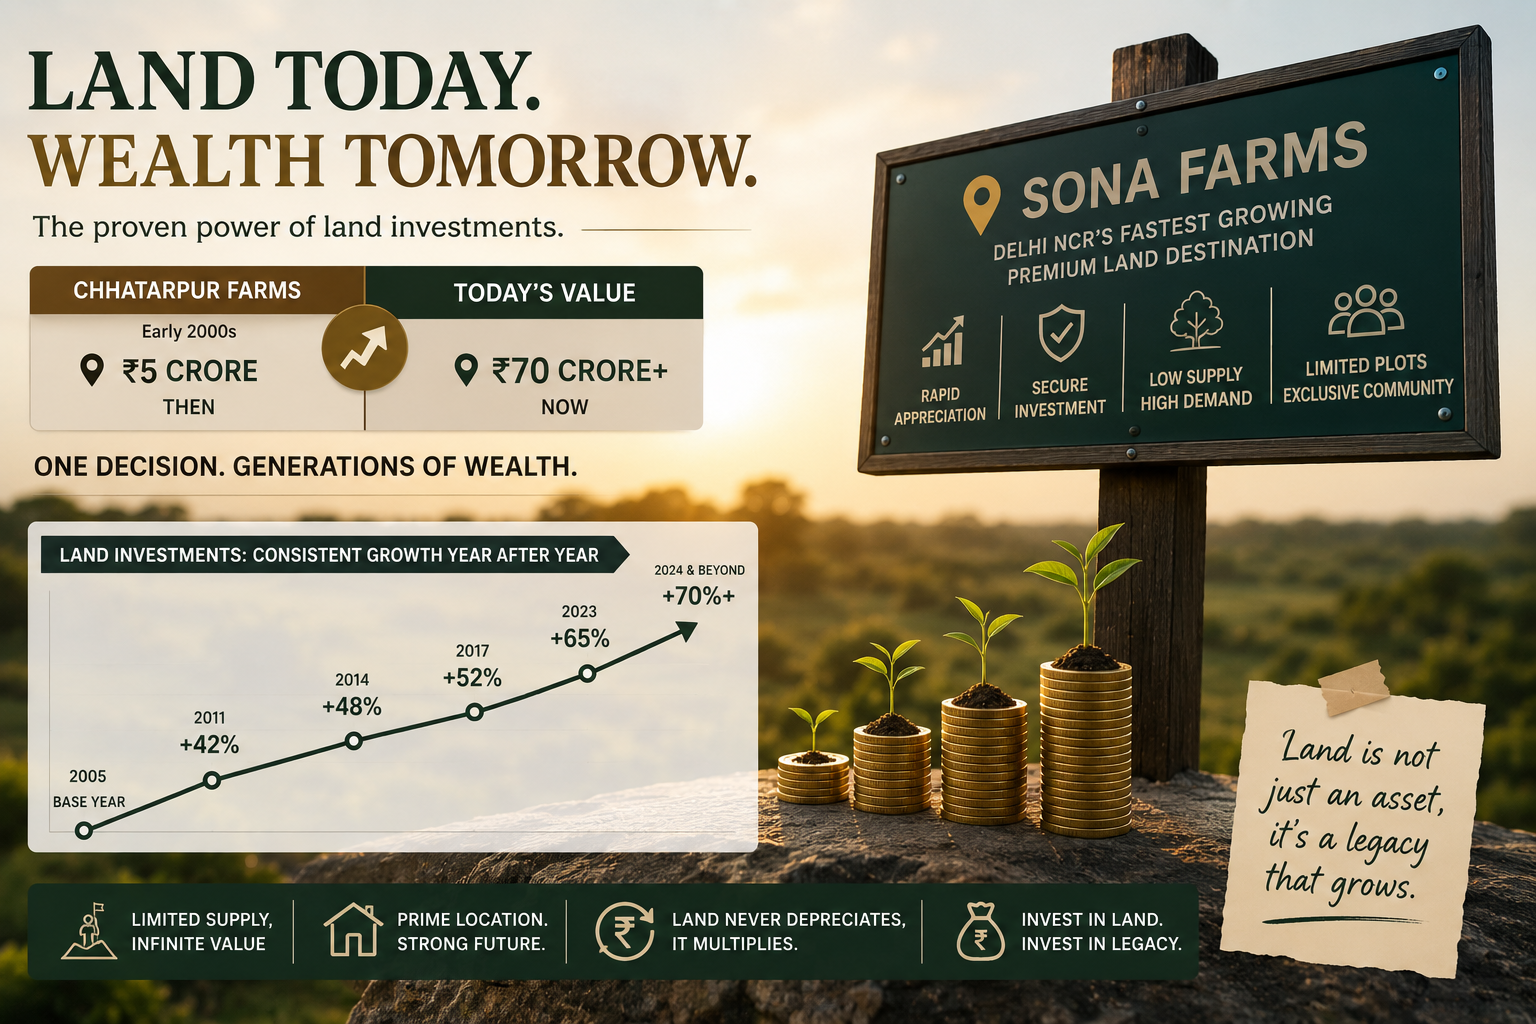
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.