The Perilous Pursuit of Profit: European Retailers Recalibrate SaaS Investments
European retailers are navigating a complex landscape of slowing consumer spend and intensified competition, prompting a critical re-evaluation of their extensive software-as-a-service ecosystems.

At a Carrefour hypermarket in suburban Paris, the digital price tags flicker with promotions, linked seamlessly to inventory and supply chain data. This visible layer of technological integration, however, belies a deeper, more challenging trend across the continent: the escalating cost and fragmented utility of the software powering modern retail. As economic headwinds temper consumer spending, particularly in Germany and the Nordics, European players from Zalando to Lidl are scrutinising every euro spent on the cloud-based tools that promise efficiency and growth.
The initial enthusiasm for digital transformation, fuelled by pandemic-era e-commerce surges, led many retailers to adopt a wide array of SaaS solutions. Marketing automation, customer relationship management, inventory optimisation, logistics coordination, and payment processing all became distinct, often layered, software subscriptions. This 'best-of-breed' approach, while offering specialised functionality, has frequently resulted in spiralling costs and integration headaches, complicating data flows across crucial business functions.
Companies like Allegro in Poland and Bol.com in the Netherlands, which operate extensive marketplace models, have invested heavily in robust platform infrastructure. Their challenge lies in maintaining agility and competitive pricing for their merchants while managing the underlying technological complexity. Smaller players or those with less mature digital operations often struggle even more, finding themselves locked into multi-year contracts that offer diminishing returns as market conditions shift.
The SaaS Consolidation Imperative
A growing sentiment among European retail executives is that the era of simply adding more software layers is drawing to a close. Instead, focus is shifting towards consolidation and optimisation. This involves identifying redundancies, sunsetting underperforming tools, and negotiating more favourable terms with key vendors. The goal is not just cost reduction, but also to achieve a more unified view of the customer and supply chain, which remains elusive for many.
The fragmentation of the European market, with its diverse languages, regulatory frameworks, and consumer preferences, further complicates the picture. A SaaS solution that performs well for REWE's operations in Germany might require significant customisation or even be unsuitable for Cdiscount's model in France or a grocery chain like Edeka. This often forces retailers to adopt a patchwork of regional tools or incur substantial localisation costs from global vendors.
The drive for leaner operations is no longer an aspiration, but a critical response to persistent margin pressures.
Even successful digital-native companies like Vinted, which has seen impressive growth across Europe for its second-hand fashion marketplace, must continually refine its platform strategy to maintain efficiency. The rapid expansion and subsequent retrenchment of quick commerce players like Gorillas and Flink serves as a stark reminder of how quickly operational costs, including significant SaaS expenditures, can undermine a promising business model without rigorous control.
Beyond the Subscription Trap
The long-term strategy for many European retailers now involves a more strategic partnership approach with their technology providers, rather than just transactional vendor relationships. This means demanding greater transparency on total cost of ownership, stronger integration capabilities, and a clearer return on investment. Some are exploring more 'composable commerce' architectures, allowing them to mix and match modular components rather than committing to monolithic suites.
The imperative extends to internal capabilities as well. Investing in in-house data analytics and engineering talent allows retailers to better leverage their existing software investments and build custom solutions for truly unique business challenges, rather than relying solely on external tools. This blend of strategic external procurement and focused internal development is emerging as the preferred path to sustainable digital growth.
The coming years will likely see a significant shake-up in the European retail SaaS market. Vendors that can offer genuinely integrated solutions, transparent pricing, and demonstrable value in a challenging economic climate will thrive. Those that continue to offer siloed, costly tools may find their contracts increasingly scrutinised, and ultimately, cancelled, as European retailers sharpen their focus on profitability.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
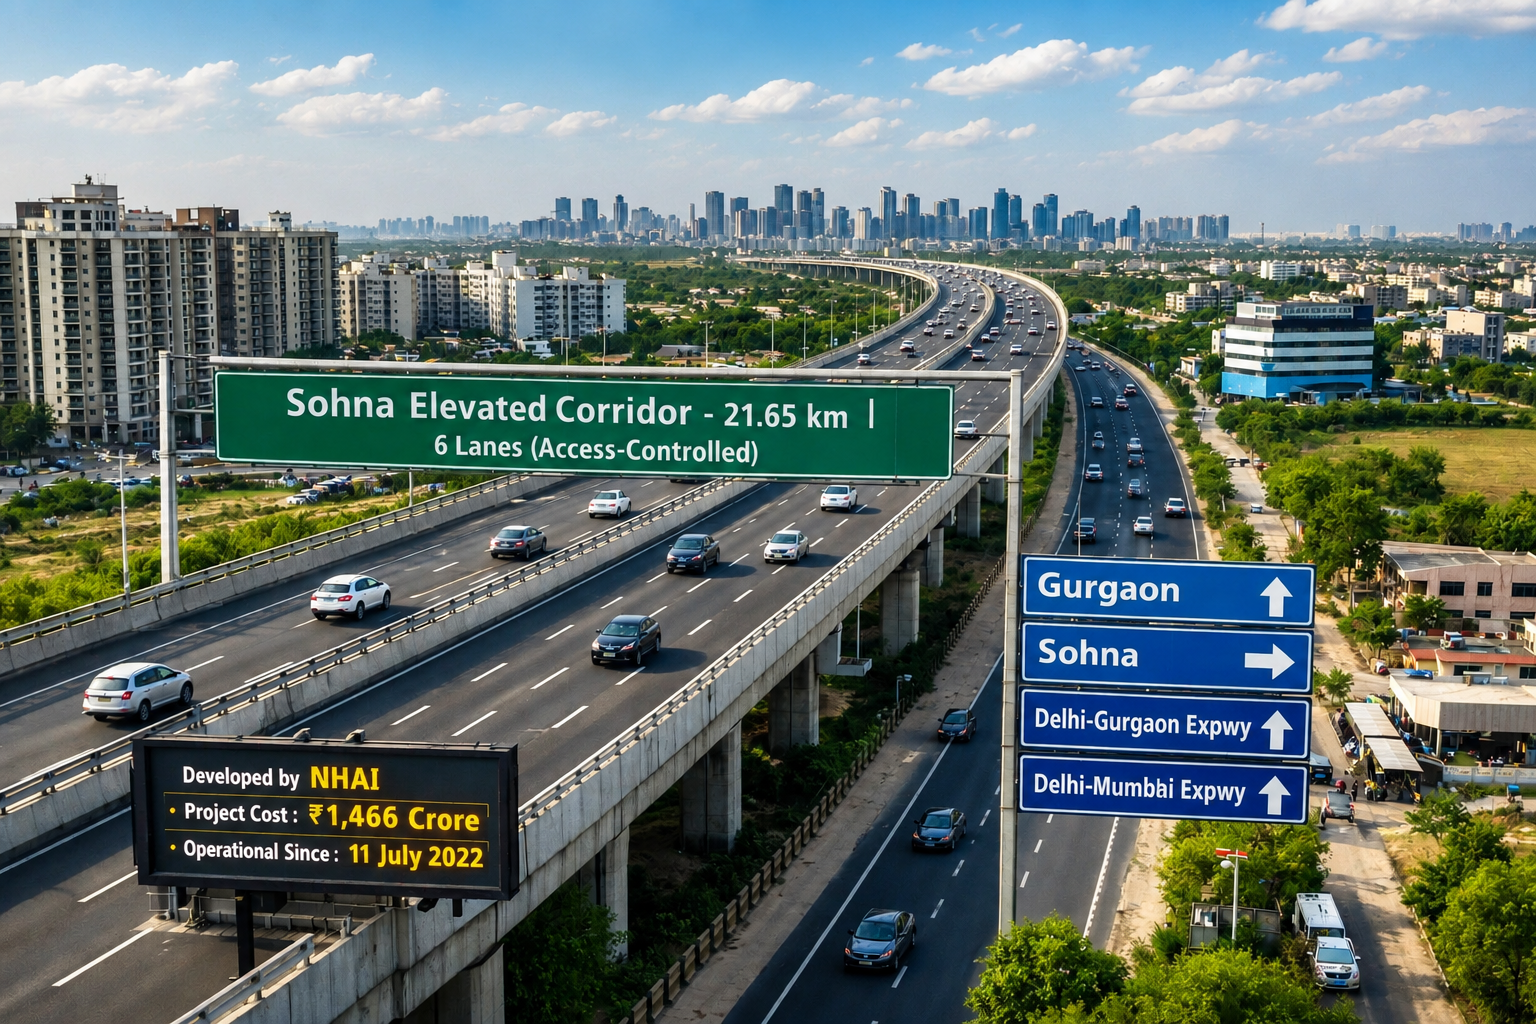
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
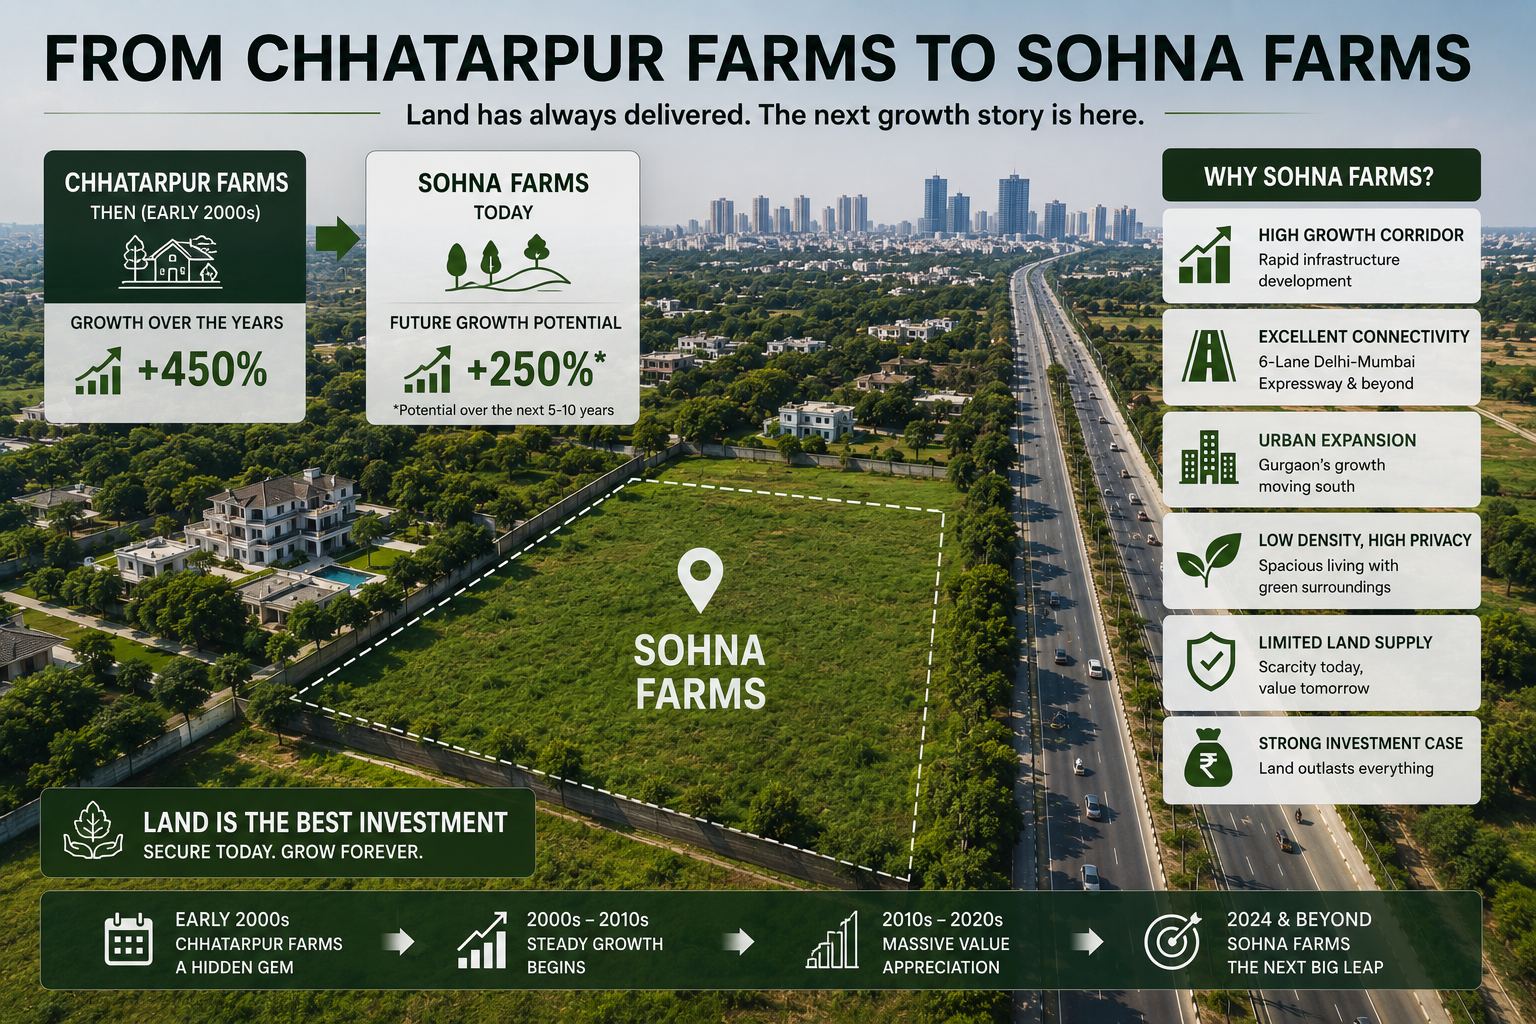
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
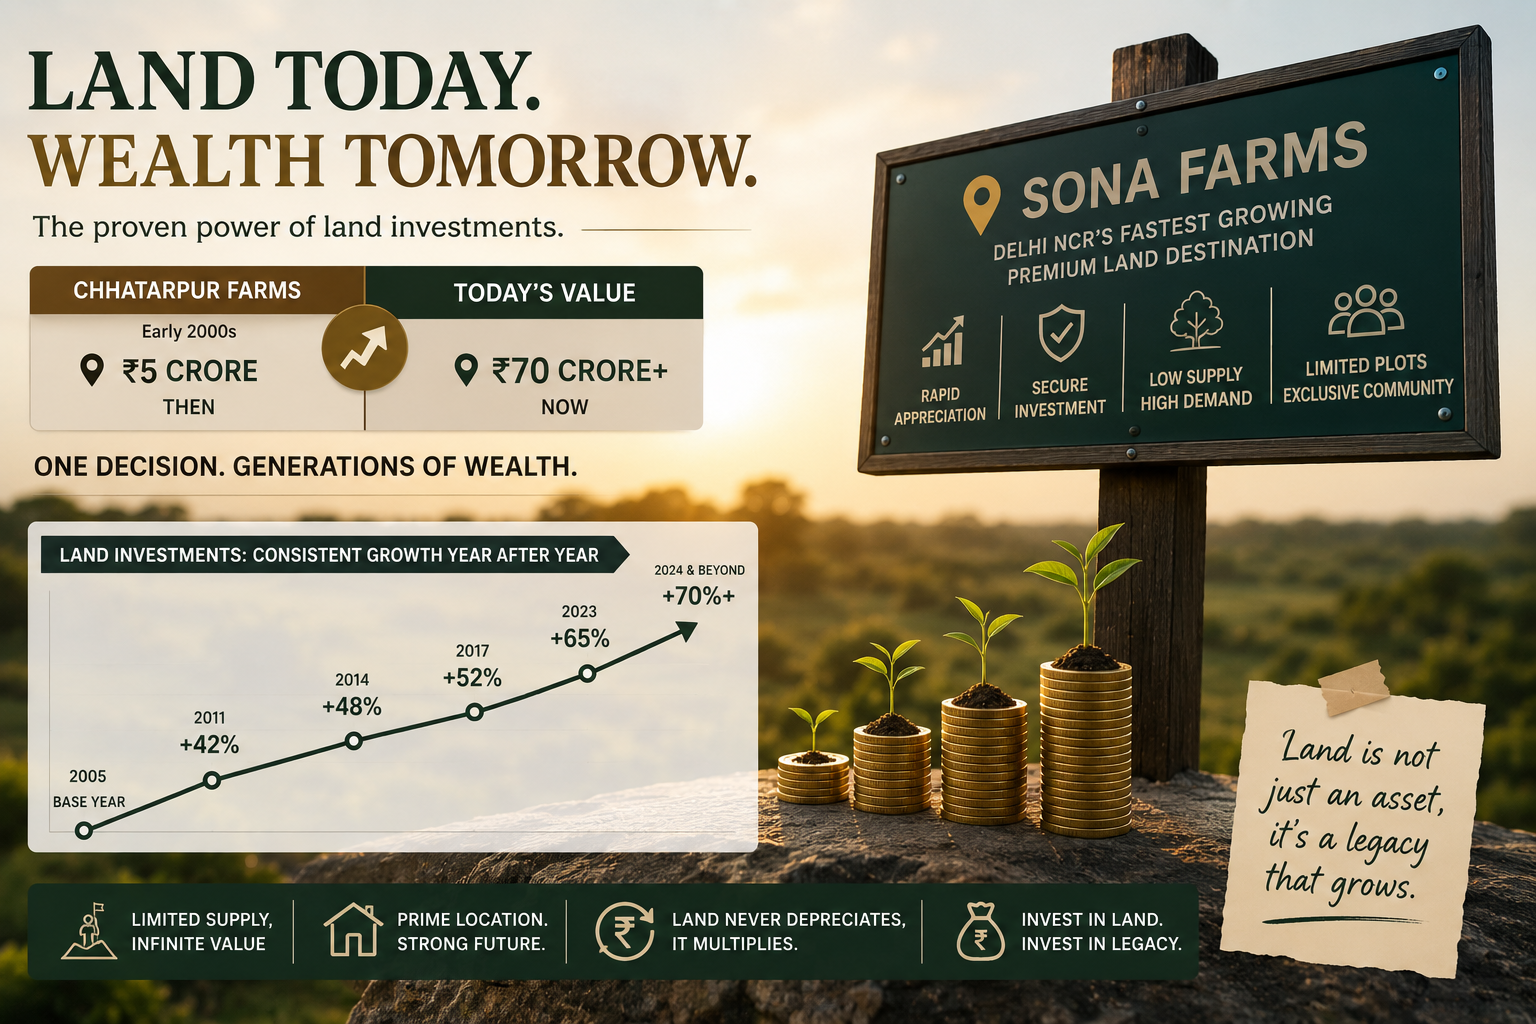
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.