The Persistent Digital Friction: Why Europe's Retail Fragmentation Persists
Despite a unified market vision and rising e-commerce penetration, the continent's digital retail landscape remains stubbornly fractured, presenting enduring challenges for growth and operational efficiency.

From the vast fulfilment centres of Zalando in Germany to the burgeoning marketplace of Allegro in Poland, and the entrenched local dominance of Bol.com in the Netherlands, Europe’s digital retail ecosystem has matured significantly over the past decade. Yet, beneath the headlines of rising online sales and technological adoption, a fundamental characteristic endures: fragmentation. While consumers increasingly expect seamless digital experiences, the logistical, regulatory, and cultural nuances across member states continue to complicate pan-European expansion for many retailers, limiting the scale efficiencies seen in other large markets.
The initial promise of a borderless digital single market has been met with the reality of diverse consumer preferences and operational complexities. A French consumer navigating Cdiscount or Carrefour online often encounters different product assortments and delivery options than an Italian browsing similar categories. Even within the grocery sector, where the pandemic accelerated digital adoption, players like REWE and Lidl operate distinct online strategies tailored to their respective national footprints, rather than a harmonised European model.
This regional disparity is not merely a matter of language. Varying data protection regimes, nuanced consumer protection laws, and disparate packaging waste regulations across the EU create significant compliance hurdles. A company shipping across the bloc must often navigate a patchwork of legal requirements, elevating operational costs and discouraging aggressive cross-border expansion, particularly for smaller and medium-sized enterprises. This regulatory mosaic stands in contrast to the more uniform environment of the United States or China, where scale can be achieved more readily.
The Logistics Labyrinth and Local Dominance
Logistics present another formidable barrier. Delivering goods from, say, Germany to Spain or a Nordic country involves navigating disparate postal services, last-mile delivery providers, and customs procedures, even within the customs union itself. The brief, high-growth periods of rapid delivery services like Gorillas and Flink, which ultimately faced challenges in consolidating their multi-market operations, underscore the difficulty of achieving true logistical synergy across diverse urban landscapes and consumer expectations. Local incumbents, deeply embedded in their national infrastructures, often retain a competitive edge.
Consumer behaviour further complicates the picture. While platforms like Vinted demonstrate the potential for successful cross-border commerce in specific niches, general merchandise often faces cultural preferences that vary widely. Payment methods, return policies, and brand loyalties differ substantially from one country to the next. What resonates with a German shopper may not appeal to a Spanish counterpart, necessitating localised marketing and product curation efforts that erode the benefits of a uniform digital storefront.
The ambition for a truly integrated digital European retail space often founders on the granular details of national idiosyncrasies and a fragmented regulatory terrain.
Investment Flows and Market Concentration
Despite these challenges, investment in European e-commerce remains robust, albeit often directed towards strengthening national champions or building niche platforms rather than fostering broad cross-border integration. The total value of European online retail transactions continues to grow, with annual figures often surpassing several hundred billion euros. Yet, this growth is frequently absorbed by entities that have mastered their domestic markets, leading to a landscape where market share remains relatively dispersed compared to more consolidated regions.
The implications extend beyond individual company balance sheets. A less integrated digital retail market can limit consumer choice, maintain higher price points due to reduced competitive pressure, and slow the pace of digital innovation. While the European Commission continues its efforts to harmonise digital rules and foster a single market, the inherent complexities of a continent composed of numerous distinct cultures and legal systems mean that true digital fluidity remains an aspiration rather than a widespread reality. The persistent friction embedded in cross-border operations underscores a fundamental tension: the pursuit of continental unity against the powerful forces of national particularity.
Therefore, as retailers look to future growth, a nuanced understanding of these underlying structural impediments, rather than a blanket assumption of an ever-flattening digital world, will be crucial for strategic success. Navigating the continent's digital landscape demands a sophisticated approach, acknowledging that while Europe shares a currency and many common aspirations, its retail markets are still very much defined by their distinct national contours.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
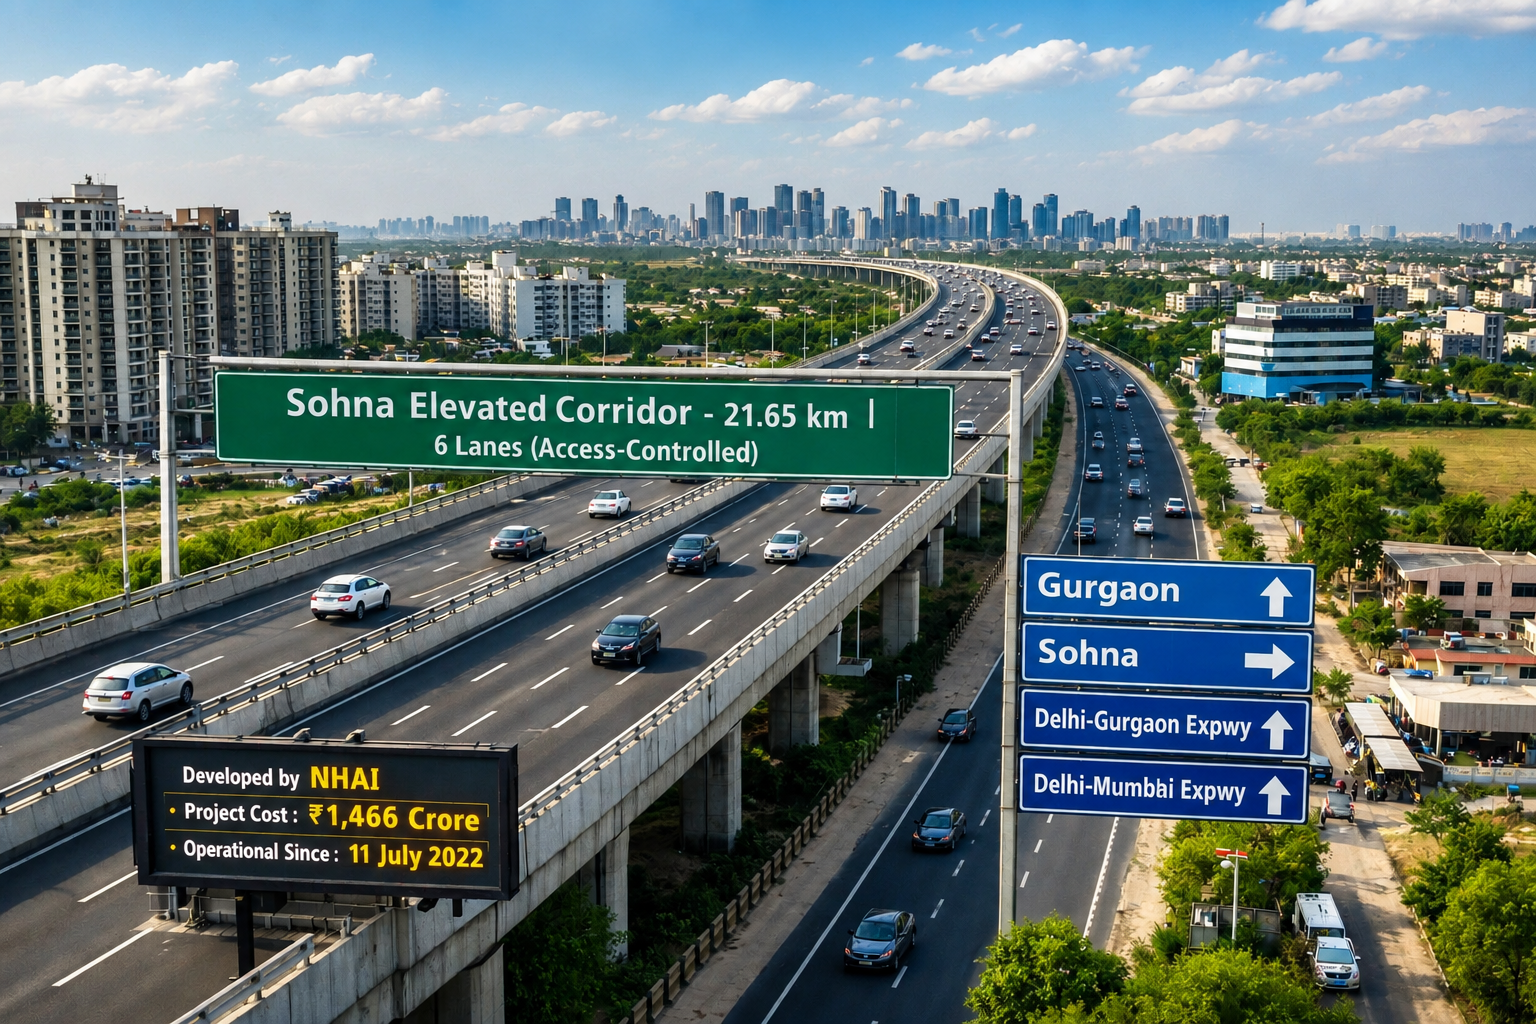
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
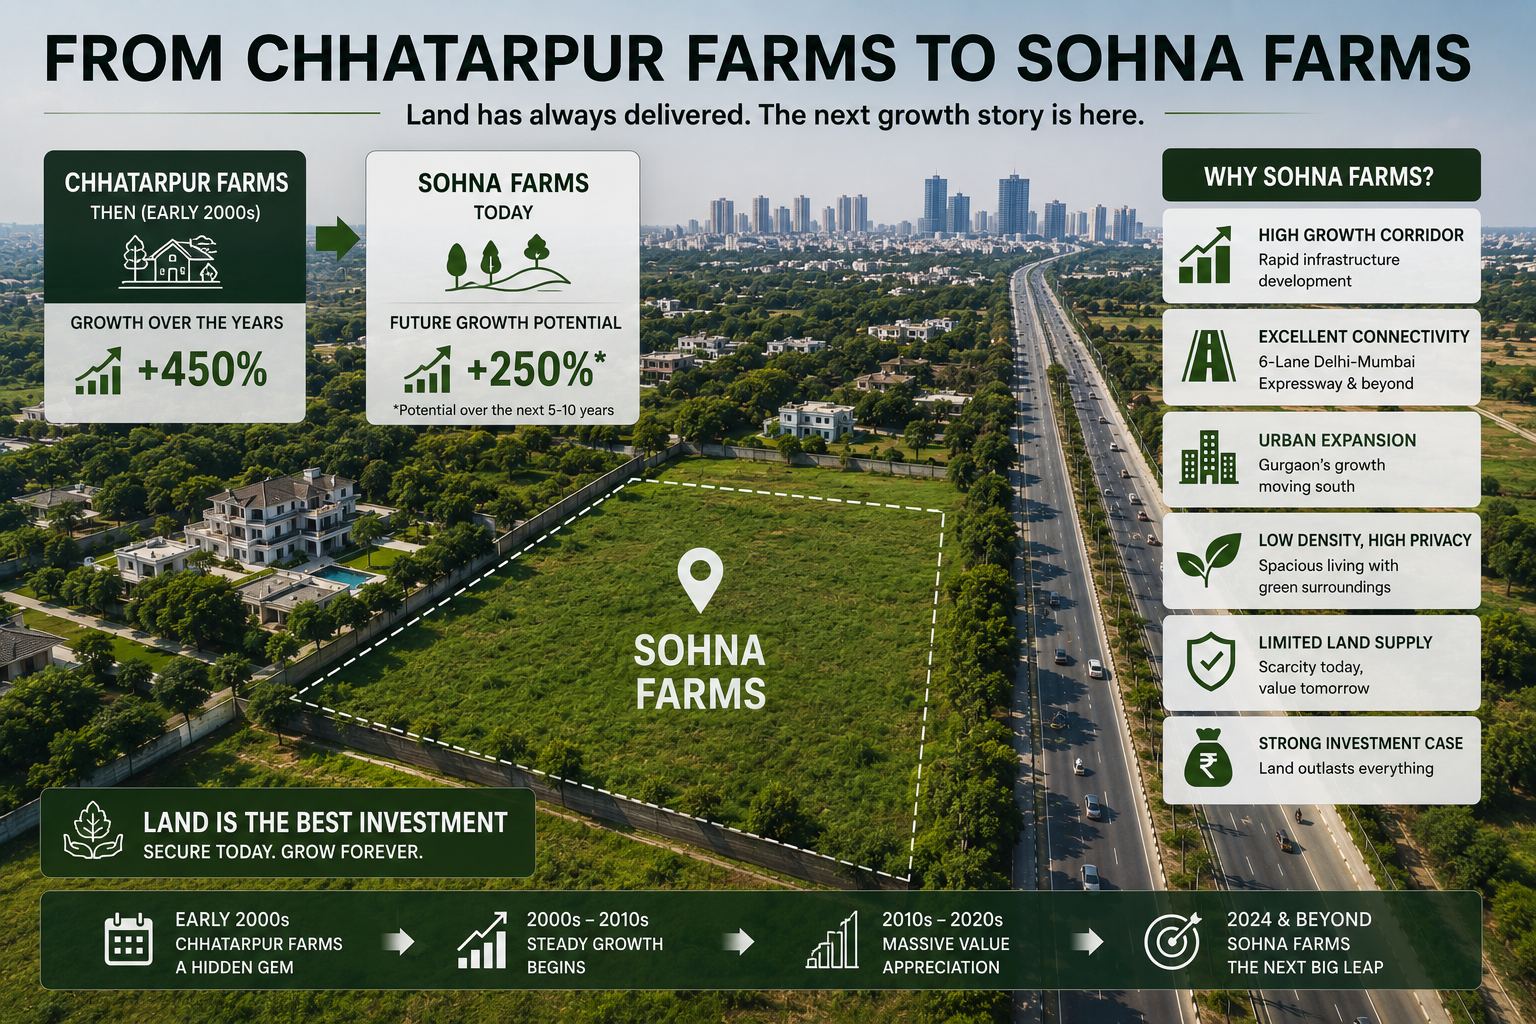
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
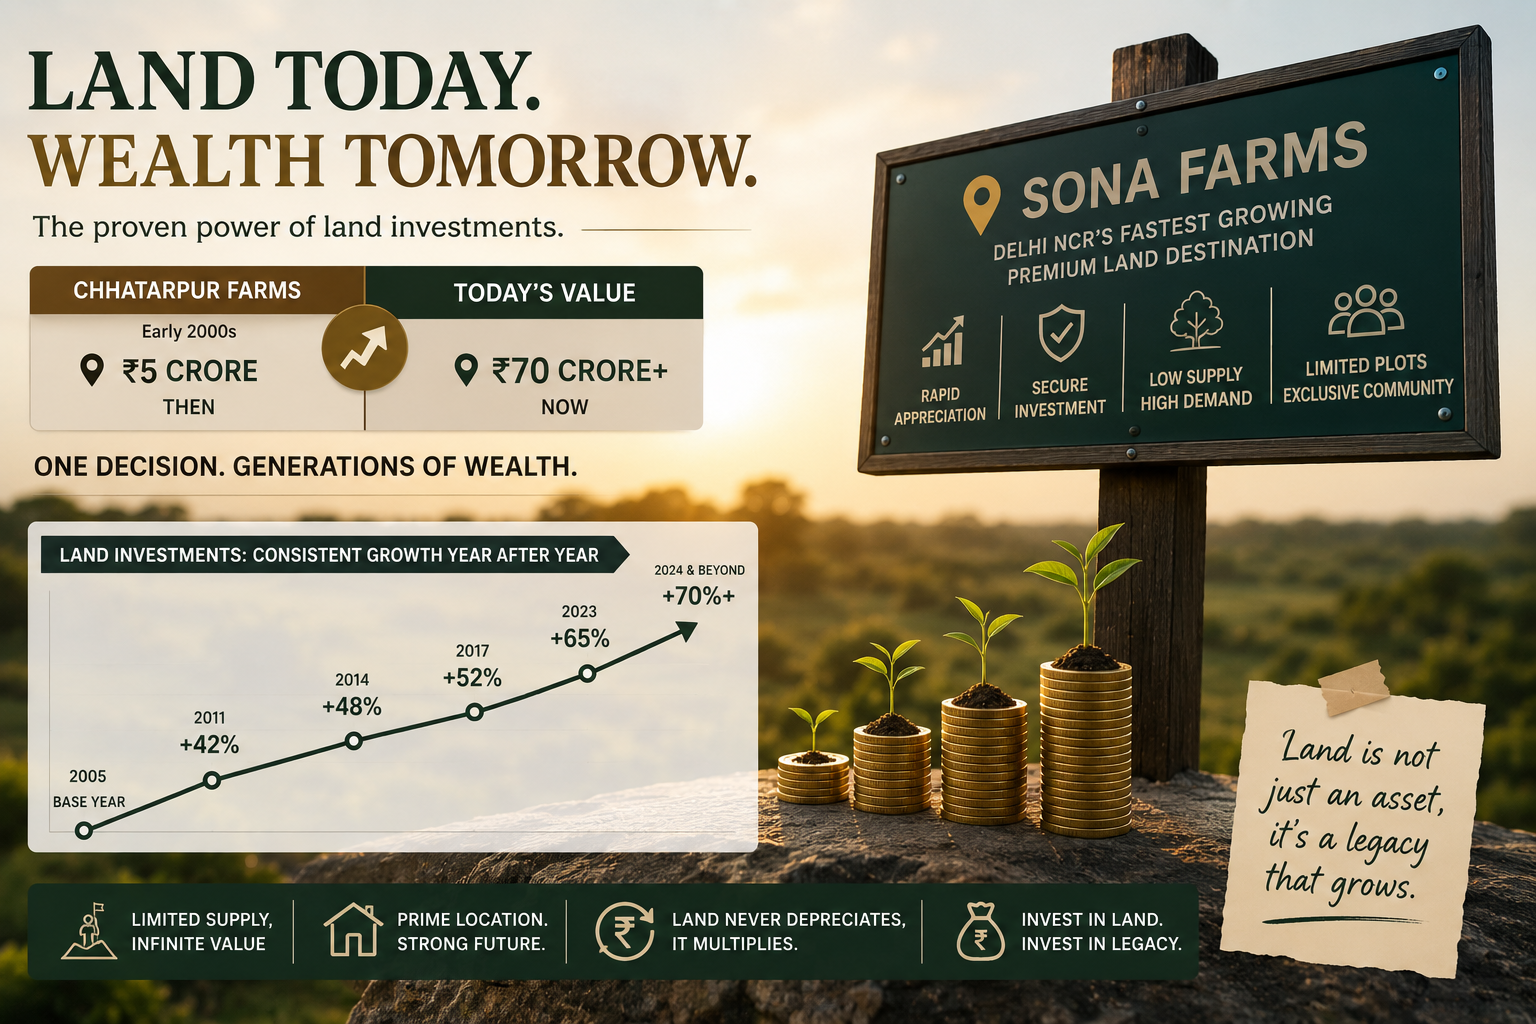
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.