The Quiet Retreat from Micro-Hubs: How British Grocers Recaptured the Final Mile
The speculative frenzy over twenty-minute grocery delivery has receded into British retail orthodoxy, turning traditional supermarket aisles into default dispatch points for app-based aggregators.

At dawn inside a suburban Sainsbury’s in south-west London, the early traffic through the aisles belongs not to early-morning commuters or shelf-stackers, but to store colleagues manoeuvring handheld scanners. They are picking chilled ready meals, artisan loaves, and ambient pantry goods into colour-coded tote bags for couriers waiting outside. This quiet repurposing of the retail sales floor illustrates how decisively the logistics of rapid British commerce have shifted over the past twenty-four months. The existential threat posed by well-funded, dark-store operators has collapsed, leaving legacy grocers in uncontested possession of the urban perimeter.
During the height of the venture capital boom, pure-play rapid delivery networks wagered hundreds of millions of pounds on dedicated micro-warehouses situated in railway arches and light-industrial parks across Britain's major cities. That premise failed under the weight of commercial rents, high customer acquisition outlays, and soaring debt charges. Rather than creating bespoke infrastructure from scratch, the rapid channel has defaulted back to the established estate. Deliveroo, Just Eat, and Uber Eats now function less as disruptive merchants and more as outsourced fleet managers for the established retail aristocracy.
The store as dispatch centre
The operational calculus behind this retreat is straightforward. A traditional supermarket already pays the lease, absorbs the energy tariffs, and maintains the cold chain on tens of thousands of product lines. Tesco, through its proprietary Whoosh service, and Sainsbury’s, via distribution agreements with delivery platforms, have turned physical branches into dual-purpose assets. Picking an order off a public shelf involves higher labour friction than pulling from an automated grid, but it avoids the catastrophic fixed overhead that doomed standalone rapid-delivery operators across London, Manchester, and Birmingham.
This hybrid approach exposes a clear structural divide in UK logistics strategy. Ocado, whose automated customer fulfilment centres represent the technological pinnacle of British e-commerce, continues to dominate high-value, scheduled weekly shops alongside joint-venture partner Marks & Spencer. Yet even Ocado has discovered the limits of its massive, centralised robotic sheds in Erith and Andover when attempting to satisfy unplanned, on-demand purchases. Meeting the consumer within thirty to sixty minutes requires physical proximity that centralised automated sheds cannot provide without satellite depots.
The reckoning on basket economics
The British supermarket did not need to outbuild venture-backed delivery networks; it simply waited for their cost of capital to mirror its own.
The challenge for British retail logistics now lies in margin protection. Grocers cannot afford to subsidise the final mile indefinitely. While apparel merchants such as Next and ASOS have brought harsh discipline to their logistics pipelines by instituting return fees and parcel collection charges, grocers are walking a finer line. They must balance delivery fees of £2.50 to £4.50 against subtle product price premiums on third-party aggregators without alienating a consumer base fatigued by several years of food price inflation.
For Deliveroo and Just Eat, British supermarkets have provided a hedge against softening restaurant takeaway volumes, contributing high-frequency, daylight transactions that smooth out courier utilisation. For the grocers, the arrangement offers incremental turnover without the risk of capital expenditure on bespoke urban warehouses. The lasting consequence of the rapid delivery experiment is not a new logistical paradigm, but a commercial realignment: the mid-sized British supermarket has preserved its role as the dominant logistics nexus of the neighbourhood.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
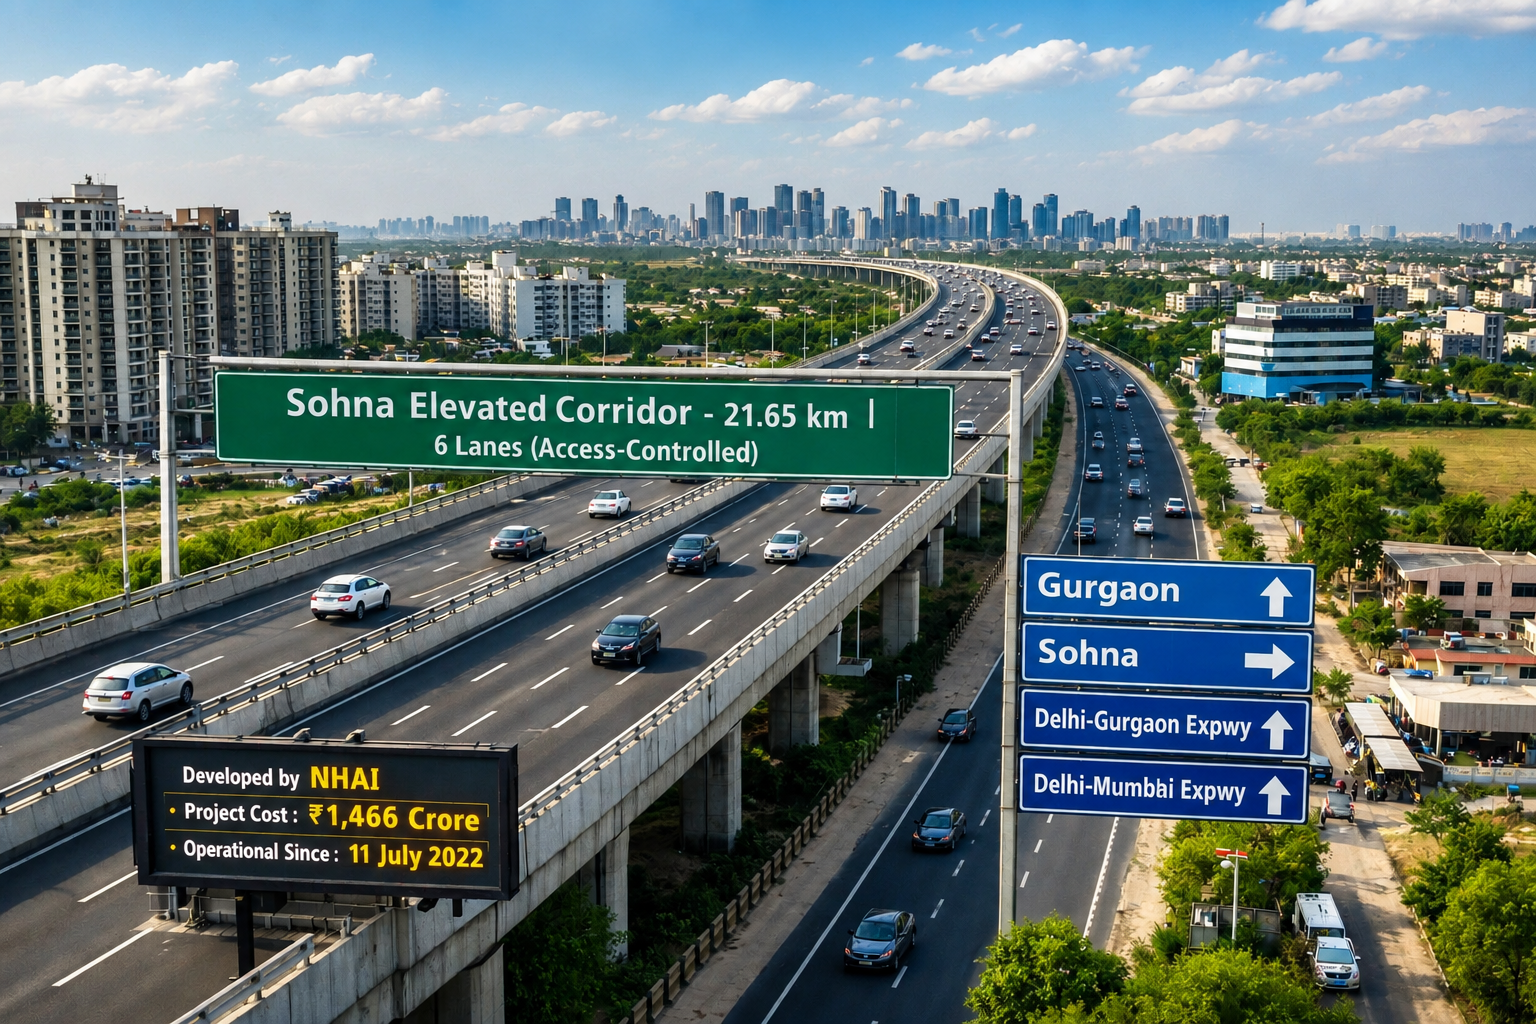
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
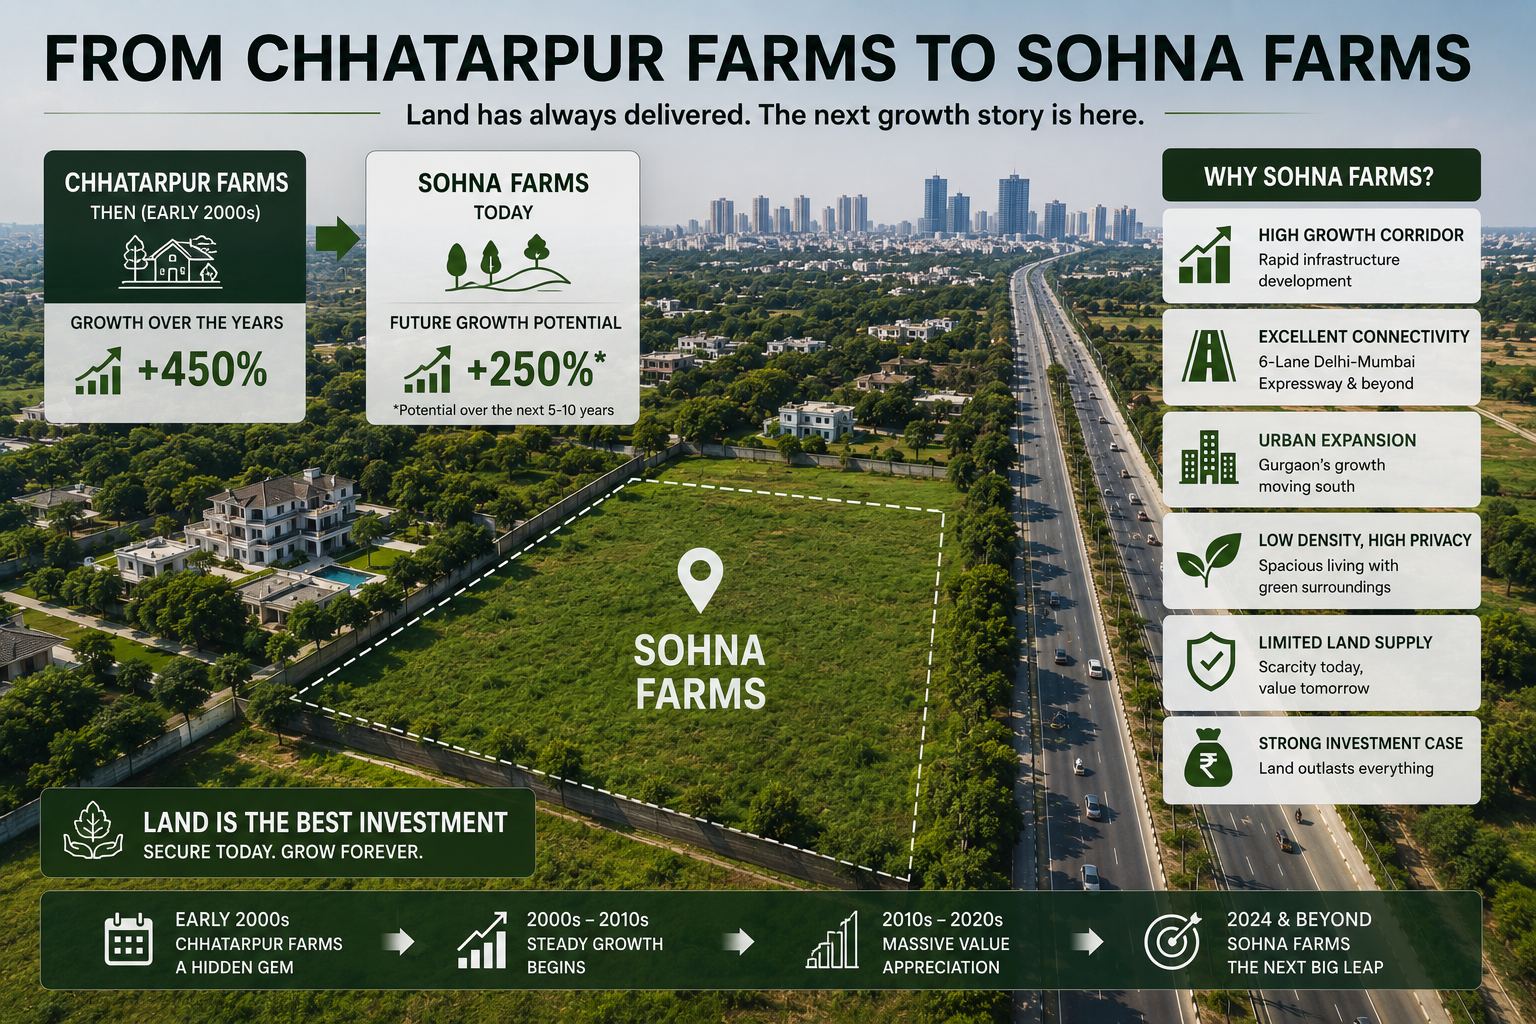
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
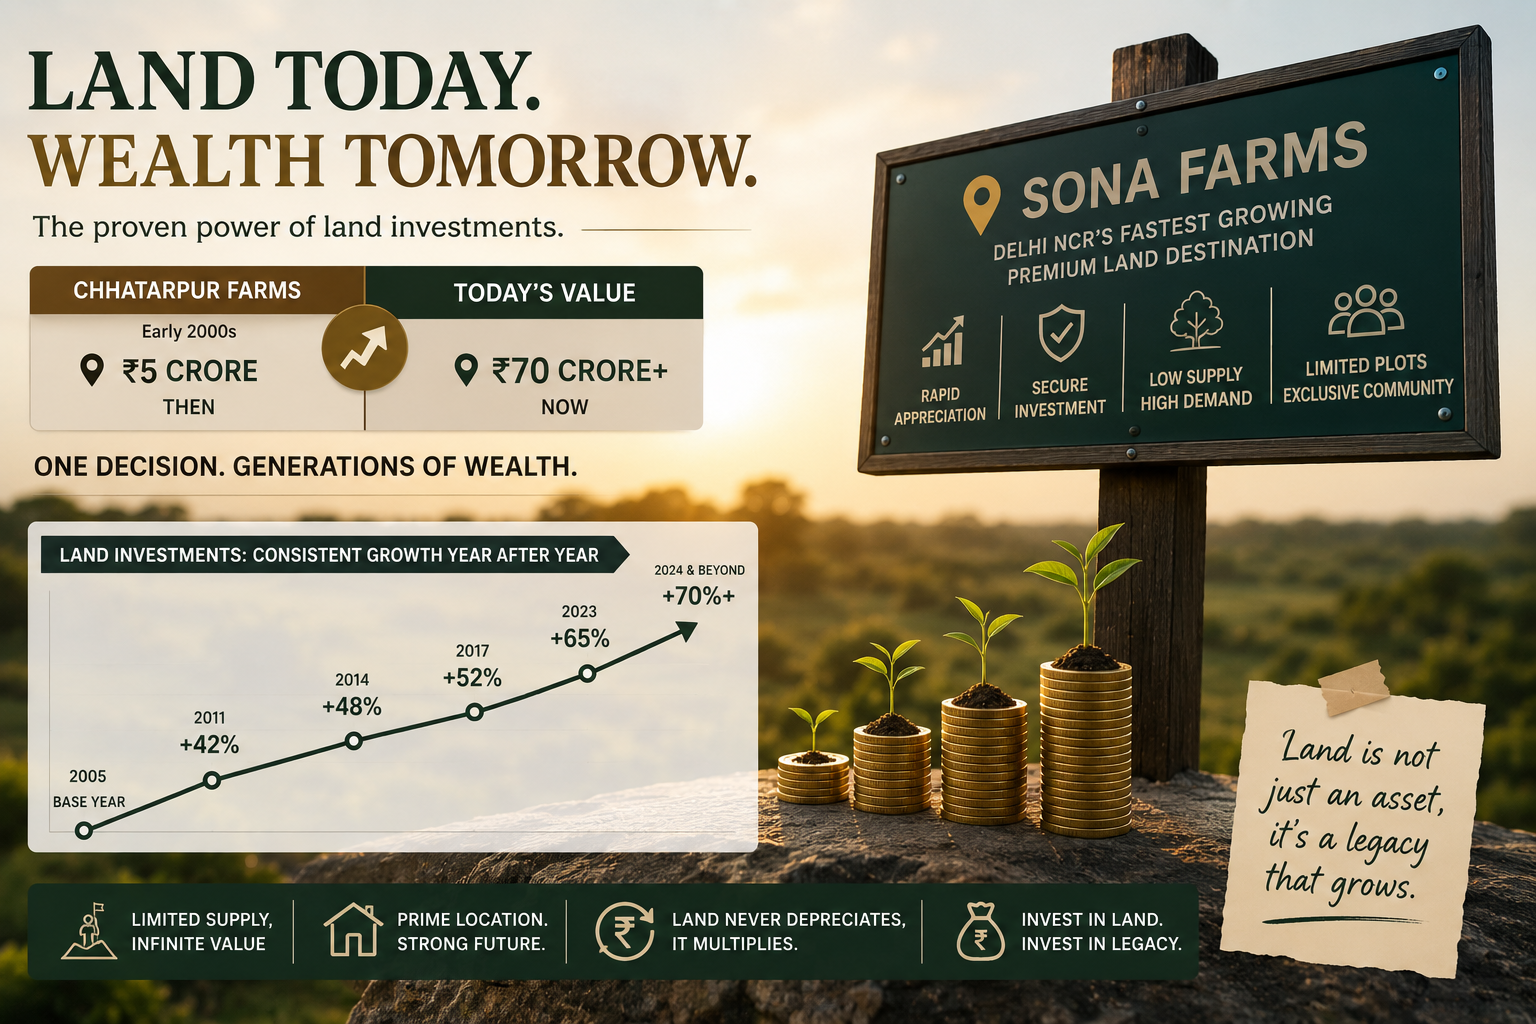
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.