The Scramble for Europe's Digital Shelf: Retail Startups Grapple with Maturity and Local Loyalties
Venture capital funding for rapid expansion has waned, forcing a strategic reckoning for a generation of European e-commerce and quick commerce ventures. Surviving this new phase demands acute market understanding and operational discipline.

The distinctive teal livery of a Flink delivery rider, once a ubiquitous sight in Berlin, is now less common. While still operational in key German cities, the company's trajectory, along with that of its quick commerce predecessor Gorillas, illustrates a broader shift across the European retail startup landscape. The era of expansive, capital-intensive growth, fuelled by investor enthusiasm for market share above all else, appears to be drawing to a close, ushering in a period defined by consolidation and a renewed focus on profitability.
For several years, the European market, fragmented by language, regulation, and consumer preference, offered fertile ground for venture-backed disruptors. From fashion resales championed by Lithuania's Vinted to grocery delivery services that promised near-instant gratification, startups carved niches by leveraging technology and promising convenience. Billions of euros flowed into these ventures, allowing for aggressive pricing strategies and extensive marketing campaigns designed to capture first-mover advantage.
The Waning Tide of Venture Capital
The recalibration began in earnest around 2022. Global economic headwinds, rising interest rates, and a more cautious investor sentiment curtailed the free flow of capital that had underpinned rapid scaling. Companies like Gorillas, once valued in the billions, were acquired for significantly less, while others faced severe downscaling or outright closure. This has compelled remaining players to fundamentally re-evaluate their business models, shifting from growth at any cost to sustainable operations.
This shift is particularly evident in quick commerce, where the high operational costs associated with dark stores and rapid delivery times proved challenging to sustain without continuous cash injections. While services persist, particularly in dense urban centres where demand justifies the model, the continent-wide land grab has ceased. Companies now seek to optimise existing operations rather than launch in every major city from Marseille to Munich.
The transition from 'blitzscaling' to disciplined unit economics marks a crucial maturation point for Europe's digital retail sector.
Traditional European retail giants are also observing this evolution closely. Established players such as Carrefour in France, REWE and Lidl in Germany, and Spain's Mercadona have observed the startup playbook. They are now integrating last-mile delivery and digital storefronts into their own expansive networks, leveraging existing supply chains and brand loyalty to offer competitive online propositions. This creates a challenging environment for startups that once solely occupied the digital space.
Localised Strength Against Pan-European Ambitions
The fragmented nature of the European market continues to present a significant hurdle for any single entity aiming for dominance. While pan-European players like Zalando in fashion and Amazon in general merchandise have achieved considerable scale, even they encounter distinct competitive dynamics in different territories. The success of Poland's Allegro, largely dominant in its domestic market, or Bol.com, a major force in the Netherlands and Belgium, underscores the enduring power of localised market understanding and established brand trust.
For new entrants, succeeding now means navigating a complex web of national consumer behaviours, regulatory frameworks, and local competitor strength. A strategy effective in Germany, with its strong discount supermarket culture, may not translate directly to Italy, where traditional grocery shopping habits persist. This necessitates highly adaptable business models and significant investment in regional expertise, rather than a one-size-fits-all approach.
The path forward for European retail startups increasingly involves a dual focus: achieving clear profitability within core markets and carefully selecting expansion opportunities based on rigorous financial projections. Strategic partnerships, mergers, and acquisitions may become more prevalent as companies seek synergies and economies of scale, further reshaping the competitive landscape. The ambition to digitise Europe's commerce remains, but the execution now demands prudence over sheer speed.
The lessons learned from the recent investment cycle will likely foster a more resilient generation of retail enterprises, albeit ones that build their foundations with greater fiscal discipline. The digital transformation of European retail continues, yet the journey is now less about explosive growth and more about sustainable evolution.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
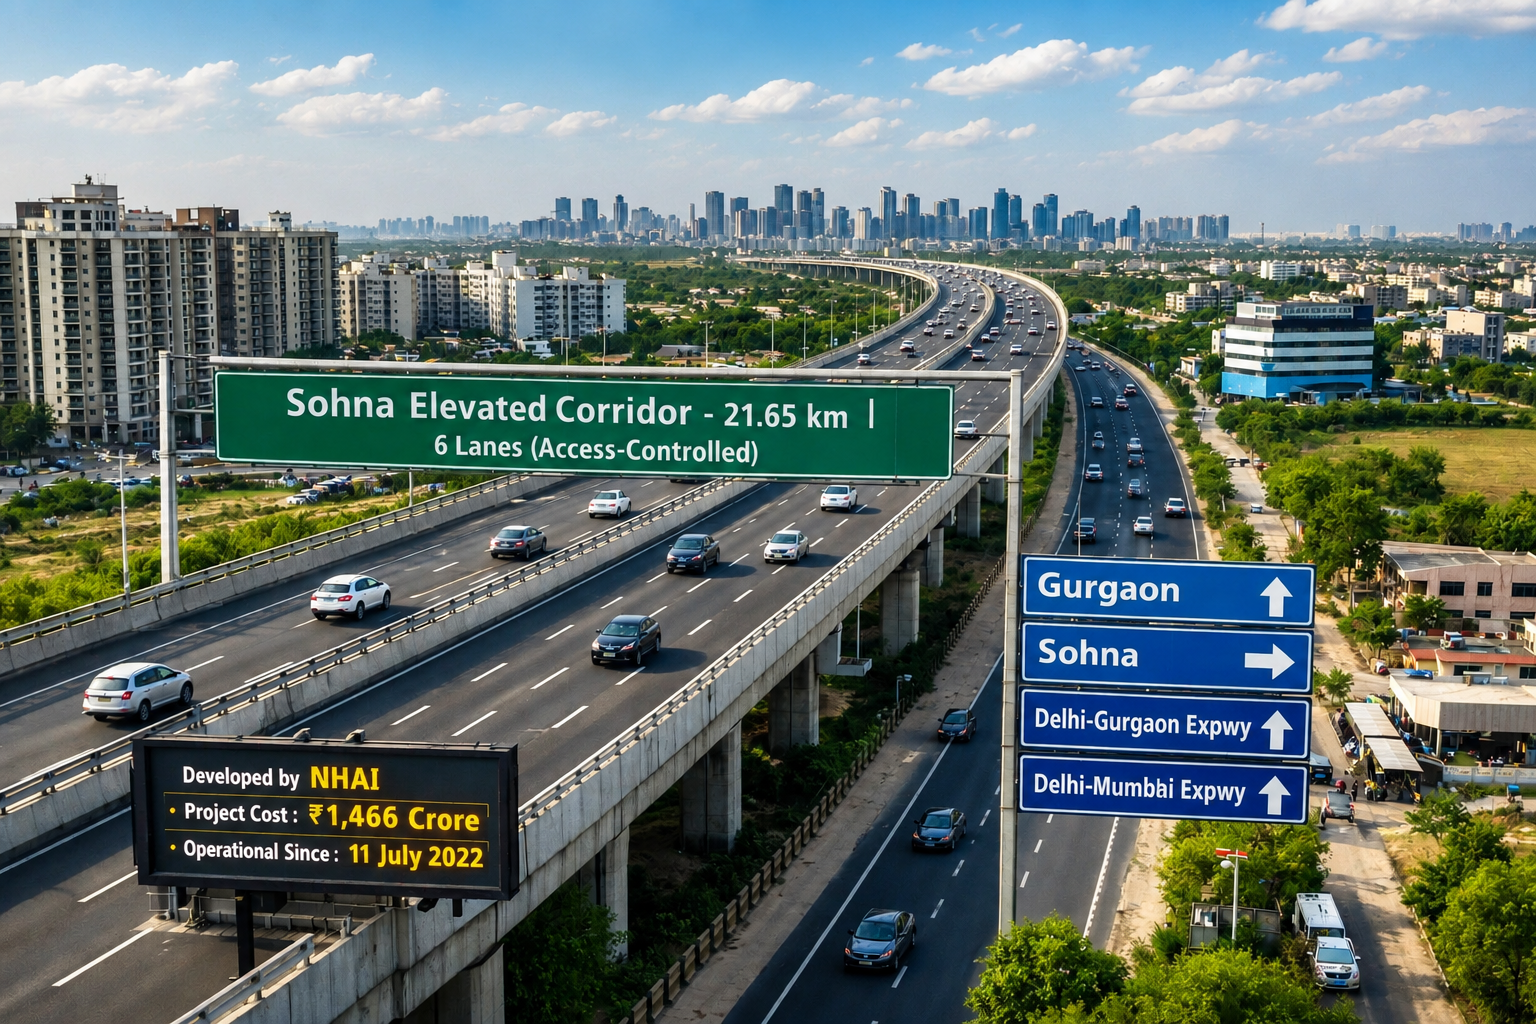
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
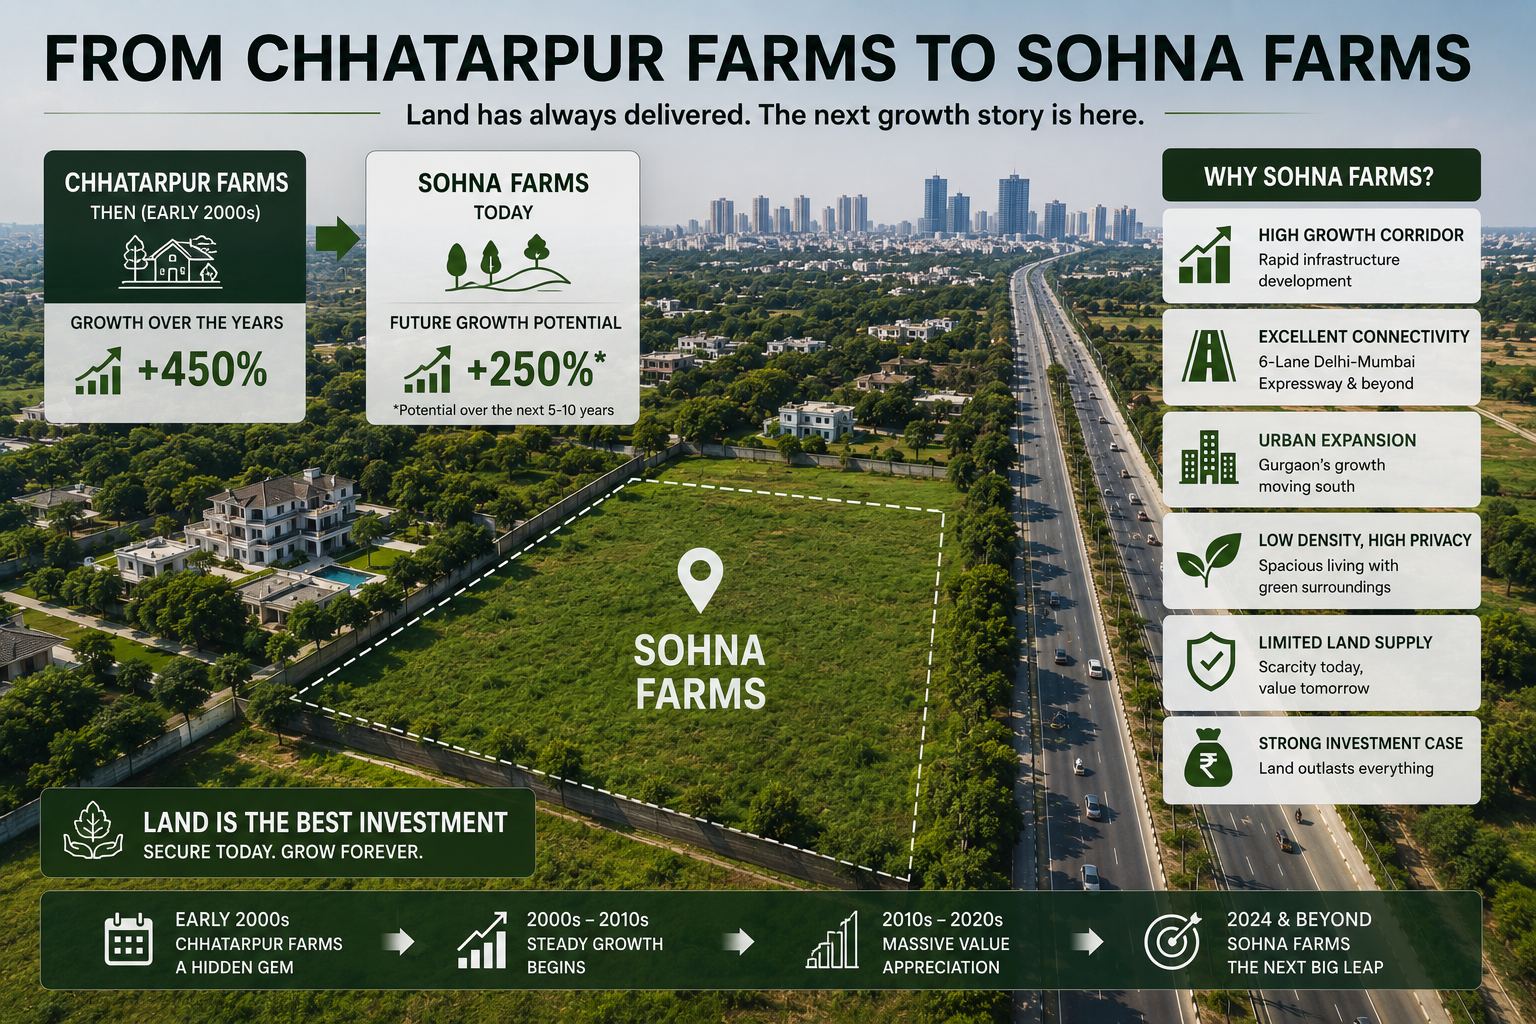
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
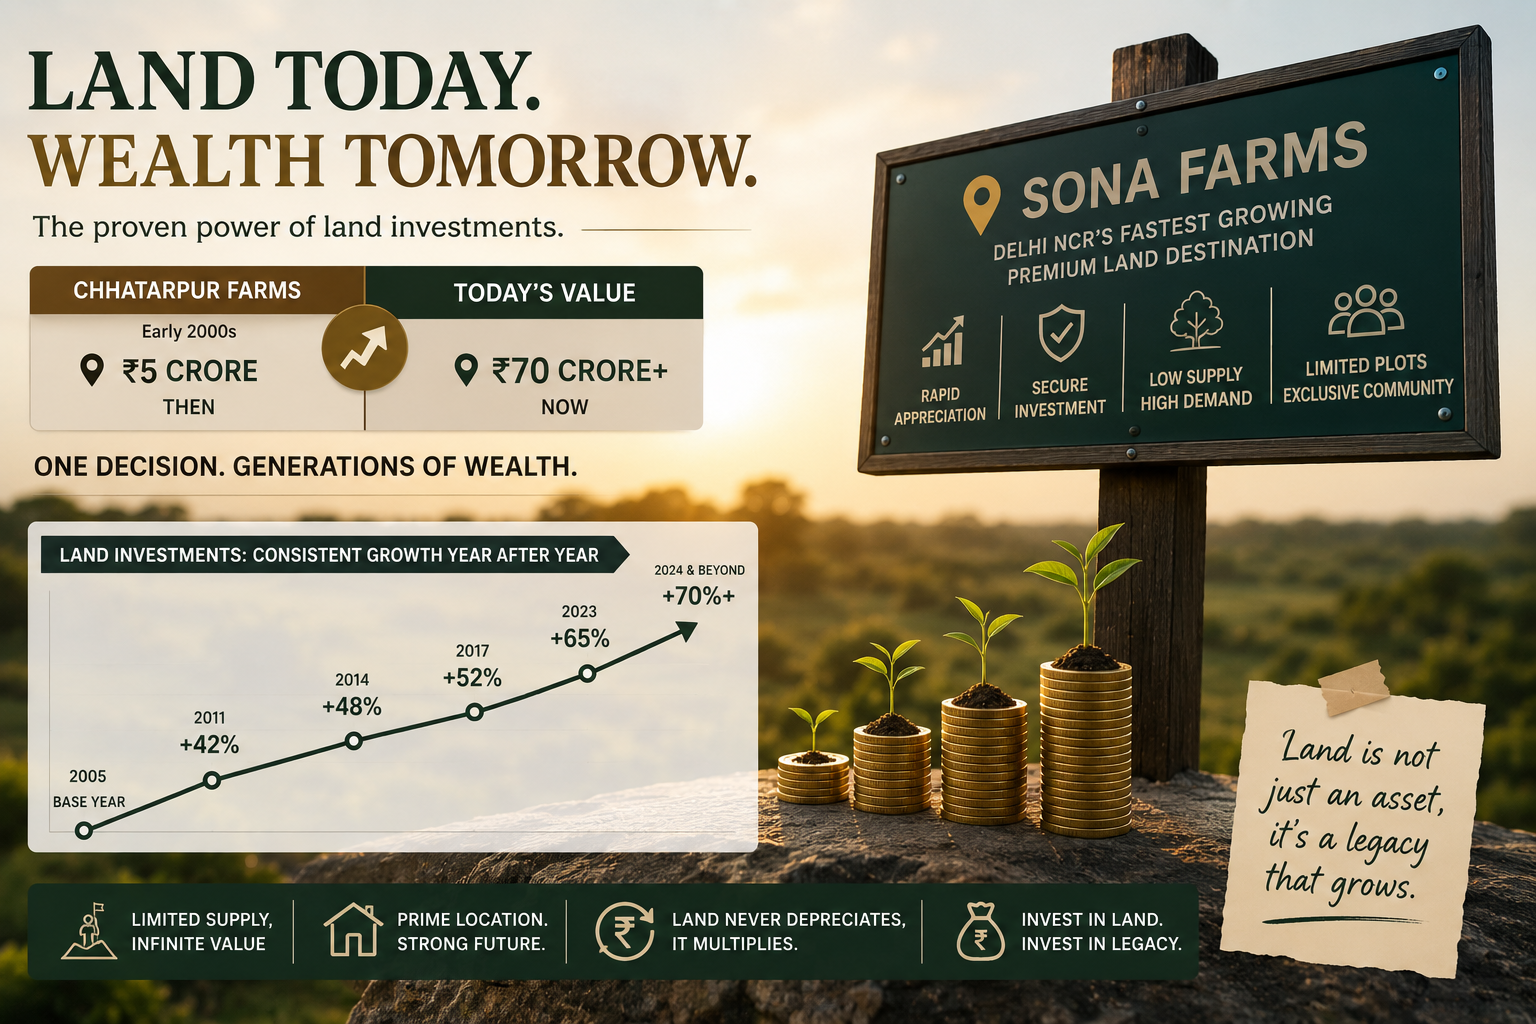
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.