The Sovereign Cart: Why Continental Europe Refuses a Single Digital Storefront
National marketplace champions, dense discount grocers and cross-border thrift networks have checked the ambitions of universal retail platforms across the continent.

In a distribution facility outside Poznań, automated sorters route parcels not into the logistics apparatus of a global tech conglomerate, but into the domestic network of Allegro, which still anchors the majority of Polish online trade. Five hundred kilometres west in Berlin, an apparel shopper balances checkout tabs between Zalando's domestic returns portal and peer-to-peer listings on Vinted, before collecting staple groceries from a neighbourhood REWE or Lidl. The long-predicted consolidation of European consumer commerce into a single, borderless digital storefront has failed to materialise. Instead, the continent has built a resilient mosaic of national platforms, discount grocers and second-hand exchanges.
Continental Europe remains an archipelago of ingrained local retail habits. Where American households concentrated their spend behind single-ecosystem subscriptions, Dutch and Flemish consumers continue to direct digital volume to Bol, while French shoppers divide their loyalty between Cdiscount and Carrefour's established click-and-collect drive lanes. These divides are structural rather than sentimental. In Germany, lingering consumer attachment to open-invoice payment and rigorous statutory return windows forced Zalando to construct bespoke reverse-logistics infrastructure that foreign entrants struggle to replicate. In Spain and Italy, cash preferences and high parcel-locker density continue to frustrate standardised delivery models.
The Thrift Corridor and the Discount Floor
Yet cross-border commerce has not stalled; it has simply organised itself around distinct consumer priorities. Vilnius-founded Vinted has quietly become one of the single market's most effective cross-border trading mechanisms, linking wardrobes in Lyon to buyers in Madrid and Warsaw through agreements with local carrier networks. The platform's success demonstrates that European shoppers are willing to navigate cross-border trade when clear economic value balances out the friction of delivery across borders.
Concurrently, the inflationary shocks of recent years have entrenched the physical discount supermarket as the bedrock of household budgets. The venture-backed quick-commerce wave—characterised by the costly collapse of Gorillas and the retrenchment of Flink across core German and Dutch metropolises—surrendered territory to incumbent operators with authentic supply-chain leverage. Private-label programmes at Lidl and Carrefour expanded market share not through algorithmic novelty, but by using dense physical real estate to shield consumers from peak food inflation.
European retail integration has advanced not through universal storefronts, but along the pragmatic routes of second-hand exchanges and parcel-locker networks.
The underlying unit economics of cross-border fulfilment explain why national boundaries persist. Moving a thirty-euro apparel parcel from a centralised warehouse in Saxony to a household in Milan incurs disparate motorway tolls, national postal surcharges and fragmented handling standards. For domestic operators, defending core territory has yielded far healthier margins than pursuing speculative pan-European expansion. Bol's disciplined focus on the Low Countries has insulated its balance sheet from the cash-burn that plagued broader platform projects.
Pragmatism Over Monolithic Scale
Regulatory pressure from Brussels has reinforced this regional fragmentation. Compliance demands under digital platform rules, coupled with tightening circular-economy directives on packaging waste and textile destruction, have raised the cost of predatory platform pricing. Regional players already accustomed to member-state labour laws and environmental oversight operate with less structural disadvantage than scale-first competitors might assume.
The result is a European shopping culture defined by deliberate pragmatism. Households assemble their weekly expenditure across an eclectic portfolio of channels: dry goods from hard discounters, domestic electronics from regional specialists, and wardrobe churn through secondhand corridors. Those who anticipated a winner-take-all resolution to European commerce underestimated the enduring power of regional infrastructure and language. The continental basket remains sovereign, and stubbornly federated.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
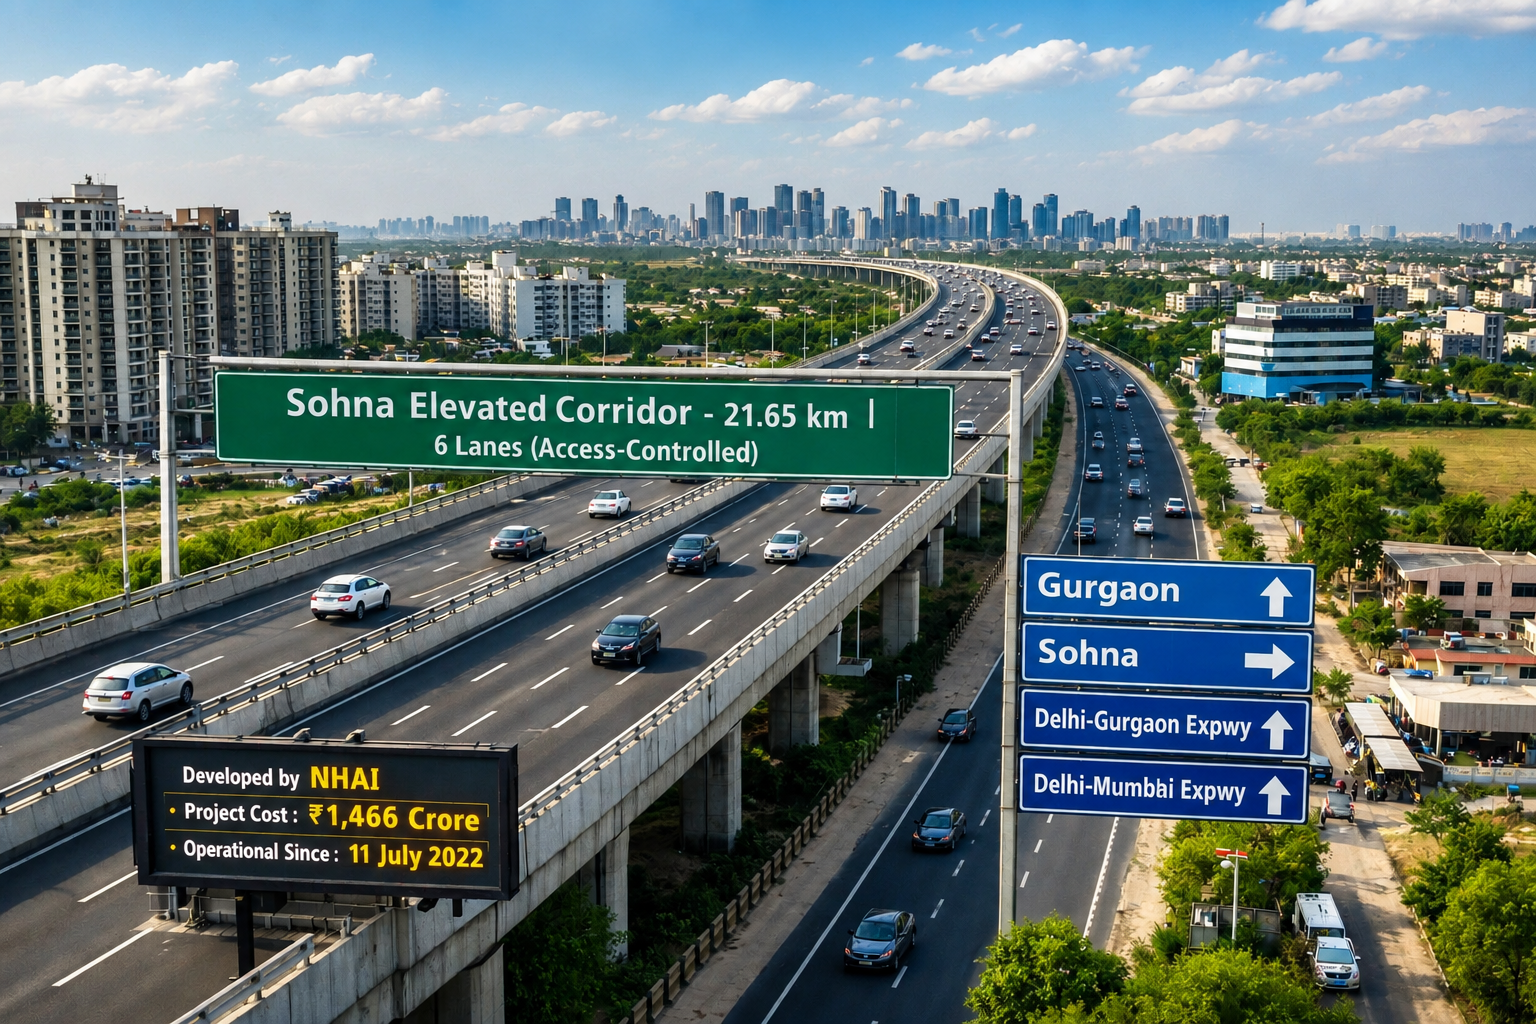
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
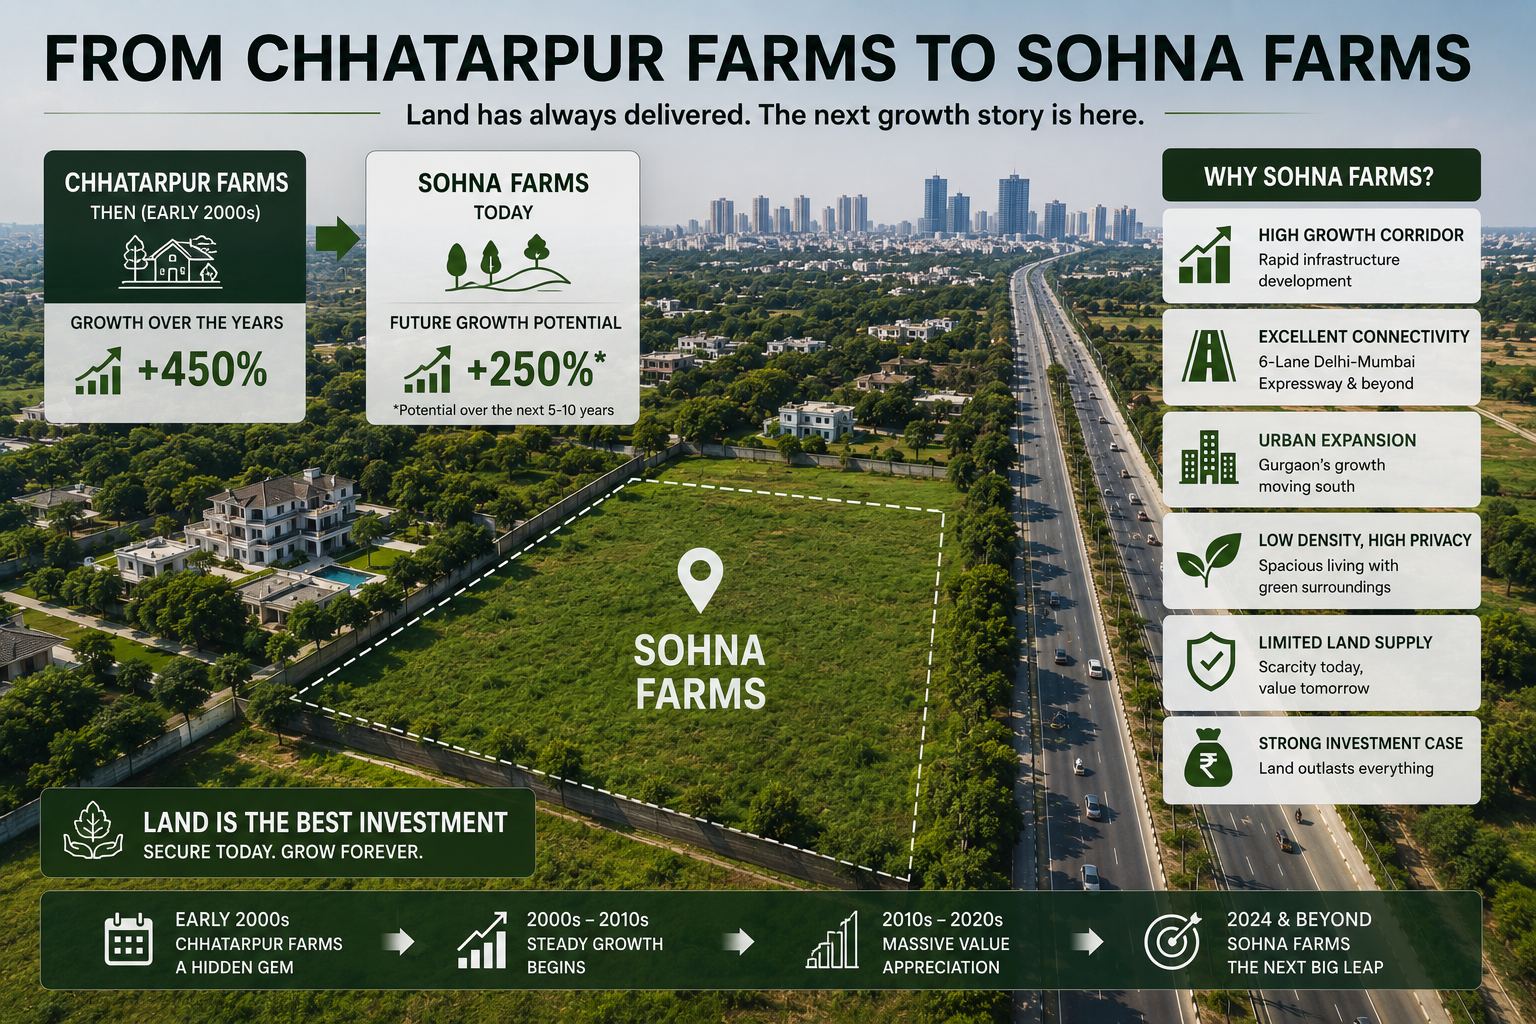
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
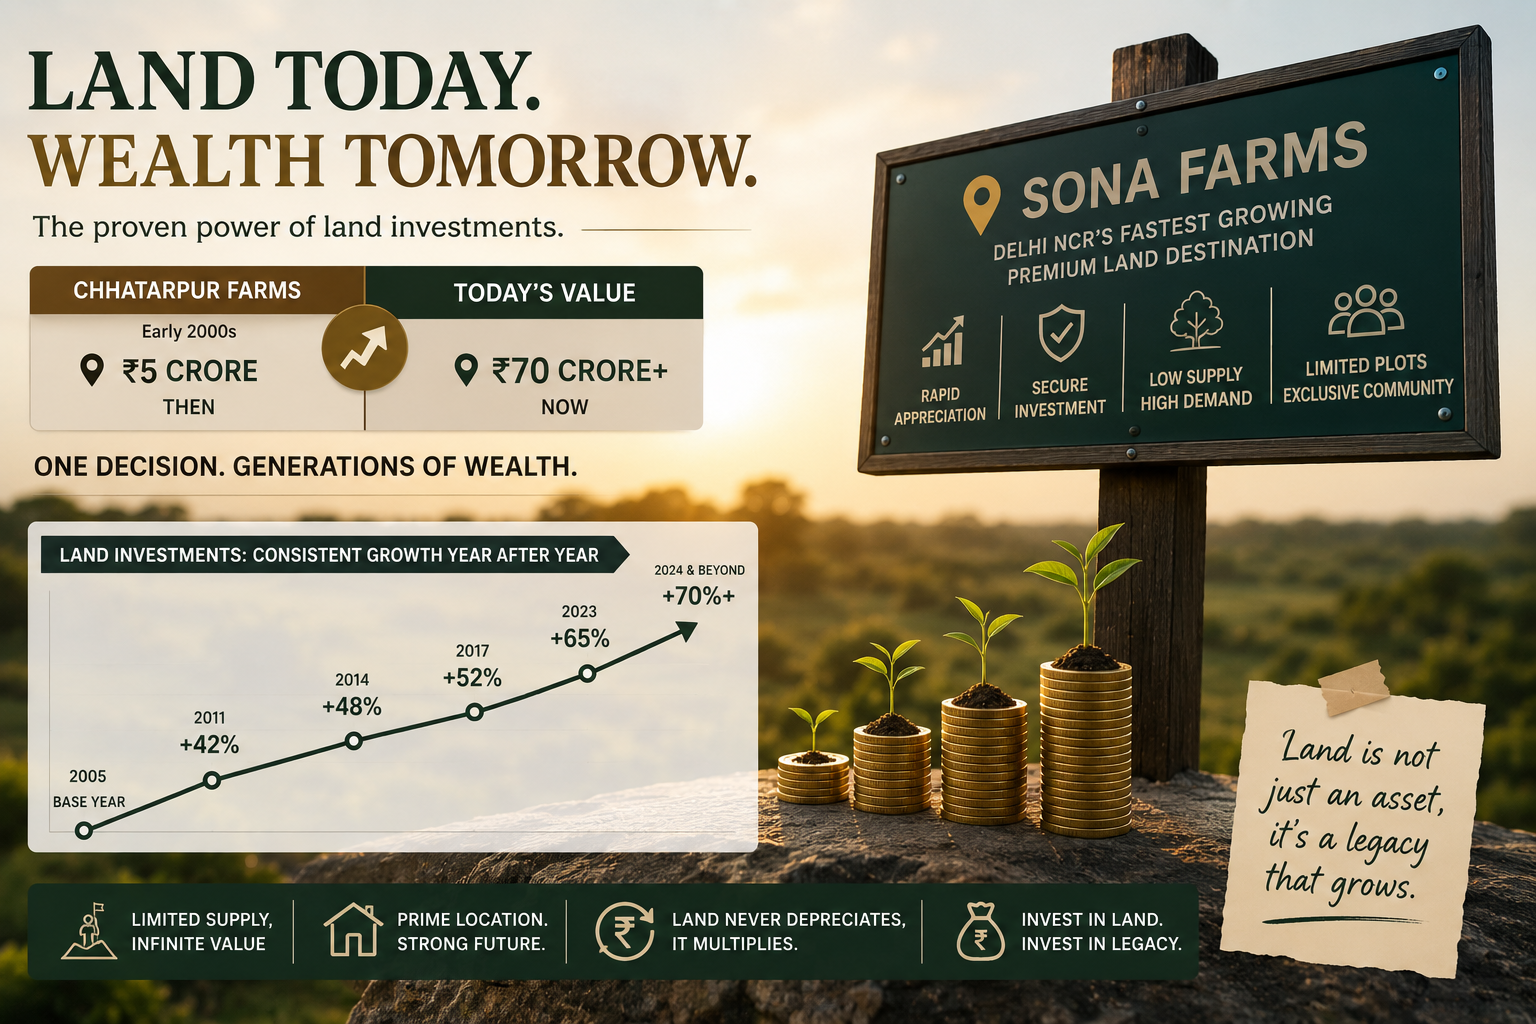
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.