The Subsidized Parcel: Why Retail Advertising Is Underwriting America's Race for Two-Hour Delivery
As Walmart and Target turn physical store networks into localized dispatch points, the escalating overhead of rapid fulfillment is no longer supported by membership fees alone.

Inside distribution corridors across the Inland Empire and outer Dallas, the spatial economics of American ecommerce are undergoing an expensive compression. Amazon has steadily partitioned its national distribution grid into discrete regional zones to push delivery windows below the four-hour mark. Simultaneously, Walmart and Target are marshaling their physical footprints to stage inventory within minutes of residential driveways. What was initially conceived as an occasional convenience for household emergencies has morphed into baseline consumer expectation, despite unit logistics costs that remain stubbornly resistant to standard margin formulas.
For traditional department stores and pure-play online merchants, the arithmetic of this speed race is brutal. Moving a twenty-dollar basket containing dish soap and breakfast cereal via point-to-point courier typically consumes more in packaging, store-floor labor, and driver dispatch than the gross profit generated by the goods themselves. While Target routes more than ninety-five percent of its digital volume through its physical store fleet, absorbing the friction of in-aisle picking, Amazon has committed billions to dedicated sub-same-day facilities situated immediately adjacent to top metropolitan statistical areas.
The Disappearing Last-Mile Margin
The core vulnerability lies in consumer resistance to itemized fulfillment charges. Decades of free-shipping promotions have conditioned American shoppers to treat logistics as an intrinsic utility rather than a paid service. Consequently, platforms have attempted to bundle these costs into annual subscription schemes: Amazon Prime at $139, Walmart+ at $98, and Target's repositioned Circle 360 at $99. Yet these recurring membership fees rarely cover the cumulative delivery overhead of a household that orders three or four times a week.
The economics of transporting twelve-dollar laundry detergent across a suburb within ninety minutes fail entirely without an auxiliary revenue stream tethered to the search query.
The fiscal mechanism bridging this gap is the explosive expansion of retail media networks. Amazon generated tens of billions of dollars in high-margin advertising revenue over the past four quarters, largely by auctioning search placements to third-party merchants and consumer packaged goods conglomerates. Walmart Connect and Target's Roundel arm operate on comparable principles, commanding operating margins estimated in the sixty to seventy percent range. In effect, digital ad real estate has become the direct financial guarantor of the delivery van.
Friction at the Periphery
This ad-funded fulfillment model now faces dual pressures from shifts in consumer behavior and incoming competitive models. As middle-income American households grapple with cumulative inflation and tighter discretionary budgets, basket compositions are skewing heavily toward private-label staples and margin-dilutive groceries. When shoppers trade down from branded pantry goods to generic alternatives, the willingness of consumer brands to bid aggressively for sponsored digital shelf placement inevitably softens.
At the same time, specialized aggregators and social commerce platforms are complicating the landscape. Instacart has diversified into enterprise white-label software to insulate itself from pure grocery delivery volatility, while TikTok Shop has relied on aggressive promotional subsidies to seed its logistics network among younger shoppers. Neither model, however, has unlocked a cheaper physical method for moving tangible freight across suburban asphalt.
The resulting divide favors balance-sheet scale above operational ingenuity. The merchants capable of competing in America's instant-delivery tier are increasingly limited to those that can disguise a logistics loss leader inside an ad-tech business. For smaller specialty sellers and independent brands on platforms like Shopify, the prospect of offering two-hour drop-offs remains an unaffordable structural luxury, cementing an ecommerce landscape bifurcated by capital endurance.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
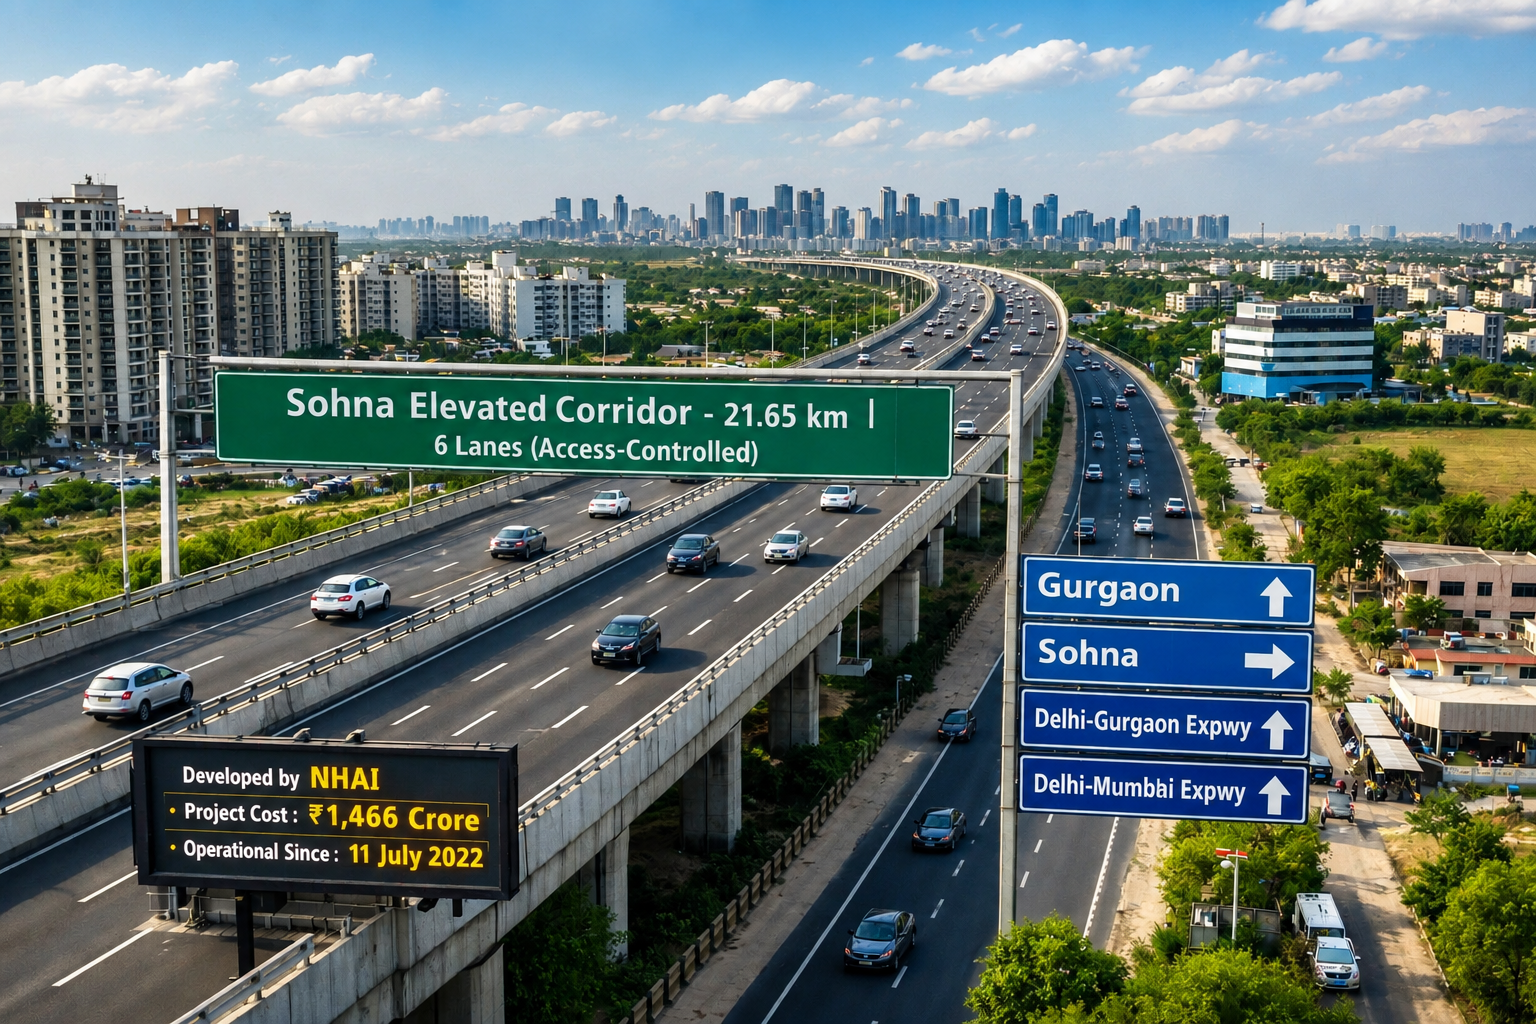
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
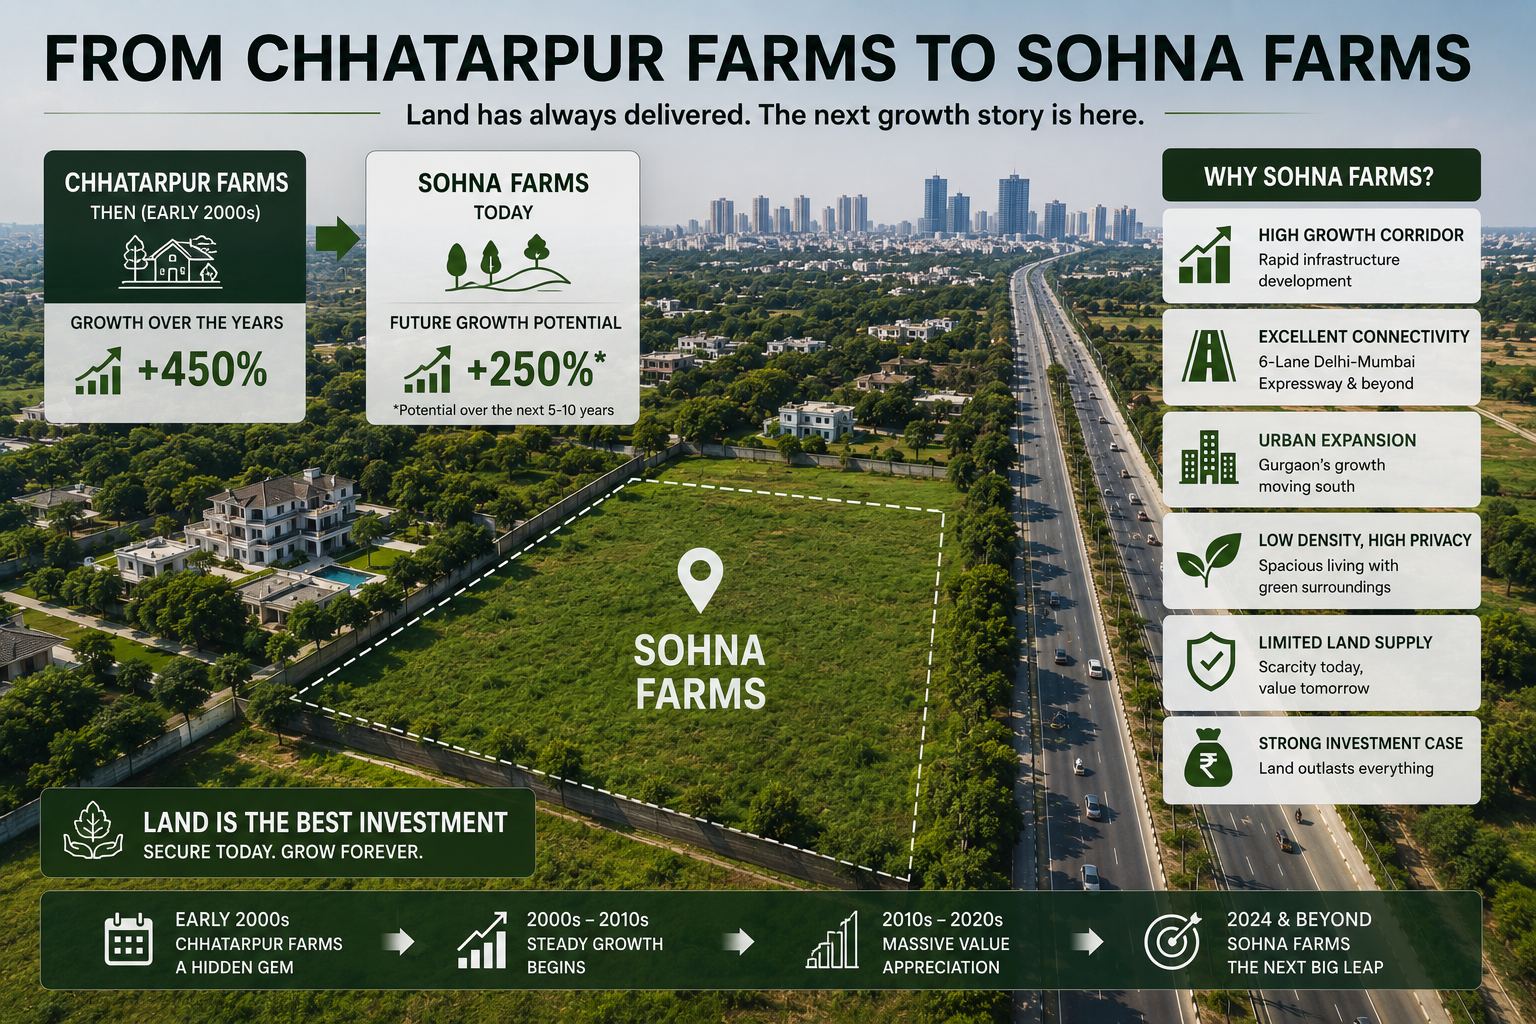
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
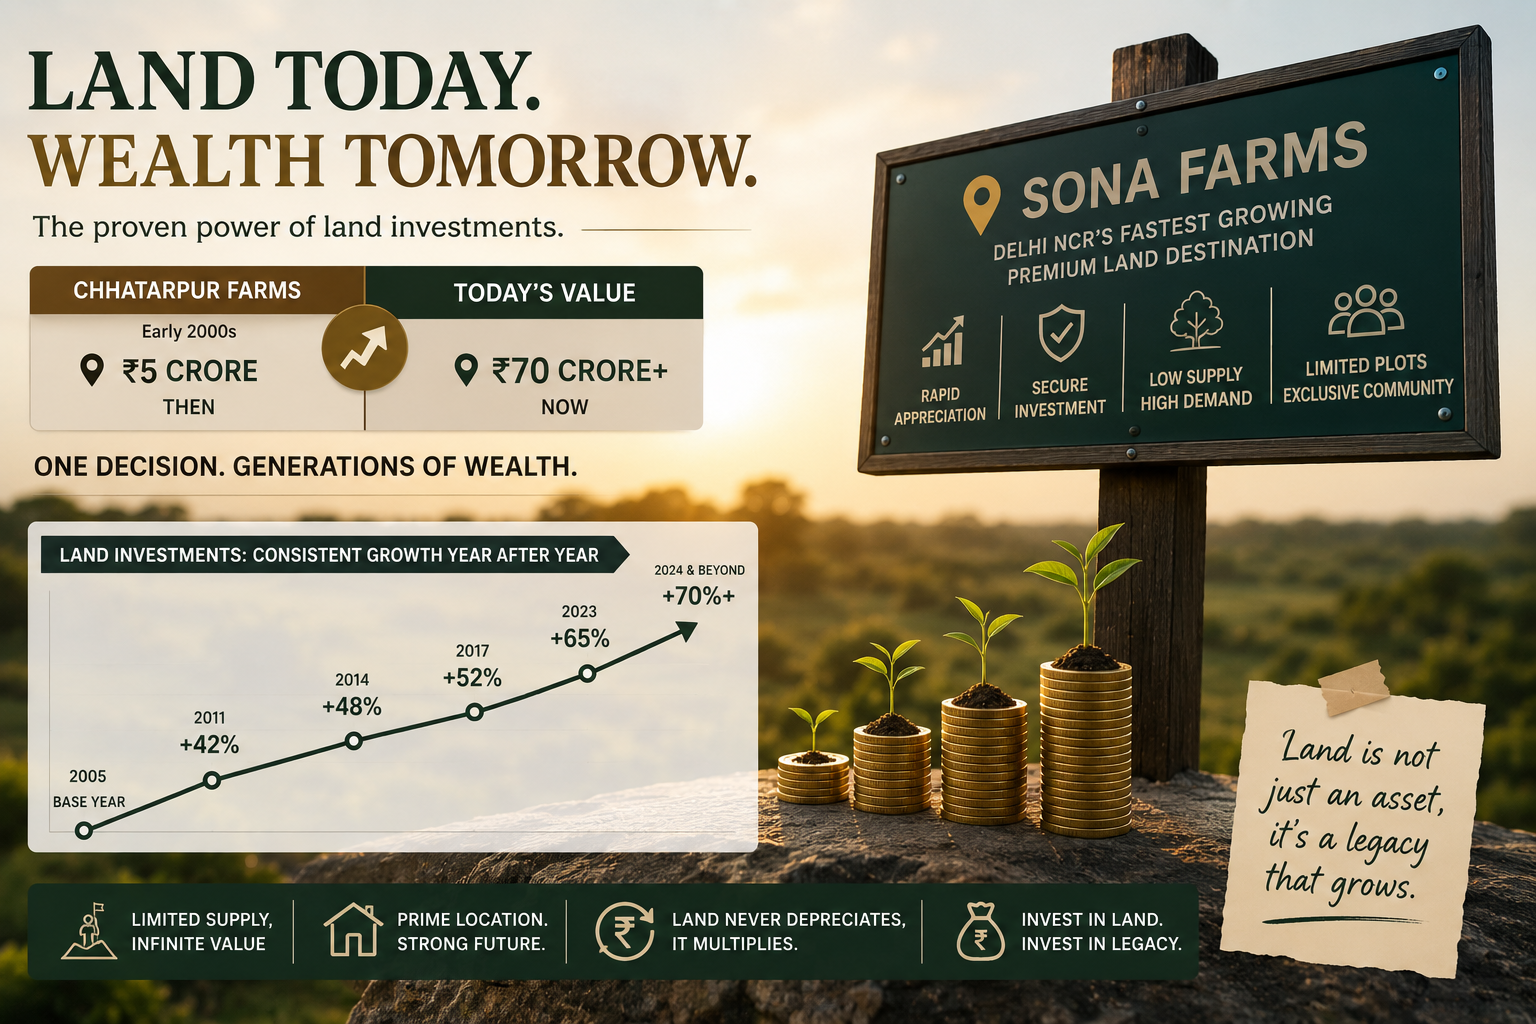
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.