The UK's High Street Reckoning: Navigating Shrinking Basket Sizes and Evolving Habits
British retailers are confronting a persistent shift in consumer expenditure, as inflationary pressures and lifestyle changes reshape purchasing priorities and channel preferences across the nation.

A casual observer walking through the aisles of a Tesco Extra or a Sainsbury's Local might notice a subtle yet pervasive change: the average shopping trolley appears less laden. While headline inflation figures have moderated, the cumulative effect of a sustained cost-of-living crisis has embedded new purchasing behaviours within the UK populace. This dynamic presents a significant challenge for retailers, requiring a strategic re-evaluation beyond simply adjusting prices.
The phenomenon extends beyond grocery. Disposable income, which once fuelled discretionary spending on fashion and homewares, now faces considerable constraint. Companies like ASOS and Next have reported varying fortunes, reflecting a market where consumers are increasingly discerning about non-essential purchases, often prioritising value or specific brand loyalty rather than impulse buying.
The Pressure on Basket Value
Analysis of recent retail data indicates a consistent trend of smaller transaction values across multiple sectors. Consumers are not necessarily reducing the frequency of their shopping trips, but rather the volume and price point of items acquired per visit. This is particularly evident in grocery, where shoppers are more frequently opting for own-brand products or discount retailers, a migration that impacts the margins of mainstream supermarkets.
Even Marks & Spencer, often seen as a bellwether for mid-to-premium consumer sentiment, has navigated this environment through a renewed focus on value and efficiency in its food division, while its clothing and home segments continue to adapt to a more cautious spending climate. The emphasis has shifted from broad appeal to targeted propositions.
The online delivery landscape, once a rapid growth engine, also illustrates this recalibration. While services like Ocado, Deliveroo, and Just Eat still command significant market share, the era of exuberant ordering and large, spontaneous baskets has given way to more considered, need-driven purchases, often influenced by promotional offers or subscription benefits. The novelty factor has largely dissipated, replaced by a functional utility.
Retailers must recognise that the 'new normal' for consumer spending is not merely a temporary dip but a more fundamental reordering of priorities, demanding sustained agility.
The Long Shadow of Inflation
While the annual rate of inflation has declined from its peaks, the accumulated price increases over the past two years mean that household budgets remain stretched. Real wages have struggled to keep pace, leaving less surplus cash for non-essential goods and services. This creates a challenging environment for categories such as fashion and electronics, where purchase cycles are lengthening and consumers are seeking greater longevity from their acquisitions.
This protracted period of financial pressure has also accelerated the adoption of more frugal habits. Shoppers are increasingly comparing prices across multiple platforms, utilising loyalty schemes more diligently, and deferring larger purchases. This behavioural entrenchment suggests that even as economic conditions improve, a portion of these cost-saving measures may persist, fundamentally altering the baseline for consumer demand.
For retailers operating in the UK, the imperative is clear: understand the nuance of these evolving spending patterns. Strategies focused solely on volume growth may prove unsustainable. Instead, a renewed emphasis on value proposition, operational efficiency, and a deep understanding of the constrained but selective consumer will be critical for maintaining relevance and profitability in a market that has fundamentally shifted.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
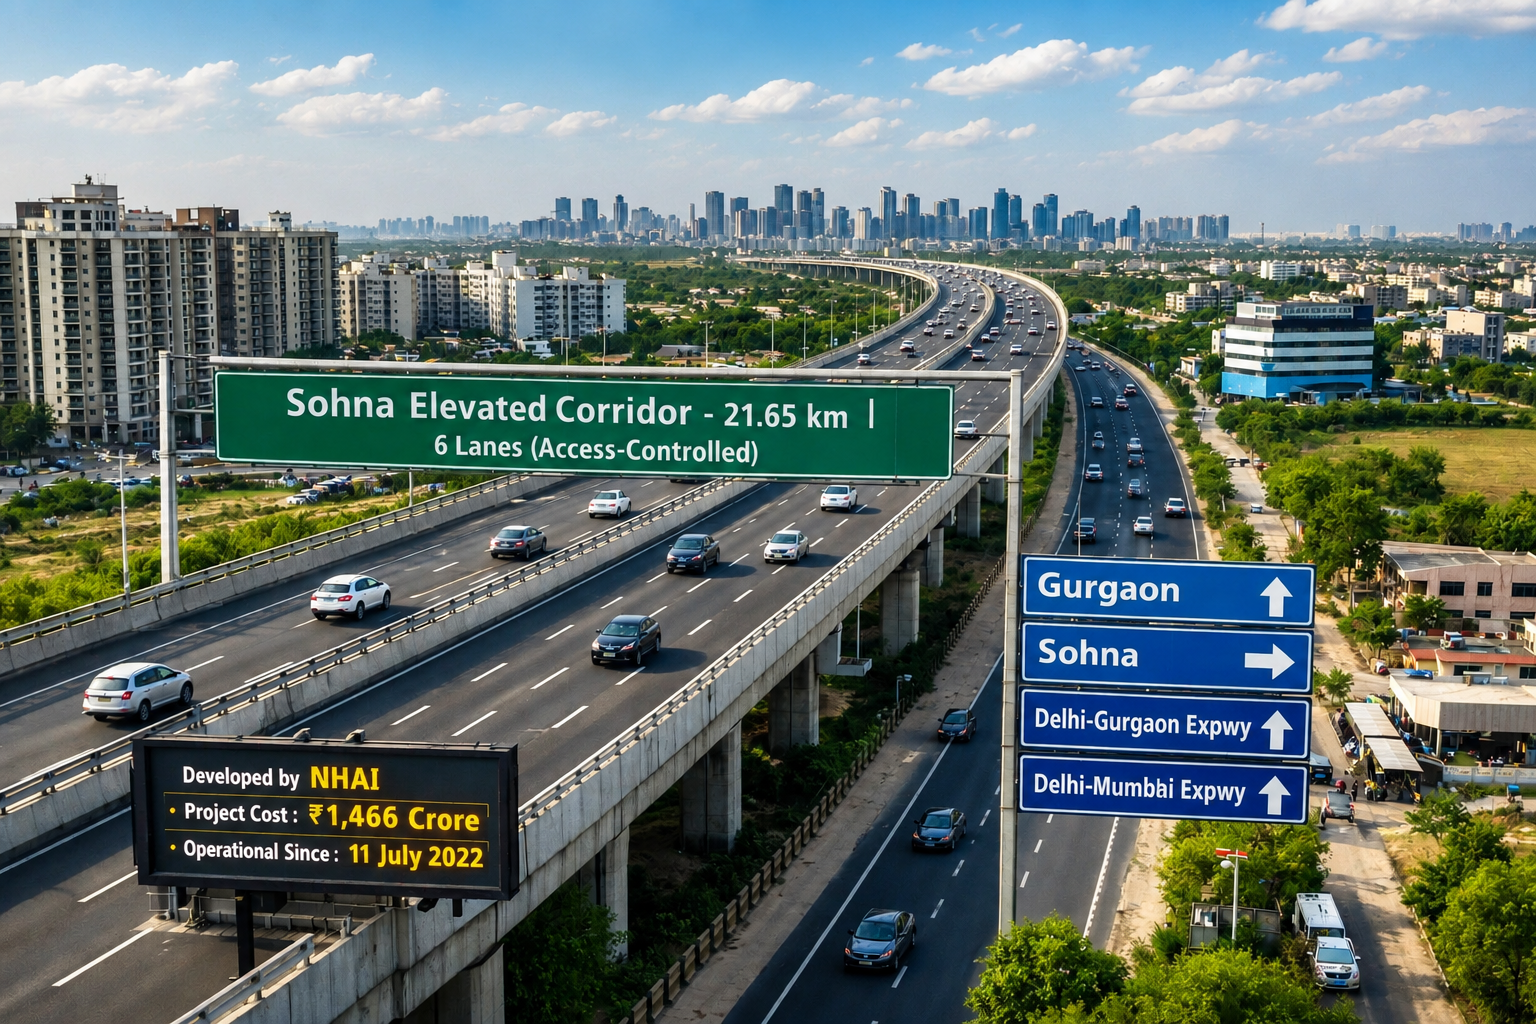
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
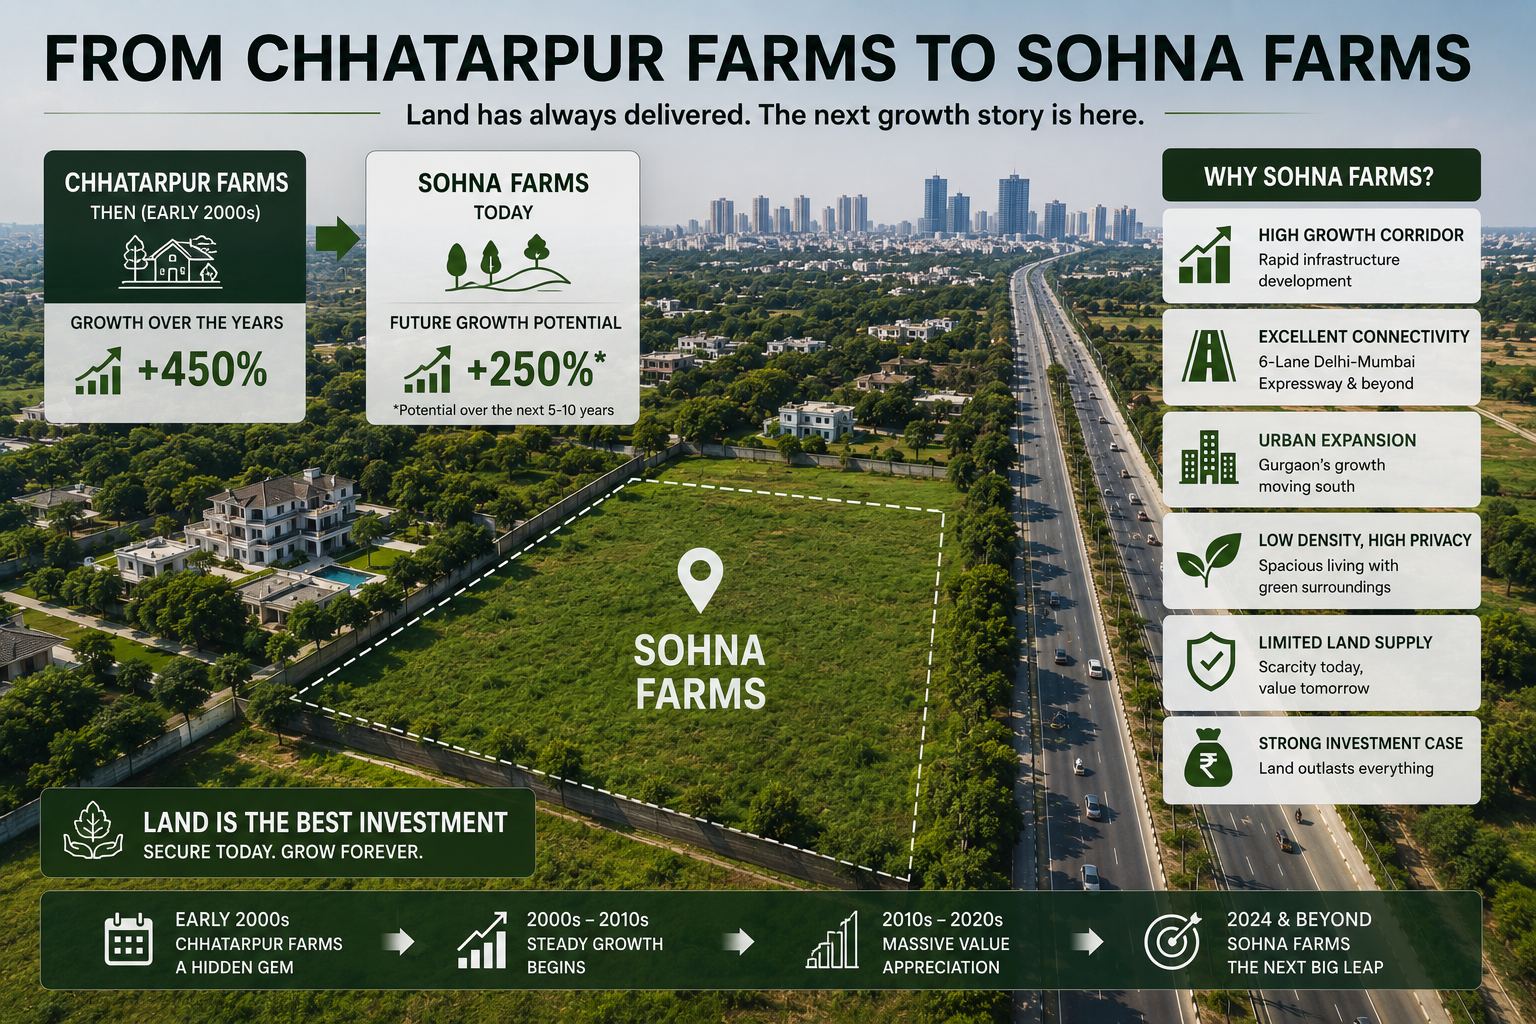
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
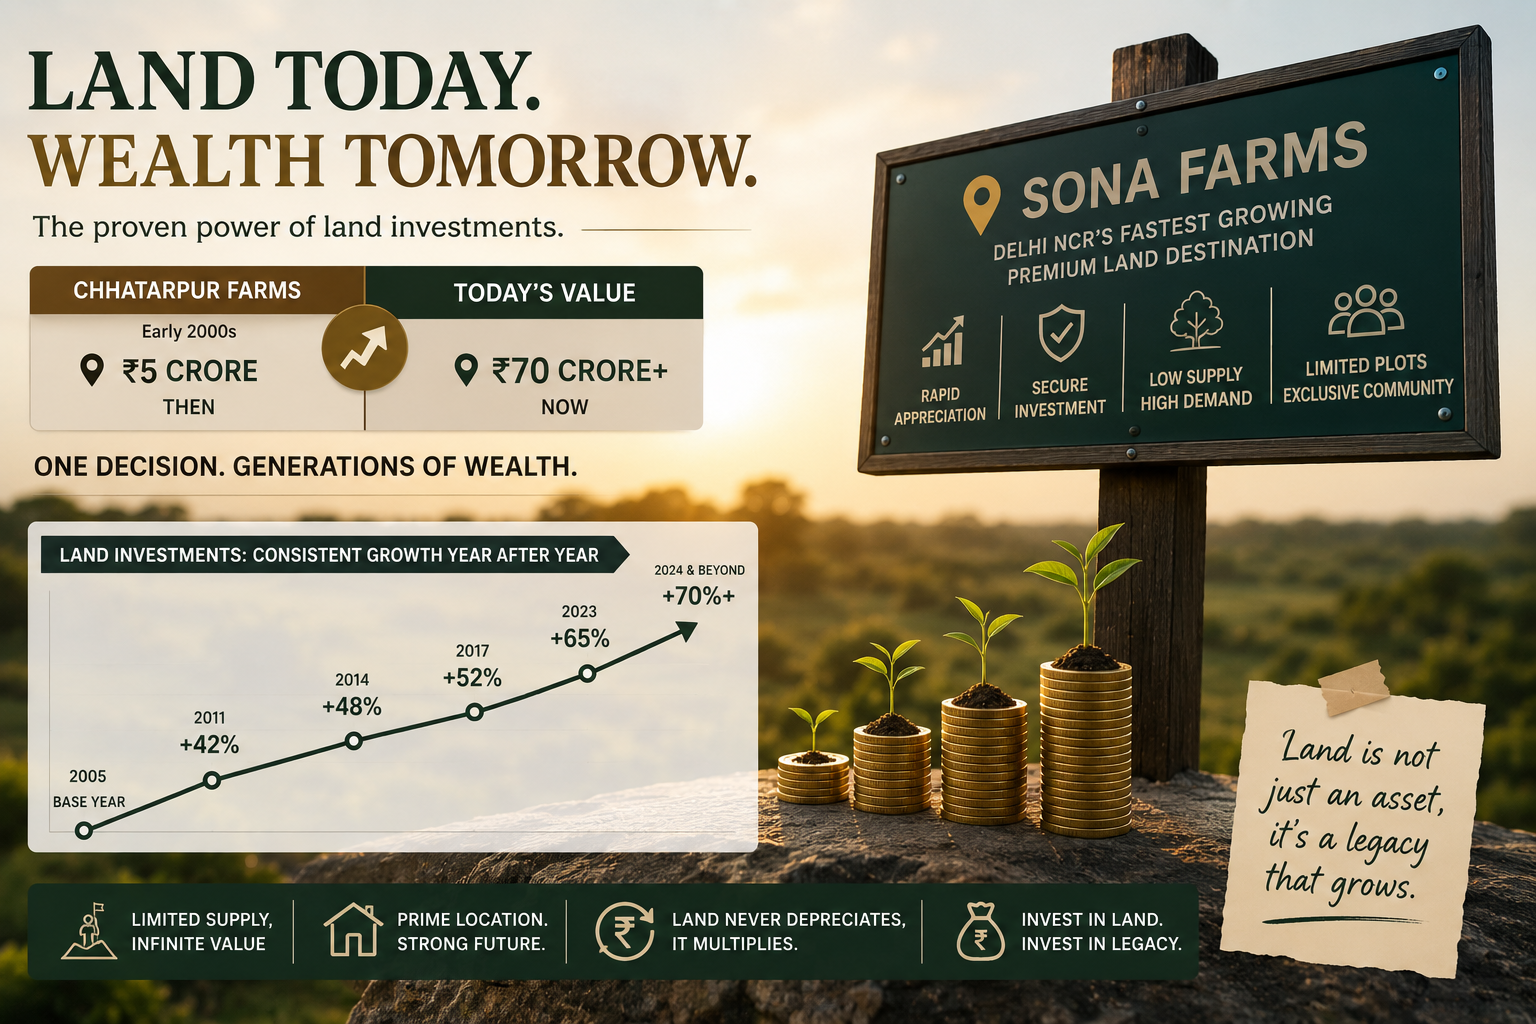
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.