The UK's Last-Mile Predicament: Retailers Brace for Elevated Delivery Costs
British retailers are confronting an intractable challenge in optimising urban logistics, as rising operational expenses and evolving consumer expectations threaten profit margins and reshape delivery strategies across the nation.

The sight of a Marks & Spencer Food delivery van navigating narrow London streets, or an ASOS parcel dropped at a rural Scottish doorstep, encapsulates a complex logistical ballet. Behind these seemingly effortless consumer touchpoints lies a system under immense pressure, with British retailers facing persistently high 'last-mile' delivery costs. This intricate web of transportation, often the most expensive leg of the supply chain, is becoming a critical battleground for profitability in the UK retail sector, impacting everything from groceries to fashion.
Data indicates that last-mile delivery can account for over half of total shipping expenses, a figure that is not merely a reflection of fuel prices but a confluence of factors unique to the UK's geography and consumer behaviour. The nation's dense urban centres, coupled with a growing preference for immediate and flexible delivery options, create a costly operational environment. Unlike some continental European counterparts, the UK's extensive network of older, often congested roadways adds further layers of inefficiency and time commitment to each drop-off.
The Infrastructure Headwind
The physical infrastructure presents a significant hurdle. Historic city layouts, with their absence of extensive loading bays and prevalence of parking restrictions, compel delivery drivers to spend more time per drop. This translates directly into higher labour costs, exacerbated by the ongoing driver shortage that has seen wages increase across the logistics industry. Companies like Ocado and Tesco, with their sophisticated grocery delivery networks, absorb these costs through a combination of membership fees, minimum order values, and, implicitly, through product pricing.
While larger players possess the scale to invest in route optimisation software and electric vehicle fleets, smaller online-only retailers often find themselves at the mercy of third-party couriers whose pricing reflects these underlying challenges. The rise of rapid delivery services from platforms such as Deliveroo and Just Eat, catering to immediate gratification, further intensifies the logistical complexity, requiring ever-closer proximity of stock to consumers and the deployment of a hyper-localised, often gig-economy, workforce.
The persistent demand for swift and precise delivery, often without a corresponding willingness to pay its true cost, is forcing a re-evaluation of retail operating models.
Moreover, returns processing represents another substantial cost, particularly for fashion retailers like Next and ASOS. The reverse logistics chain, from consumer back to warehouse, can be as intricate and costly as the outbound journey. Each returned item incurs handling, inspection, and potential repackaging costs, eroding margins that are already tight in a competitive market.
Technology as a Mitigator, Not a Panacea
Technological advancements offer partial solutions but are not a panacea. Autonomous delivery vehicles and drone technology remain largely experimental or restricted to specific environments. Warehouse automation, while improving first-mile efficiency, does not directly address the final leg of the journey through congested residential areas. Retailers are actively exploring innovative hub-and-spoke models, micro-fulfilment centres within urban areas, and enhanced predictive analytics to group deliveries more efficiently.
Ultimately, the UK's last-mile predicament demands a multi-faceted approach. It may involve a greater consumer acceptance of longer delivery windows in exchange for lower costs, or a broader implementation of click-and-collect options. For retailers, the challenge is to strike a balance between meeting consumer expectations and maintaining financial viability in an operational environment that continues to present unique and substantial costs.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
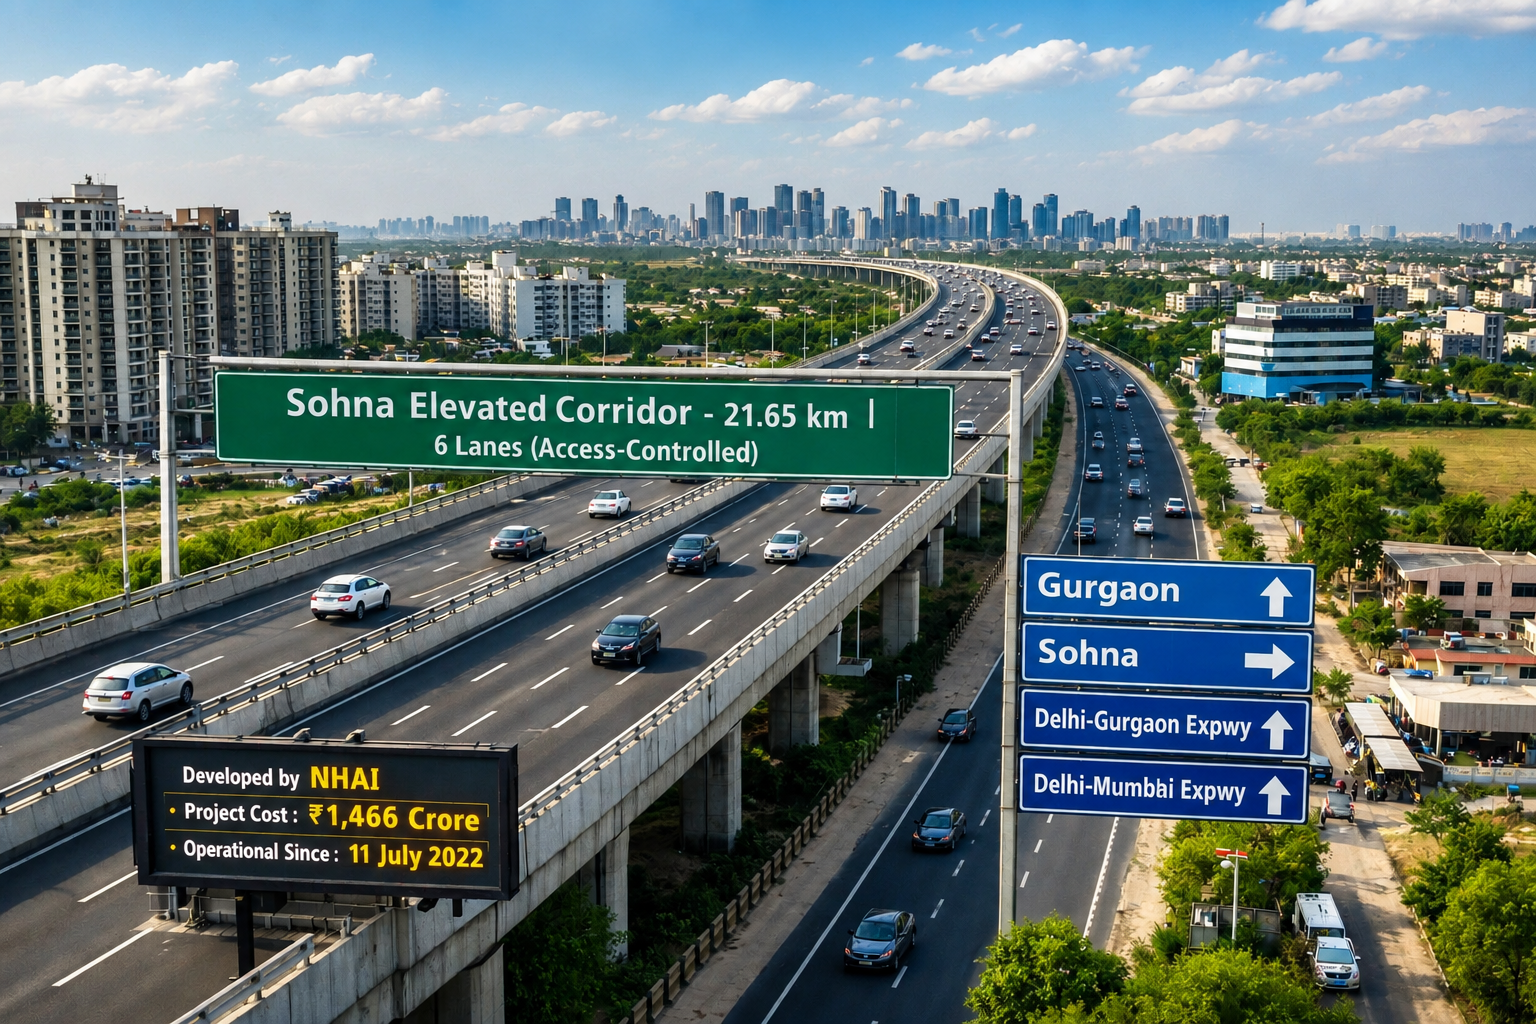
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
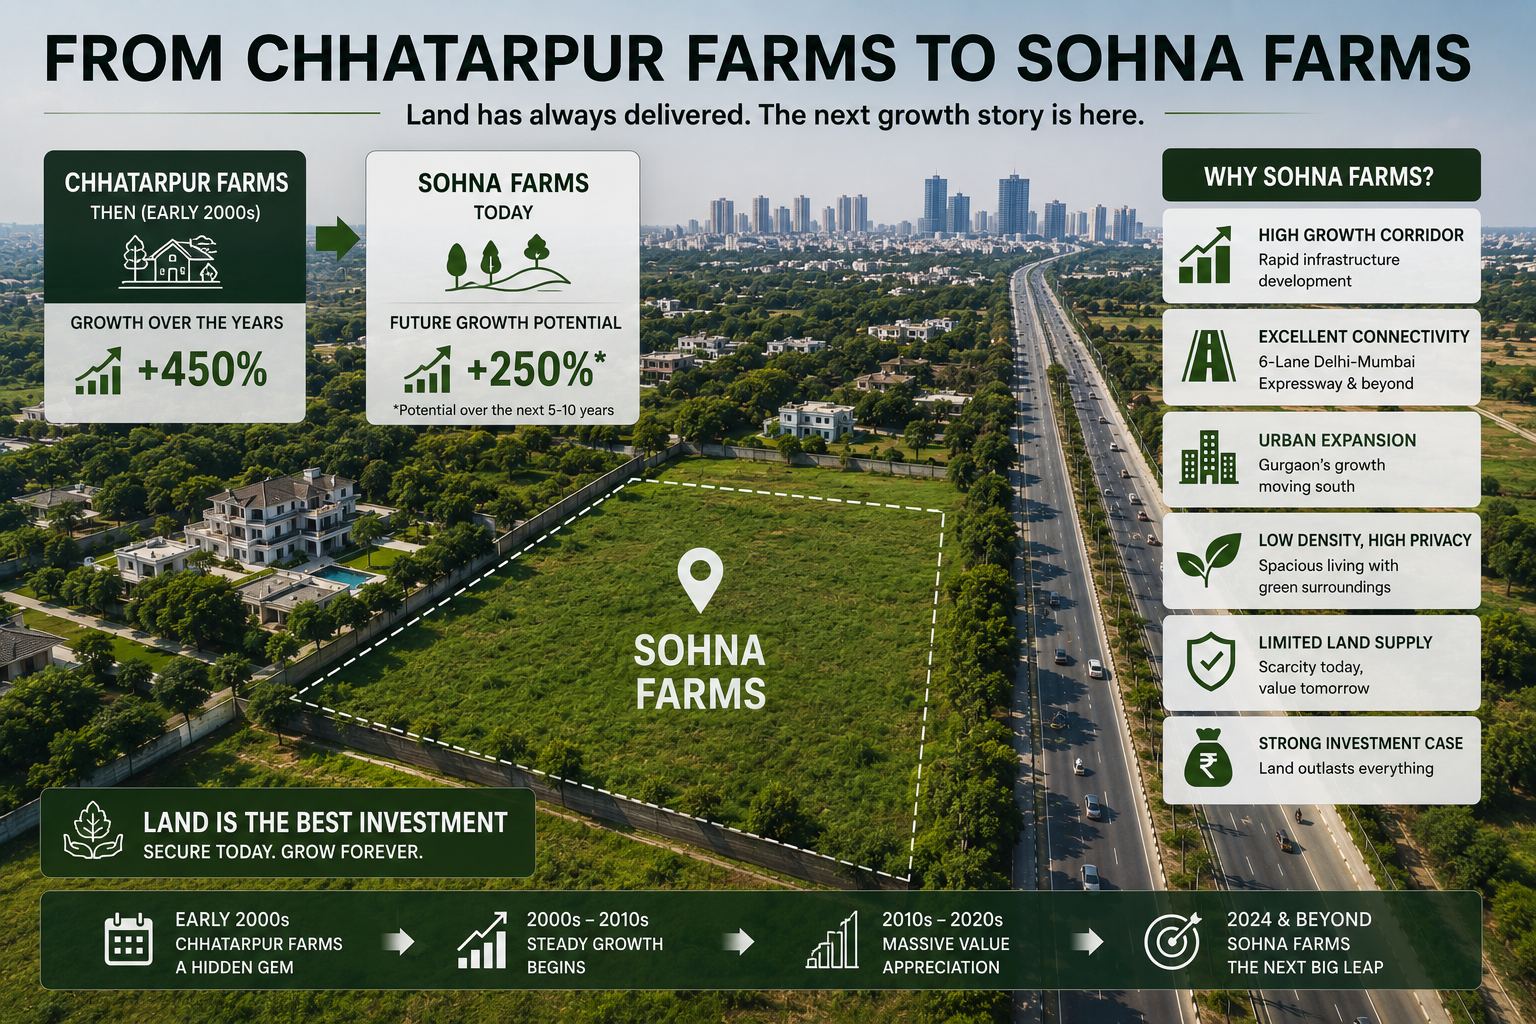
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
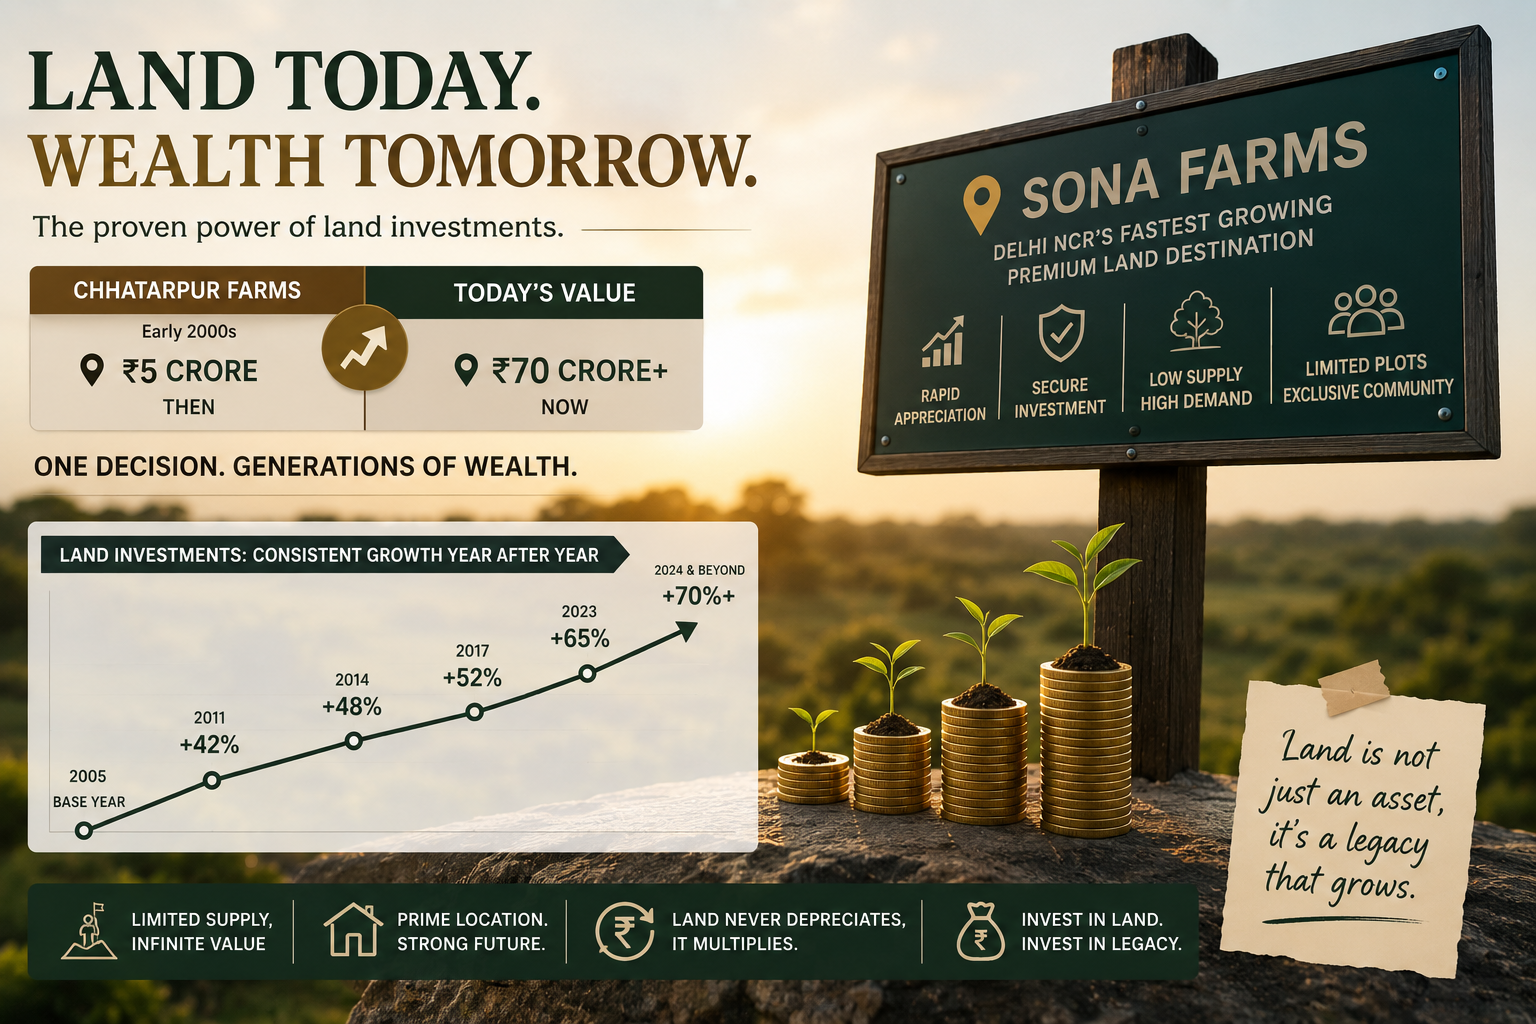
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.