The UK's Marketplace Paradox: Consolidation Amidst Continued Expansion
Despite a crowded digital landscape and persistent economic headwinds, Britain's online marketplaces are demonstrating remarkable resilience and strategic evolution, even as consumer spending habits shift dramatically.

When a customer finalises a grocery order with Tesco, selecting a delivery slot and adding a non-food item like a new frying pan, they are interacting with an increasingly complex retail ecosystem. This seemingly routine transaction represents the strategic pivot of established retailers into sophisticated marketplace models, a trend that is reshaping the commercial fabric of the United Kingdom and warrants close examination.
For years, pure-play marketplaces like eBay and Amazon dominated the digital retail narrative. Their expansive inventories and logistical prowess set the benchmark. However, the last half-decade has seen a proliferation of new models and an aggressive expansion by traditional high street names. Marks & Spencer, for instance, has broadened its online offering beyond its own labels to include third-party fashion and home brands, effectively becoming a curated platform. Next has similarly pursued a partner-brand strategy through its 'Next Brand' initiatives, integrating other labels into its strong e-commerce infrastructure.
This shift is not merely about increasing product assortment; it is a fundamental re-evaluation of the retailer's role. Faced with rising operational costs, intense competition, and volatile consumer demand, many UK companies view marketplaces as a capital-light method to expand reach and revenue. Instead of holding vast inventories, they leverage other sellers' stock, reducing working capital requirements and mitigating risk.
The pandemic accelerated digital adoption across all demographics, solidifying online shopping as a deeply ingrained behaviour. Even as high street footfall recovers, the expectation for immediate availability and diverse selection online persists. This has created fertile ground for services like Deliveroo and Just Eat, which, while primarily food delivery platforms, have begun to experiment with non-food verticals, effectively becoming local delivery marketplaces for convenience stores and pharmacies.
Operational Efficiencies and Logistical Headwinds
Operating a successful marketplace in the UK presents its own set of challenges, particularly concerning logistics and customer experience. While companies like Ocado have built highly automated and efficient fulfilment networks, replicating this infrastructure for a broad spectrum of third-party sellers is complex. Quality control, delivery consistency, and returns processing become critical pain points, often outsourced or managed through elaborate partner agreements. The cost of 'last mile' delivery in densely populated urban areas, exacerbated by fuel price fluctuations and labour shortages, continues to pressure margins.
The true measure of a marketplace's success lies not just in its breadth of offerings, but in its seamless integration of disparate vendors and the consistent delivery of a unified brand experience to the end consumer.
Furthermore, the competitive intensity among UK marketplaces remains high. While ASOS has navigated a challenging fashion retail environment, its ability to maintain its marketplace position relies on constant innovation in customer engagement and supplier relationships. The ongoing economic squeeze on household budgets means consumers are more discerning, often prioritising value and convenience, pushing marketplaces to optimise pricing and delivery options.
The Evolution of the Omni-Channel Strategy
The future trajectory for UK marketplaces likely involves deeper integration between online and physical retail. Click-and-collect services, pioneered by retailers like John Lewis and Next, are becoming a standard offering for marketplace participants, blurring the lines between pure-play e-commerce and traditional retail. This 'omni-channel' approach allows consumers to leverage the convenience of online browsing with the immediacy of physical pickup, offering a competitive edge against pure-online competitors.
Consolidation is another foreseeable trend. As smaller, niche marketplaces struggle to achieve scale and profitability in a tighter economic climate, larger players with robust capital and logistical infrastructure may acquire them. This could lead to fewer, but more powerful, platforms dominating the UK market, each offering an extensive range of products and services, further cementing their role in the daily lives of British consumers.
News Legacy maintains editorial independence. Some recommendations may contain affiliate links. We earn from qualifying purchases at no additional cost to you. Read our policy.
Read Next
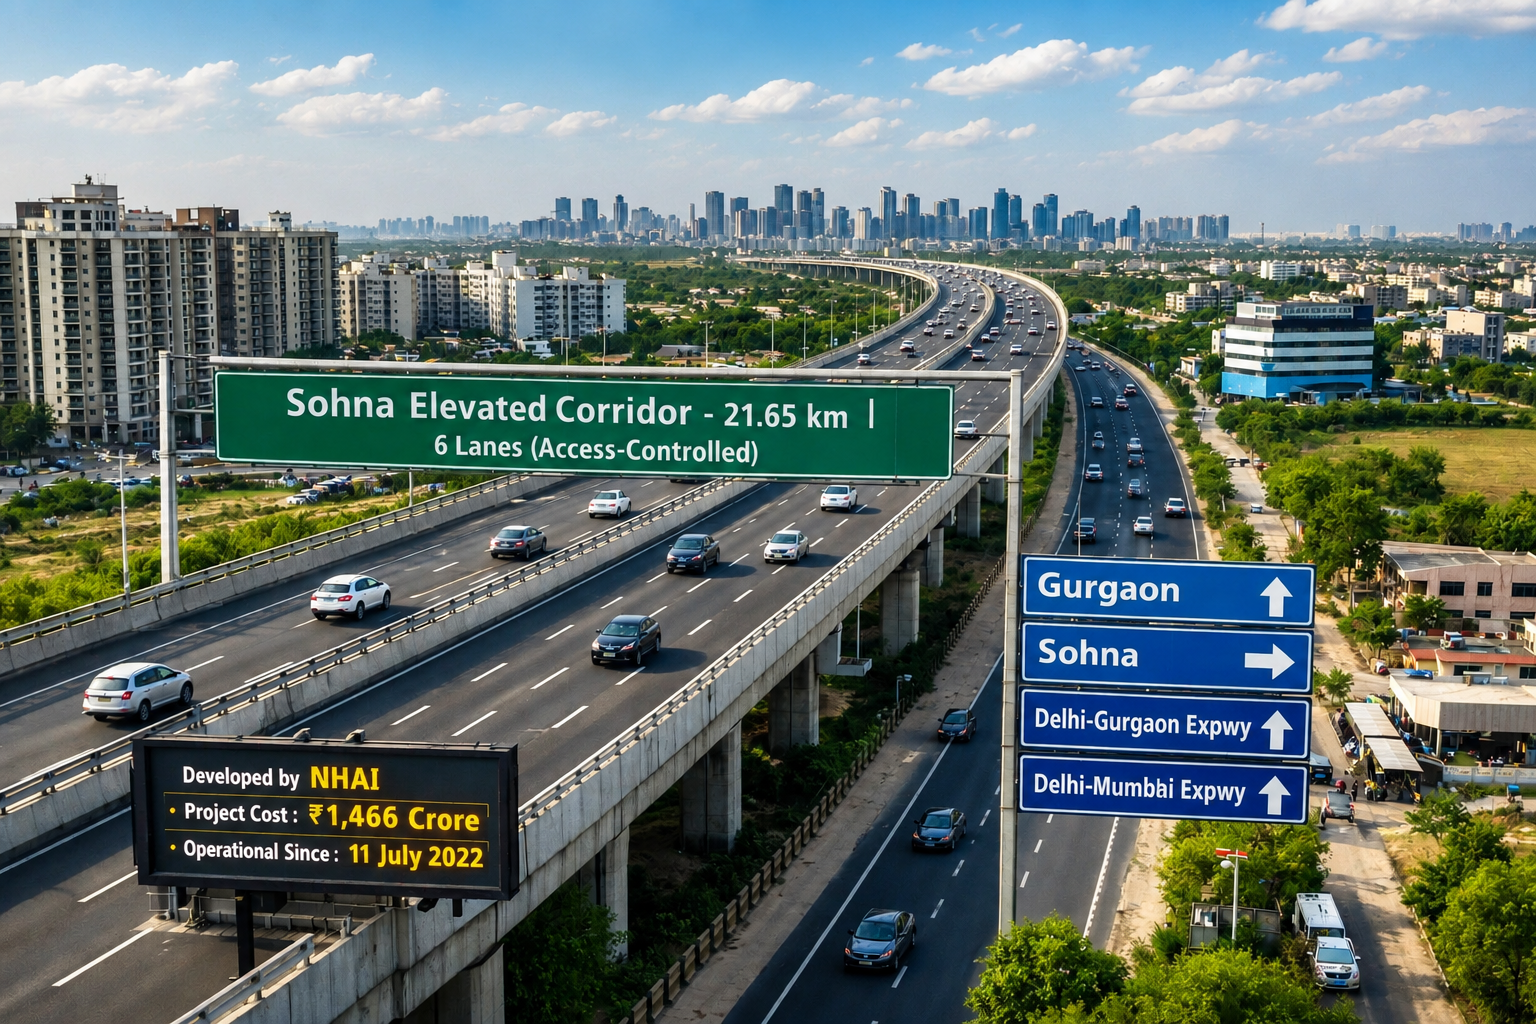
Is Sohna Really the Next Chhatarpur?
Three decades after Chhatarpur redrew South Delhi's map for space, privacy and exclusivity, a familiar pattern is now taking shape further south, and Sohna is where the smart money is beginning to look.
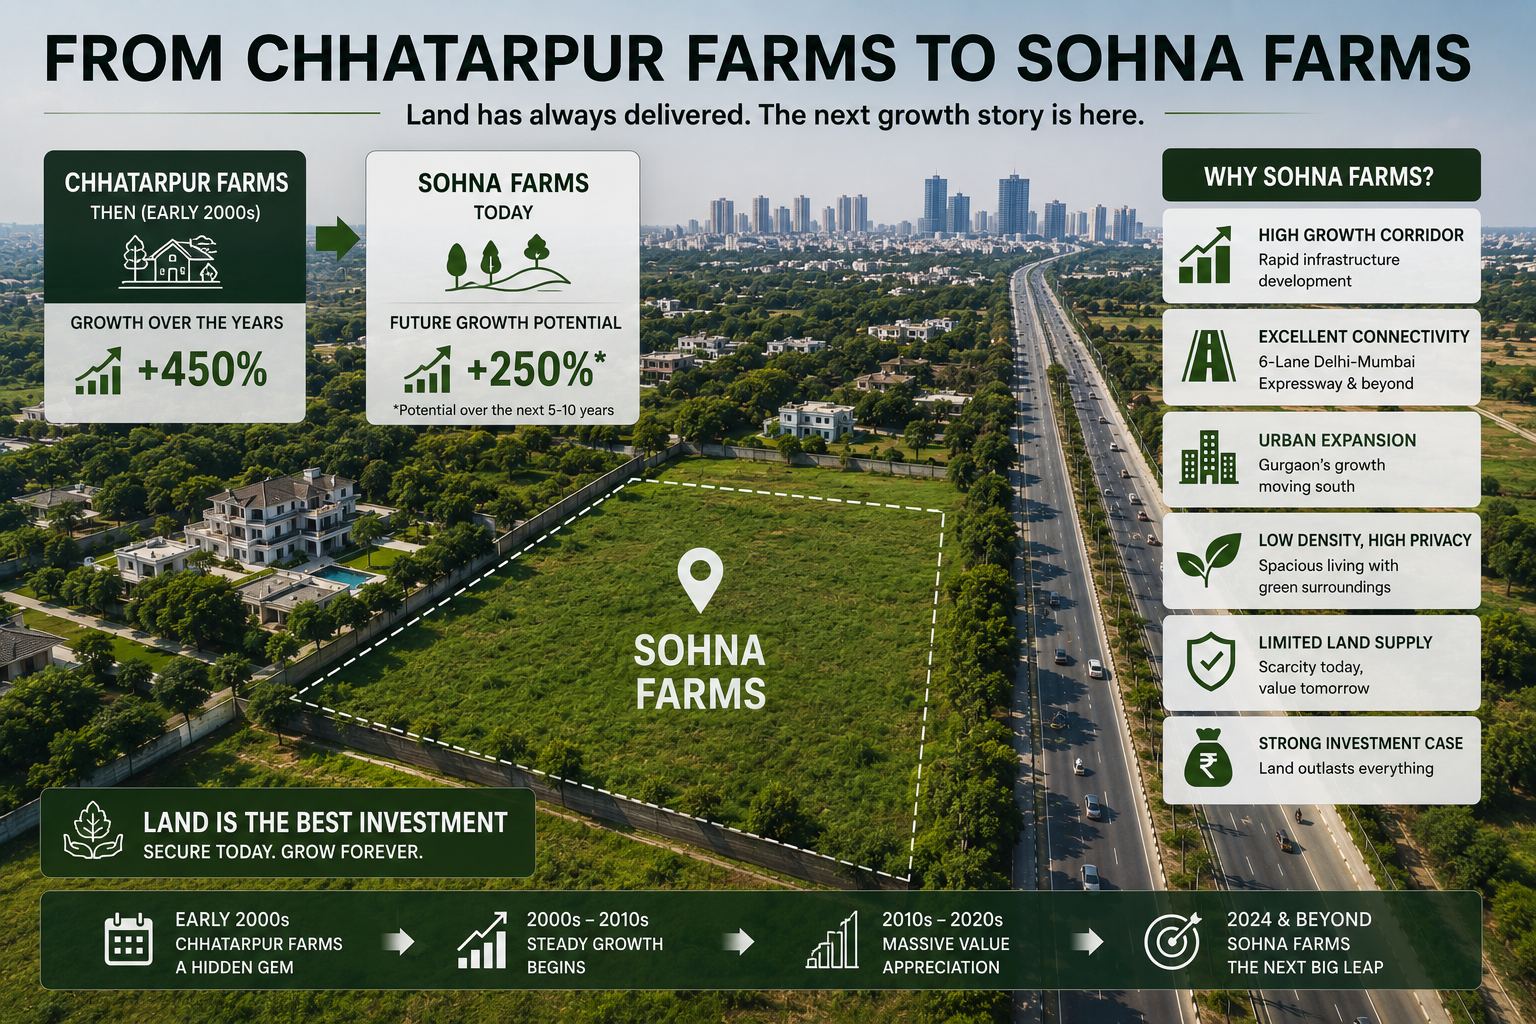
How Chhatarpur Farmhouses Created Multi-Crore Wealth for Early Buyers
What a quiet corner of South Delhi can teach investors about land, scarcity, and long-term wealth creation.
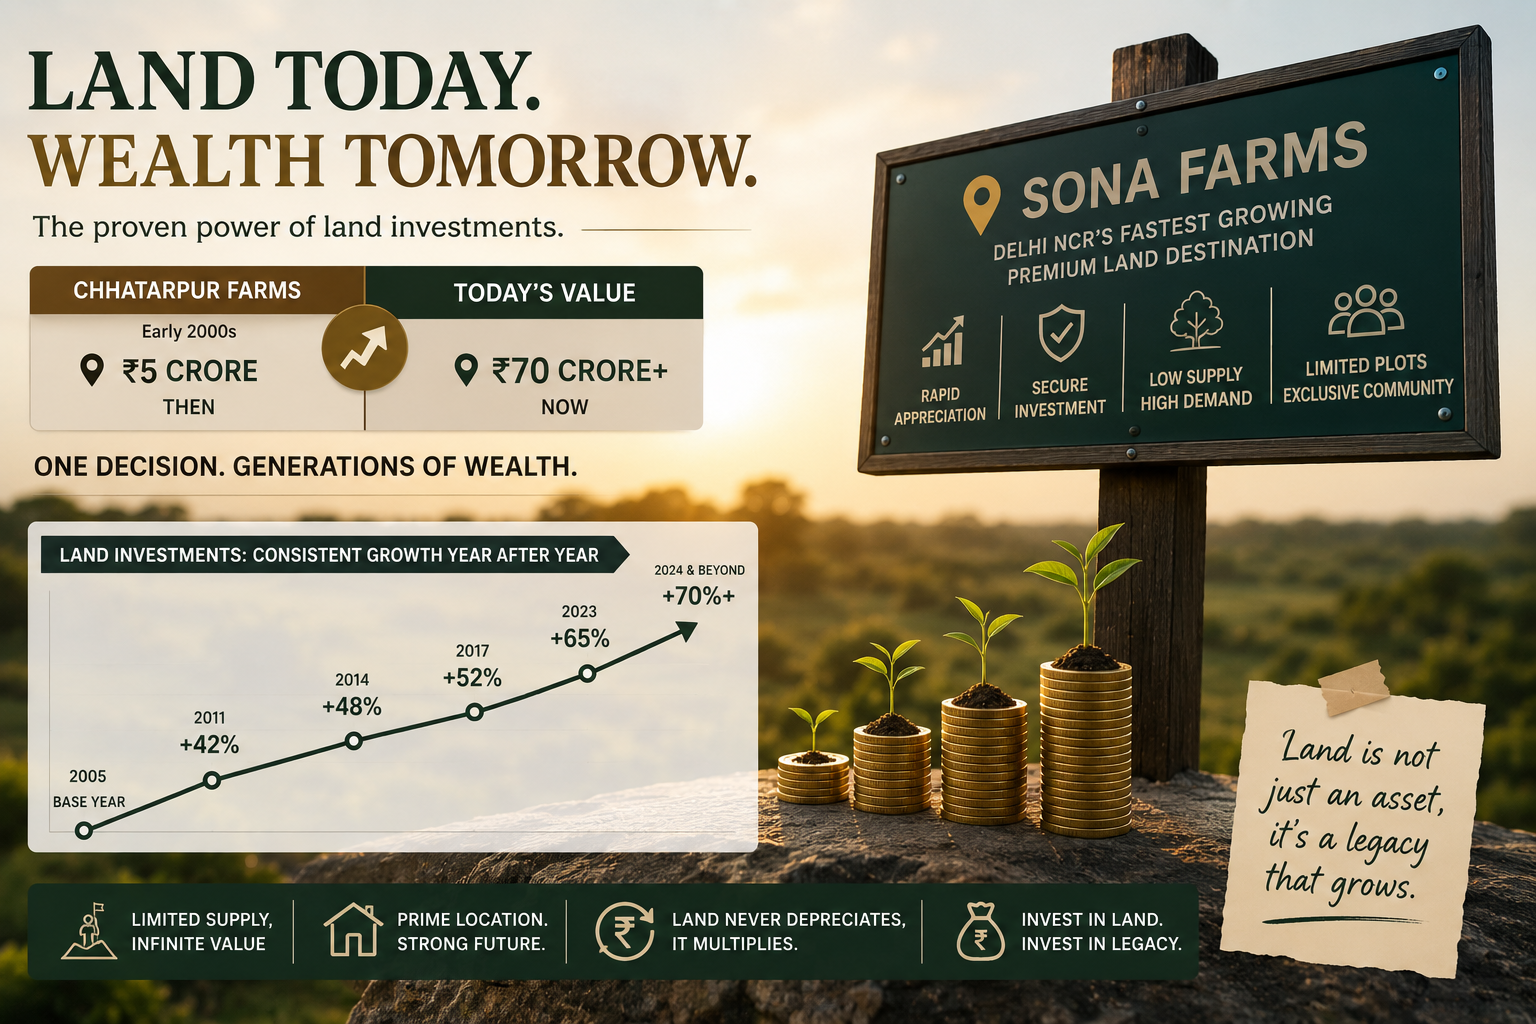
The ₹5 Crore Land Purchase That Became Worth ₹70 Crore
What the Story of DLF Chhatarpur Farms Reveals About Wealth Creation Through Premium Land Ownership
One short email. Stories you can use.
A free, occasional email from our editorial team with our latest features, explainers and reads. Unsubscribe any time — your email stays with us.